


 |
市場調查報告書
商品編碼
2124090
馬達監測:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Motor Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
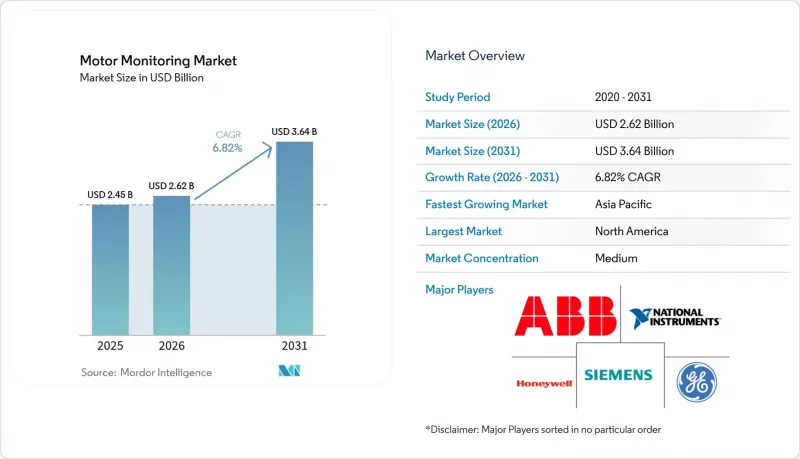
根據 Mordor Intelligence 預測,汽車監控市場規模將從 2025 年的 24.5 億美元成長到 2026 年的 26.2 億美元,到 2031 年將達到 36.4 億美元,2026 年至 2031 年的複合年成長率為 6.82%。
本報告按產品(硬體、軟體等)、部署方式、監測方法(振動分析、馬達電流特性等)、終端用戶產業(石油天然氣、能源電力等)、馬達類型(AC馬達、DC馬達等)和地區進行細分。市場預測以美元計價。
全球馬達監測市場趨勢與洞察
擴大預測性維護平台的應用
目前,預測性維護平台將振動、電流、聲學和熱學數據與機器學習模型結合,實現了91%的異常檢測準確率,並將故障率降低了30%至50%。鋼鐵製造商能夠提前40小時預測故障,而礦業營運商則透過避免意外停機,獲得了9倍的投資回報。隨著雲端分析將原始感測器數據轉化為主動式工單,從而減少備件庫存和加班時間,其經濟效益正變得越來越明顯。
快速過渡到無線、無電池感測器網路
從馬達磁場中提取微瓦級能量的能源採集設計無需更換電池和佈線,顯著降低了生命週期成本。 TDK 的 i3 和其他商用模組整合了板載邊緣 AI,可將運作延長 50%,同時在工業設施中建構自癒網狀網路。這些無線節點能夠對船舶機艙和海上鑽井平台等區域進行監控,而這些區域的監控通常成本高且危險。
高額的初始資本支出(CAPEX)和投資報酬率的不確定性
全面部署該系統通常需要超過 10 萬美元的成本,包括感測器、閘道器和整合費用。對於中型工廠而言,這筆費用可能成為採用該系統的障礙,儘管它有可能降低 10% 到 40% 的維護成本。案例研究表明,早期模型在設備更換時可能會出現資料偏差,需要額外成本來重新訓練演算法,從而延長投資回收期。為了降低成本敏感型買家的財務風險,供應商正在實施諸如訂閱服務和分階段試點部署等措施。
細分市場分析
隨著企業擴大將整合、分析和生命週期最佳化外包,服務業預計將以 9.34% 的複合年成長率成長。雖然硬體在 2025 年仍將佔總收入的 68.45%,但在複雜的多供應商環境中,數據解讀的重要性已超過感測器採購。艾默生以 82 億美元收購 NI 的交易凸顯了向利潤更高的業務收益流的轉變,並將持續監控整合到更廣泛的自動化合約中。
硬體製造商正透過捆綁式閘道器、雲端連接器和託管儀表板,將自身重新定位為解決方案供應商。 Regal Rexnode 的 Perceptiv 平台整合了現場感測器和分析功能,據報道可將預期故障率降低 55%,並將機器壽命延長 40%。隨著價值從組件轉向洞察,涵蓋設備、軟體和支援的混合經營模式正成為馬達監控市場的標準。
即使到了2025年,本地部署架構仍將佔據73.10%的營收佔有率。這是因為出於延遲和資料主權的考慮,關鍵工廠仍然更傾向於本地控制。然而,隨著網路安全標準的日趨成熟以及5G網路降低回程傳輸成本,雲端採用率正以11.75%的複合年成長率呈現最高成長。Honeywell和Verizon的合作展示了一種日益流行的混合邊緣雲模式,該模式將蜂窩網路智慧整合到計量器中,並將使用數據安全地傳輸到分析中心。
學術研究已指出雲端SCADA整合中存在四大常見漏洞:資源共用、內部威脅、不安全協定和連接性不足。但零信任架構和基於網路的入侵偵測系統的應用正在緩解這些風險。製造商正擴大將深度學習工作負載和車隊基準測試卸載到雲端,同時在本地處理安全關鍵資料。這種模式在不影響運作的前提下,提高了整個汽車監控市場的可擴展性。
區域分析
亞太地區展現最強勁的成長前景,預計2031年複合年成長率將達到9.98%。中國政府的「智慧製造2025」計畫等政策正在推動感測器維修,國內廠商也陸續推出具有成本競爭力的平台以滿足本地市場需求。西門子的「中國加速2.0」計畫和三菱電機「凌凌」品牌下的新產品線便是針對該市場制定專業策略的典範,進一步增強了電機監測市場的成長動能。北美地區將繼續保持其銷售領先地位,預計到2025年將佔據34.70%的市場佔有率,這得益於嚴格的能源效率法規以及對電網和資料中心韌性的投資。Schneider Electric投資7億美元擴建美國五家工廠的計劃表明,供應商正在透過本地化生產來支持聯邦基礎設施項目,這些項目優先考慮能源、水務和製造業領域的基於狀態的維護。在歐洲,永續性法規和循環經濟目標正在推動市場需求的穩定成長。 SKF的「Infinium」軸承(採用雷射金屬沉積技術,可無限次重複使用)展示了歐洲供應商如何將監測解決方案與資源效率結合。在南美、中東和非洲等新興地區,監測技術正被應用於採礦和公共產業專案中,以提高在嚴苛運作條件下的運作,從而推動全球馬達監測市場的擴張。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大預測性維護平台的應用
- 快速過渡到無線、無電池感測器網路
- 工業物聯網與數位孿生架構的整合
- 加強全球汽車能源效率法規
- 整合到感測器中的邊緣人工智慧診斷晶片
- 對離岸風力發電機傳動系統持續監測的需求
- 市場限制因素
- 高額的初始資本支出(CAPEX)和投資報酬率的不確定性
- 具備該領域專業知識的可靠性工程師短缺
- 基於雲端的監控中的網路安全風險
- 涉及多個供應商的工廠之間的資料所有權/互通性糾紛
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 報價
- 硬體
- 軟體
- 服務
- 不同的發展
- 現場
- 雲
- 透過監測方法
- 振動分析
- 馬達電流特徵
- 熱成像
- 石油分析
- 超音波和聲學
- 依馬達類型
- 交流馬達
- DC馬達
- 伺服馬達和步進電機
- 按最終用戶行業分類
- 石油和天然氣
- 能源與電力
- 車
- 採礦和金屬
- 食品/飲料
- 化學品
- 航太/國防
- 其他行業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- GCC
- 土耳其
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB Ltd.
- Siemens AG
- General Electric Co.
- Emerson Electric Co.
- Honeywell International Inc.
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corp.
- National Instruments Corp.
- Banner Engineering Corp.
- SKF Group(Baker Instrument Co.)
- Fluke Corp.
- Iris Power LP
- Dynapar Corp.
- Koncar Electrical Engineering Institute Inc.
- Baker Hughes Co.
- Artesis AS
- Analog Devices Inc.
- Teledyne FLIR LLC
- WEG SA
第7章 市場機會與未來展望
According to Mordor Intelligence, the motor monitoring market size is expected to grow from USD 2.45 billion in 2025 to USD 2.62 billion in 2026 and is forecast to reach USD 3.64 billion by 2031 at 6.82% CAGR over 2026-2031.
This report is Segmented by Offering (Hardware, Software, and More), Deployment, Monitoring Technique (Vibration Analysis, Motor Current Signature, and More), End-User Industry (Oil and Gas, Energy and Power, and More), Motor Type (AC Motors, DC Motors, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Motor Monitoring Market Trends and Insights
Rising Adoption of Predictive Maintenance Platforms
Predictive maintenance platforms now combine vibration, current, acoustic and thermal data with machine-learning models that deliver 91% anomaly detection accuracy and cut breakdowns by 30-50%. Steel makers have demonstrated 40-hour failure forecasts, and mining operators report nine-fold returns from averting unplanned stoppages. The economic case continues to sharpen as cloud analytics turn raw sensor feeds into prescriptive work orders that reduce spare-parts inventories and overtime labour.
Rapid Shift Toward Wireless, Battery-less Sensor Networks
Energy-harvesting designs that draw micro-watts from motor magnetic fields eliminate battery swaps and wiring, slashing lifetime ownership costs. Commercial modules such as TDK's i3 integrate on-board edge-AI to extend operating life by 50% while forming self-healing mesh networks over industrial campuses. These untethered nodes unlock monitoring in ship engine rooms and offshore rigs where access is costly and hazardous.
High Upfront CAPEX and ROI Uncertainty
Full-scale deployments often require USD 100,000 or more for sensors, gateways and integration, a burden that can deter mid-sized plants despite potential 10-40% maintenance savings. Case studies show early models may drift when equipment is modified, necessitating extra spend on algorithm retraining, which prolongs payback horizons. Vendors are responding with subscription-based offerings and staged pilots to mitigate financial risk for cost-sensitive buyers.
Other drivers and restraints analyzed in the detailed report include:
- Integration of IIoT and Digital Twin Architectures
- Stricter Global Motor-Efficiency Regulations
- Shortage of Domain-Skilled Reliability Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated a 9.34% CAGR outlook as companies turn to external specialists for integration, analytics and lifecycle optimization. While hardware retained 68.45% of 2025 revenue, complex multivendor environments now prioritize data interpretation over sensor procurement. Emerson's USD 8.2 billion purchase of NI underscores the pivot toward higher-margin service revenue streams that embed continuous monitoring into broader automation contracts.
Hardware makers are repositioning as solution providers by bundling gateways, cloud connectors and managed dashboards. Regal Rexnord's Perceptiv platform integrates field sensors with analytics that reportedly cut expected failures by 55% and stretch machine life 40%. As value migrates to insights rather than components, hybrid commercial models encompassing equipment, software and support are becoming the norm across the motor monitoring market.
On-premises architectures kept 73.10% revenue share in 2025 because critical plants still favour local control for latency and data-sovereignty reasons. Nevertheless, cloud deployments hold the fastest 11.75% CAGR as cybersecurity standards mature and 5G networks lower backhaul costs. Honeywell's collaboration with Verizon embeds cellular intelligence in meters to stream usage data securely to analytics hubs, showcasing the hybrid edge-cloud approach gaining traction.
Academic research flags four common vulnerabilities in cloud-SCADA links-shared resources, insider threats, insecure protocols and connectivity gaps-yet the adoption of zero-trust architectures and network-based intrusion detection is mitigating risk. Manufacturers increasingly process safety-critical data locally while offloading deep-learning workloads and fleet benchmarking to the cloud, a pattern that boosts scalability without compromising uptime across the motor monitoring market.
Complete Report Scope:
- By Offering
- Hardware
- Software
- Services
- By Deployment
- On-Premise
- Cloud
- By Monitoring Technique
- Vibration Analysis
- Motor Current Signature
- Thermography
- Oil Analysis
- Ultrasound and Acoustic
- By Motor Type
- AC Motors
- DC Motors
- Servo and Stepper Motors
- By End-User Industry
- Oil and Gas
- Energy and Power
- Automotive
- Mining and Metals
- Food and Beverage
- Chemicals
- Aerospace and Defense
- Other Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific holds the strongest growth outlook at a 9.98% CAGR through 2031. Government policies such as China's Smart Manufacturing 2025 blueprint are incentivizing sensor retrofits, and domestic vendors are releasing cost-competitive platforms to capture local demand. New product lines under Siemens' "China Acceleration 2.0" and Mitsubishi Electric's "Lingling" brand exemplify tailored strategies for this market, reinforcing momentum within the motor monitoring market. North America remains the revenue leader with 34.70% share in 2025 due to strict energy-efficiency rules and investments in grid and data-center resiliency. Schneider Electric's USD 700 million expansion across five U.S. plants illustrates how suppliers are localizing production to support federal infrastructure programs that prioritize condition-based maintenance in energy, water and manufacturing sectors. Europe shows steady demand fuelled by sustainability mandates and circular-economy goals. SKF's Infinium bearings-capable of indefinite reuse through laser metal deposition-demonstrate how European suppliers align monitoring solutions with resource efficiency. Emerging regions in South America and Middle East and Africa are adopting monitoring technologies in mining and utility projects to enhance uptime amid harsh operating conditions, extending the global reach of the motor monitoring market.
- ABB Ltd.
- Siemens AG
- General Electric Co.
- Emerson Electric Co.
- Honeywell International Inc.
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corp.
- National Instruments Corp.
- Banner Engineering Corp.
- SKF Group (Baker Instrument Co.)
- Fluke Corp.
- Iris Power LP
- Dynapar Corp.
- Koncar Electrical Engineering Institute Inc.にし
- Baker Hughes Co.
- Artesis A.S.
- Analog Devices Inc.
- Teledyne FLIR LLC
- WEG S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising adoption of predictive maintenance platforms
- 4.2.2 Rapid shift toward wireless, battery-less sensor networks
- 4.2.3 Integration of IIoT and digital twin architectures
- 4.2.4 Stricter global motor-efficiency regulations
- 4.2.5 Edge-AI embedded diagnostic chips in sensors
- 4.2.6 Offshore wind turbines demand for continuous drivetrain surveillance
- 4.3 Market Restraints
- 4.3.1 High upfront CAPEX and ROI uncertainty
- 4.3.2 Shortage of domain-skilled reliability engineers
- 4.3.3 Cyber-security risk in cloud-based monitoring
- 4.3.4 Data-ownership / interoperability disputes across multi-vendor plants
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Deployment
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By Monitoring Technique
- 5.3.1 Vibration Analysis
- 5.3.2 Motor Current Signature
- 5.3.3 Thermography
- 5.3.4 Oil Analysis
- 5.3.5 Ultrasound and Acoustic
- 5.4 By Motor Type
- 5.4.1 AC Motors
- 5.4.2 DC Motors
- 5.4.3 Servo and Stepper Motors
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Energy and Power
- 5.5.3 Automotive
- 5.5.4 Mining and Metals
- 5.5.5 Food and Beverage
- 5.5.6 Chemicals
- 5.5.7 Aerospace and Defense
- 5.5.8 Other Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 GCC
- 5.6.5.2 Turkey
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 General Electric Co.
- 6.4.4 Emerson Electric Co.
- 6.4.5 Honeywell International Inc.
- 6.4.6 Schneider Electric SE
- 6.4.7 Rockwell Automation Inc.
- 6.4.8 Mitsubishi Electric Corp.
- 6.4.9 National Instruments Corp.
- 6.4.10 Banner Engineering Corp.
- 6.4.11 SKF Group (Baker Instrument Co.)
- 6.4.12 Fluke Corp.
- 6.4.13 Iris Power LP
- 6.4.14 Dynapar Corp.
- 6.4.15 Koncar Electrical Engineering Institute Inc.にし
- 6.4.16 Baker Hughes Co.
- 6.4.17 Artesis A.S.
- 6.4.18 Analog Devices Inc.
- 6.4.19 Teledyne FLIR LLC
- 6.4.20 WEG S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 馬達監控市場:2026-2032年全球市場預測(依產品、技術、馬達類型、部署方式及最終用途分類)
 2026-2030年全球無線電機監控系統市場
 馬達監控市場:按組件、技術和地區分類
 馬達監控市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶及功能分類
 馬達監控市場規模、佔有率及成長分析(按類型、技術、最終用戶產業、部署類型和地區分類)-2026-2033年產業預測
 2025 年至 2033 年汽車監控市場報告(按產品、監控流程、最終用途和地區)
 馬達監控市場-全球產業規模、佔有率、趨勢、機會及預測(依產品、監控流程、最終用途產業、地區及競爭細分,2020-2030 年預測)
 全球馬達監控市場規模(按產品、部署、地區、範圍和預測)
 全球馬達監控市場:市場規模、佔有率、趨勢分析(按產品、流程、部署方法、最終用途和地區)、細分市場預測(2025 年至 2030 年)