


 |
市場調查報告書
商品編碼
2124724
生物識別卡:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Biometric Card - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年生物識別卡市值為 10.1 億美元,預計到 2031 年將達到 170.9 億美元,而 2026 年為 16.2 億美元,預測期(2026-2031 年)複合年成長率為 60.2%。
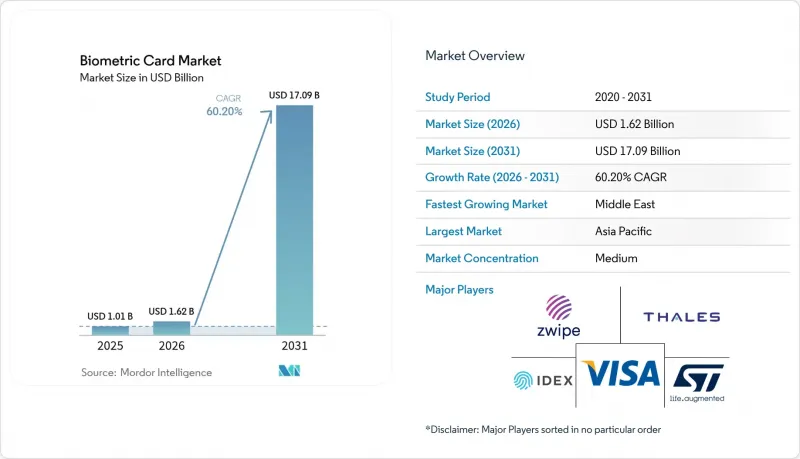
本報告按卡片類型(信用卡、簽帳金融卡、混合/雙介面卡)、應用領域(支付、門禁、政府頒發的識別卡、普惠金融等)、終端用戶行業(銀行、金融服務和保險、零售、政府、醫療保健和商業機構)以及地區(北美、歐洲等)進行細分。市場預測以美元計價。
全球生物識別卡市場趨勢及洞察
非接觸式支付的普及
疫情期間,非接觸式支付從單純的便利功能發展成為一種備受青睞的標準支付方式,其地位已穩固確立。生物識別卡消除了傳統非接觸式支付(需要輸入密碼)的交易限額,同時保持了接觸式支付的速度,並恢復了部分已失效的防詐欺措施。日本的Life Card專案表明,消費者迅速接受了使用指紋認證支付高價餐飲和交通費用。支付網路正在推廣生物識別,以維持實體卡在其基於電子錢包的生態系統中的地位。零售商也因此受益,排隊時間縮短,扣回爭議帳款風險降低,進一步增強了商家對生物識別卡市場的支持。
降低生物識別感測器和安全元件的成本。
大規模生產已將指紋感應器的成本降至 5 美元以下,降低了組件成本,使發卡機構能夠大規模生產無需年費的生物識別卡。英飛凌的 Secora Pay Bio 和指紋卡單晶片結構無需冗餘的微控制器,從而降低了功耗並簡化了層壓製程。多層結構良率的提高使缺陷率從 20% 以上降低,為契約製造製造商開闢了新的收入來源。鑑於以往矽成本隨產能翻倍而下降 15-20% 的趨勢,生物識別卡市場目前正享受著半導體產業獨有的成本曲線,這種曲線先前僅限於行動電話。
生產成本高,成品率低
在這種結構複雜的卡片中,指紋感應器、安全元件、天線和電池被整合在一個僅0.8毫米外形規格中。層壓過程中的錯位和縫隙會導致整批卡片無法使用,最終導致其良率低於傳統的非接觸感應卡。指紋卡公司累計,2024年其銷售額為4.032億瑞典克朗(約3,850萬美元),但由於瑕疵產品增多導致出貨量受限,銷售額大幅下降。 Zwipe公司於2025年3月破產,凸顯了當生產擴張與根深蒂固的缺陷發生衝突時所帶來的融資壓力。在自動化和線上光學檢測技術成熟之前,製造業的經濟效益將限制供應成長,並減緩生物識別卡市場的成長。
細分市場分析
到2025年,簽帳金融卡將佔銷售額的51.62%。這反映了日常交易的高頻率以及欺詐責任向發卡機構的轉移,而發卡機構更傾向於採用生物識別。使用者接受指紋認證是因為它既能保護他們的支票帳戶餘額,又能免去輸入PIN碼的麻煩。信用卡的發展速度落後於簽帳金融卡,但離線生物識別帶來的安全感也讓信用卡受益,尤其是在昂貴的國際旅行中。混合雙介面格式目前的複合年成長率高達62.1%,其成長速度超過了生物識別卡市場的整體規模,因為發卡機構傾向於選擇支援接觸式和非接觸式讀卡模式的單一SKU。 Kona獲得PVC和金屬卡的認證,凸顯了其向高階市場的擴張,該市場可以收取更高的交易手續費。
此外,複合卡在所有場景下均採用相同的指紋認證流程,包括超級市場收銀台、公共交通閘機和餐廳EMV讀卡器,有助於提高庫存管理效率,並為消費者提供更清晰的說明。金屬基板更能吸引追求外觀差異化的高階消費者,但其較厚的外殼需要可靠的感測器校準。隨著產量增加,複合卡的盈利增大,單價溢價降低,使其能夠應用於更廣泛的產品線,而不僅限於白金級產品。這種良性循環使混合卡在生物識別卡市場佔據了核心競爭地位。
區域分析
預計到2025年,亞太地區將佔全球銷售額的38.10%,這得歸功於日本Life Card和中國數位付款基礎的早期應用先例。在地化生產帶來的成本降低,加上監管機構生物識別對老年人和不熟悉智慧型手機的農村居民具有普惠性,以及國內晶片製造能力的提升,意味著區域供應商如今已能與歐洲老牌企業在國際競標中展開直接競爭。
北美也緊隨其後,這主要是由於發卡機構面臨交易手續費下降和不當扣回爭議帳款的風險。金融品牌正在試行採用金屬基板的指紋卡,以吸引富裕的旅行者,而區域銀行則將這項技術視為在金融科技公司競爭中客戶維繫的優勢。儘管北美在強大的客戶身份驗證方面的監管力度不如歐洲,但消費者對無縫安全性的期望正在推動市場發展。
中東地區以66.4%的複合年成長率領先全球,這主要得益於沙烏地阿拉伯「2030願景」和阿拉伯聯合大公國「智慧城市」計畫對數位身分和無現金社會計畫的資金投入。政府訂單正在加速認證流程,Visa向IDEX Biometrics訂購1萬套設備是最好的例證。非洲透過整合支付和國民身分功能的泛非金融普惠計畫展現出成長勢頭,但電力供應不穩定和POS終端普及率低限制了短期銷售量的成長。歐洲持續受惠於PSD2法規,但市場成熟度使其相對於新興地區的成長速度有所放緩。儘管如此,非接觸式支付的日益普及仍然保持著對生物識別卡的基本需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 非接觸式支付正變得越來越普及。
- 降低生物識別感測器和安全元件的成本。
- 監管機構為加強客戶身份驗證所做的努力
- 新興市場的金融普惠計劃
- 銀行的目標是追回被OEM錢包竊取的交換費。
- 具備生物識別功能的冷錢包型加密貨幣記憶卡的需求
- 市場限制因素
- 生產成本高,成品率低
- 透過智慧型手機內建的生物識別技術競爭
- 缺乏標準化的遠端註冊流程
- 對多層卡片材料永續性的擔憂
- 產業生態系分析
- 監理情勢
- 技術展望
- 宏觀經濟因素的影響
- 波特五力分析
- 生物識別卡的演變
第5章 市場規模與成長預測
- 按卡片類型
- 信用卡
- 簽帳金融卡
- 混合/雙介面卡
- 透過使用
- 沉澱
- 存取控制
- 政府核發的身份證和普惠金融
- 其他
- 按最終用戶行業分類
- 銀行業、金融服務業及保險業
- 零售
- 政府
- 醫療保健
- 商業組織
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 肯亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Thales SA
- IDEMIA Group SARL
- IDEX Biometrics ASA
- Zwipe AS
- Fingerprint Cards AB
- STMicroelectronics NV
- Infineon Technologies AG
- NXP Semiconductors NV
- Giesecke+Devrient GmbH
- Visa Inc.
- Mastercard Incorporated
- Samsung Electronics Co., Ltd.(System LSI Business)
- Goldpac FinTech Holding Limited
- Watchdata Technologies Pte Ltd
- CPI Card Group Inc.
- Seshaasai Business Forms(P)Ltd
- Smartmatic International Holding BV
- NEC Corporation
- HID Global Corporation
- Linxens Holding SAS
第7章 市場機會與未來展望
According to Mordor Intelligence, the biometric card market size was valued at USD 1.01 billion in 2025 and estimated to grow from USD 1.62 billion in 2026 to reach USD 17.09 billion by 2031, at a CAGR of 60.2% during the forecast period (2026-2031).
This report is Segmented by Card Type (Credit Card, Debit Card, and Hybrid/Dual-interface Card), Application (Payments, Access Control, Government ID and Financial Inclusion, and More), End-User Vertical (Banking Financial Services and Insurance, Retail, Government, Healthcare, and Commercial Entities), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Biometric Card Market Trends and Insights
Rising Adoption of Contactless Payments
Contactless usage shifted from convenience feature to preferred default during the pandemic and remains entrenched. Biometric cards remove the contactless value limit that otherwise triggers PIN entry, preserving tap-and-go speed while restoring lost fraud controls. Japan's Life Card program showed consumers quickly accept fingerprint verification for higher-ticket meals and transit fares. Payment networks now promote biometric authentication to keep the physical card relevant amid wallet-based ecosystems. Retailers benefit from shorter queues and lower chargeback risk, reinforcing merchant support for the biometric card market.
Declining Biometric Sensor and Secure-Element Costs
Volume production pushed fingerprint-sensor prices under USD 5, trimming bill-of-materials costs to the point where issuers can mass-issue biometric cards without annual fees. Infineon's Secora Pay Bio and Fingerprint Cards' single-chip architecture eliminated duplicate microcontrollers, shaving power budgets and simplifying lamination steps. Yield improvements in multi-layer construction reduced scrap rates that once exceeded 20%, unlocking new profit pools for contract manufacturers. As each capacity doubling historically cuts silicon cost 15-20%, the biometric card market now enjoys semiconductor-style cost curves formerly limited to mobile handsets.
High Production Cost and Low Manufacturing Yield
Complex card stacks pair fingerprint sensors, secure elements, antennas, and batteries into a 0.8 mm form factor. Misalignment or lamination voids render entire batches unusable, keeping yields below conventional contactless cards. Fingerprint Cards posted SEK 403.2 million (USD 38.5 million) revenue in 2024, down sharply as rising scrap curtailed volumes. Zwipe's March 2025 bankruptcy underscores the capital strain when production ramp-ups collide with persistent defects. Until automation and inline optical inspection mature, manufacturing economics will cap supply growth and temper the biometric card market.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Strong Customer Authentication
- Banks Aiming to Reclaim Interchange Lost to OEM Wallets
- Competition from Smartphone Biometrics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Debit cards generated 51.62% of revenue in 2025, reflecting everyday payment frequency and fraud-liability shifts toward issuers that favor biometric authentication. Users accept fingerprint verification because it removes PIN-entry friction while guarding checking-account balances. Credit cards trail but benefit from high-ticket international travel where offline biometric verification offers peace of mind. The hybrid dual-interface format now enjoys a 62.1% CAGR, outpacing the overall biometric card market size as issuers choose a single SKU that works in contact and contactless reader modes. Kona's PVC and metal approvals highlight extension into premium tiers carrying higher interchange.
Hybrid cards also streamline inventory and simplify consumer education because the fingerprint ritual stays identical at supermarket terminals, transit gates, or restaurant EMV readers. Metal substrates further appeal to affluent segments seeking tangible differentiation yet demand reliable sensor calibration to handle thicker housings. As volume scales, hybrid yields improve, reducing unit premiums and expanding availability beyond platinum-tier offerings. This feedback loop places hybrid formats at the competitive core of the biometric card market.
Complete Report Scope:
- By Card Type
- Credit Cards
- Debit Cards
- Hybrid / Dual-interface Cards
- By Application
- Payments
- Access Control
- Government ID and Financial Inclusion
- Other Applications
- By End-User Vertical
- Banking, Financial Services and Insurance
- Retail
- Government
- Healthcare
- Commercial Entities
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
Asia Pacific accounted for 38.10% of 2025 global revenue as Japan's Life Card and China's digital-payments backbone set early adoption precedents. Local manufacturing kept costs low, and regulators framed biometrics as an inclusion tool for seniors or rural citizens less comfortable with smartphones. Rising domestic chip capabilities mean regional suppliers now compete head-to-head with European incumbents for international tenders.
North America follows, propelled by issuers facing interchange erosion and stray-chargeback exposure. Financial brands trial fingerprint cards with metal substrates to court affluent travelers, while regional banks view the technology as a retention perk amid fintech competition. Regulatory clarity around strong-customer authentication remains less prescriptive than Europe, but consumer expectation for seamless security provides market momentum.
The Middle East heads growth tables with a 66.4% CAGR as Saudi Vision 2030 and UAE smart-city blueprints funnel funds into digital-ID and cashless-society programs. Government procurement accelerates certification cycles, evidenced by IDEX Biometrics' 10,000-unit Visa order. Africa shows nascent traction through Pan-African financial-inclusion drives that blend payment capability with national-ID features, though unreliable power and POS coverage restrain near-term volume. Europe continues to benefit from PSD2 mandates, but market maturation tempers its relative pace compared with emerging regions, even as contactless ubiquity keeps baseline demand strong in the biometric card market.
- Thales SA
- IDEMIA Group SARL
- IDEX Biometrics ASA
- Zwipe AS
- Fingerprint Cards AB
- STMicroelectronics N.V.
- Infineon Technologies AG
- NXP Semiconductors N.V.
- Giesecke+Devrient GmbH
- Visa Inc.
- Mastercard Incorporated
- Samsung Electronics Co., Ltd. (System LSI Business)
- Goldpac FinTech Holding Limited
- Watchdata Technologies Pte Ltd
- CPI Card Group Inc.
- Seshaasai Business Forms (P) Ltd
- Smartmatic International Holding B.V.
- NEC Corporation
- HID Global Corporation
- Linxens Holding SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising adoption of contactless payments
- 4.2.2 Declining biometric sensor and secure-element costs
- 4.2.3 Regulatory push for strong customer authentication
- 4.2.4 Financial-inclusion programmes in emerging economies
- 4.2.5 Banks aiming to reclaim interchange lost to OEM wallets
- 4.2.6 Demand for biometric cold-wallet crypto storage cards
- 4.3 Market Restraints
- 4.3.1 High production cost and low manufacturing yield
- 4.3.2 Competition from smartphone biometrics
- 4.3.3 Lack of standardised remote-enrolment processes
- 4.3.4 Sustainability concerns over multi-layer card materials
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Evolution of Biometric Cards
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Card Type
- 5.1.1 Credit Cards
- 5.1.2 Debit Cards
- 5.1.3 Hybrid / Dual-interface Cards
- 5.2 By Application
- 5.2.1 Payments
- 5.2.2 Access Control
- 5.2.3 Government ID and Financial Inclusion
- 5.2.4 Other Applications
- 5.3 By End-User Vertical
- 5.3.1 Banking, Financial Services and Insurance
- 5.3.2 Retail
- 5.3.3 Government
- 5.3.4 Healthcare
- 5.3.5 Commercial Entities
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia and New Zealand
- 5.4.4.6 Rest of Asia Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Kenya
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, market level overview, core segments, financials as available, strategic information, market rank/share for key companies, products and services, and recent developments)
- 6.4.1 Thales SA
- 6.4.2 IDEMIA Group SARL
- 6.4.3 IDEX Biometrics ASA
- 6.4.4 Zwipe AS
- 6.4.5 Fingerprint Cards AB
- 6.4.6 STMicroelectronics N.V.
- 6.4.7 Infineon Technologies AG
- 6.4.8 NXP Semiconductors N.V.
- 6.4.9 Giesecke+Devrient GmbH
- 6.4.10 Visa Inc.
- 6.4.11 Mastercard Incorporated
- 6.4.12 Samsung Electronics Co., Ltd. (System LSI Business)
- 6.4.13 Goldpac FinTech Holding Limited
- 6.4.14 Watchdata Technologies Pte Ltd
- 6.4.15 CPI Card Group Inc.
- 6.4.16 Seshaasai Business Forms (P) Ltd
- 6.4.17 Smartmatic International Holding B.V.
- 6.4.18 NEC Corporation
- 6.4.19 HID Global Corporation
- 6.4.20 Linxens Holding SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 全球步態辨識市場(2026-2030 年)
 全球生物識別卡市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 生物識別:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)軍事生物識別:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026年全球軍事生物辨識市場報告下一代生物識別:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 生物識別系統市場-2026-2032年全球市場預測生物識別和身分管理市場:2026-2032年全球市場預測(按技術類型、組件、認證方法、應用、最終用戶和部署模式分類)消費性電子生物識別市場:2026-2032年全球市場預測(依產品、模式、技術、設備類型、接觸方式、外形規格、應用及銷售管道)生物識別市場:按組件、技術類型、交付方式、認證方式、行動性和最終用戶產業分類-2026-2032年全球市場預測