


 |
市場調查報告書
商品編碼
2124473
5G設備:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)5G Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
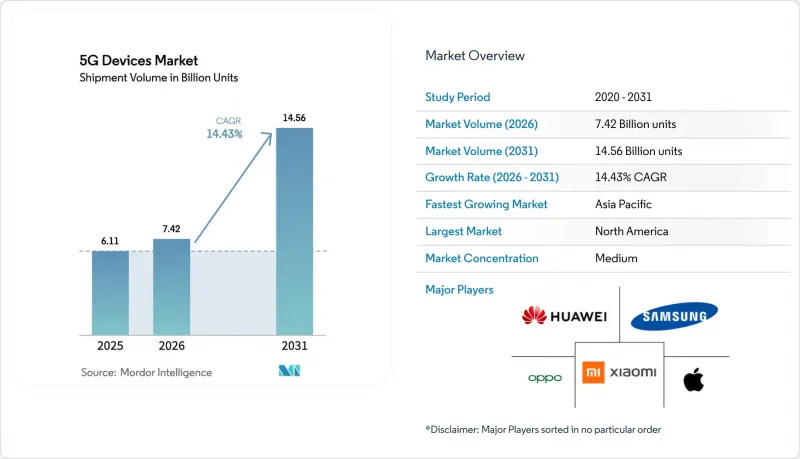
根據 Mordor Intelligence 的數據,基於出貨量,5G 設備市場規模預計將從 2025 年的 61.1 億台成長到 2026 年的 74.2 億台,然後從 2026 年到 2031 年以 14.43% 的複合年成長率成長,達到 2031 年。
本報告外形規格(智慧型手機、CPE、工業路由器、模組、筆記型電腦/平板電腦、熱點、穿戴式裝置/XR)、頻譜支援(6GHz以下、毫米波、混合頻段)、最終用戶(消費、工業、汽車、醫療、能源、企業)、應用(eMBB、URLLC、MMTC、FWA、V2X)和地區進行細分。市場預測以銷售量(單位)為單位。
全球5G設備市場趨勢與洞察
新興經濟體行動數據需求爆炸性成長
預計到2025年,印度用戶每月數據消耗量將超過20GB。這主要得益於雲端遊戲、擴增實境(AR)濾鏡以及延遲要求低於100毫秒的即時翻譯工具。儘管全球5G覆蓋率已達55%,但在低收入國家,5G普及率僅4%,價格因素比基礎建設更為重要。為了應對這個問題,營運商推出了分期付款計劃以降低設備的初始成本,製造商也開始推出售價低於150美元、功能較少的智慧型手機。雖然這擠壓了利潤空間,但5G設備市場已不再局限於早期用戶群。因此,銷量有所成長,為出貨量實現兩位數成長奠定了基礎。
5G晶片組和射頻前端的平均售價(ASP)正在下降。
2024會計年度,高通驍龍4系列處理器的平均售價年減22%。這主要歸功於聯發科降低了其天璣6000處理器的價格。用於Sub-6GHz頻段的GaAs功率放大器價格從2022年的每片3.5美元降至2025年的不到2美元。因此,5G組件相對於4G的成本溢價降至15美元以下,消除了大眾市場普及的最大障礙。毫米波前端模組的成本仍在12至18美元之間,因此該頻寬目前仍僅限於高階機型。儘管如此,核心半導體價格的下降使得入門級機型即使在新興市場也更加經濟實惠,從而擴大了5G設備市場。
射頻半導體供應鏈的波動
由於氮化鎵晶圓供不應求,2024 年射頻前端元件的前置作業時間前置作業時間已延長至 30 週,而基頻半導體裝置的交貨週期僅為 14 週。由於全球僅有三家晶圓廠能夠大規模生產碳化矽上氮化鎵 (GaN-on-SiC)基板,高階毫米波 (mmWave) 設備往往難以準時商店。為了降低這種風險,原始設備製造商 (OEM) 正在推出兩種類型的 SKU:一種是 6 吉赫以下的量產型號,另一種是限量生產的毫米波型號。這種產品兩極化將減緩 5G 設備市場的整體複合年成長率 (CAGR),直到新的晶圓廠產能投入運作。
細分市場分析
預計到2025年,智慧型手機將佔總出貨量的64.96%,凸顯其作為全球超過45億用戶主要存取設備的核心地位。然而,預計到2025年,智慧型手機的更換週期將達到31個月,顯示市場已趨於成熟。穿戴式裝置和擴增實境(XR)硬體預計將在2031年之前以15.52%的複合年成長率成長,這主要得益於保險公司的健康促進獎勵和職場安全法規的推動。據蘋果公司稱,2024年,支援蜂窩網路的Apple Watch佔該公司穿戴式產品組合的38%,高於2022年的22%。由於農村寬頻發展,固定無線網路的用戶端設備(CPE)需求正在成長,而價格在500美元至1200美元之間的工業路由器在惡劣環境下的部署需求也在增加。隨著物聯網 (IoT) 的發展,汽車與測量儀器之間 M2M (機器對機器) 通訊所必需的模組的規模也在不斷擴大。
探究成長的主導力所在,便可發現為何以口袋為中心的設備需求趨於平穩,而穿戴式和環境終端設備的需求卻在激增。擴增實境(AR)眼鏡透過將操作說明疊加到工人的視野中,減少了工廠的維護錯誤。然而,電池續航力問題依然存在,因為使用者期望腕戴式和眼鏡產品設備能夠持續使用數天。因此,持續推進半導體技術的發展,將功耗控制在300毫瓦以下,仍將是外形規格轉變的關鍵因素。隨著這些技術的進步,5G設備市場將逐漸擺脫對行動電話的依賴,並有望達到70億台的規模。
預計到2025年,6GHz以下吉赫的無線設備將佔據58.22%的市場。這主要得益於其能夠在公里級範圍內實現300-600兆位元/秒的通訊速度,且前端成本低於6美元。毫米波(mmWave)設備的出貨量雖然成長了14.86%,但由於模組單價較高(12-18美元)以及對更高網路密度的持續需求,這一成長基數較低。預計到2025年,結合兩種頻寬的混合設備將佔智慧型手機市場佔有率的18%,滿足早期用戶對最高速度的需求。為了達到與6GHz以下頻段相當的訊號覆蓋範圍,營運商需要安裝的毫米波小型基地台是吉赫以下頻段基地台的10-15倍,如此龐大的資本投入負擔正在延緩全面覆蓋的實現。
就全國普及率而言,預計6GHz以下吉赫將佔據主導地位,而毫米波可能僅限於體育場館、機場和人口密集的城市走廊。因此,6GHz以下吉赫的硬體將繼續大量供應,成為5G設備市場的主力軍,而毫米波將瞄準高階市場。如果設備普及率提高且前端價格下降,到2031年毫米波的市場佔有率可能接近30%,但其成長潛力取決於基礎設施和組件供應方面的瓶頸能否得到解決。
區域分析
到2025年,亞太地區將佔全球5G設備出貨量的55.73%。這主要得益於中國4.2億台的產量以及印度與生產連結獎勵計畫計劃,該計劃已吸引了150億美元的組裝投資。日本和韓國將佔1,000美元以上高階市場的40%,其實際市佔率遠超過其出貨量排名所顯示的水準。東南亞市場正在快速擴張,主要由300美元以下的設備推動,而澳洲和紐西蘭的成長則受到36個月週期的限制。憑藉其本土化的零件生態系統,亞太地區與歐洲和北美相比擁有高達30%的成本優勢,鞏固了主導地位。
中東是成長最快的地區之一,預計到2031年將維持16.01%的複合年成長率。沙烏地阿拉伯已在其「2030願景」下撥款200億美元用於5G智慧城市項目,而阿拉伯聯合大公國預計到2024年將實現95%的人口5G覆蓋範圍。由於平均售價持續高企,設備普及速度落後於網路部署,但晶片組成本的持續下降將為下一階段的普及鋪平道路。
北美和歐洲面臨相互矛盾的因素。雖然5G部署日趨成熟,但監管壓力正在減緩設備的更換。歐盟於2023年收緊了電子廢棄物法規,對每台設備徵收2至5美元的處置費。在美國,圍繞「維修權」的爭論促使用戶延長設備的使用壽命,使得全部區域複合年成長率保持在較低的兩位數百分比。南美洲和非洲合計佔全球出貨量的12%,但在服務不足的農村地區,固定無線網路將在中期內成為實現顯著成長的途徑。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新興市場行動數據需求爆炸性成長
- 5G晶片組和射頻前端的平均售價(ASP)正在下降。
- 電信業者主動推出終端補貼計劃
- 為企業實施專用網路
- 促進工業設備普及的監管頻率共用模式(CBRS、英國LSA)
- 一款多接入邊緣AI晶片,可實現超低功耗5G穿戴式裝置。
- 市場限制因素
- 射頻半導體供應鏈的波動
- 在人口稠密的城市地區以外,毫米波通訊覆蓋範圍不均勻。
- 限制行動電話快速更換的電子廢棄物法規。
- 跨境安全認證正在減緩工業路由器的部署。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按外形規格
- 智慧型手機
- 客戶家中的設備(室內/室外)
- 工業路由器/閘道器
- 模組
- 筆記型電腦/平板電腦
- 熱點
- 穿戴式裝置和XR設備
- 頻譜支援
- 6GHz以下頻段
- 毫米波
- 混合型(6GHz 以下 + 毫米波)
- 按最終用戶行業分類
- 消費性電子產品
- 工業和製造業
- 汽車和運輸業
- 衛生保健
- 能源公用事業
- 企業/商業
- 透過使用
- eMBB
- URLLC
- mMTC
- FWA
- V2X
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- ASEAN
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Huawei Technologies Co., Ltd.
- Xiaomi Corp.
- Guangdong OPPO Mobile Telecommunications Corp., Ltd.
- Vivo Mobile Communication Co., Ltd.
- Lenovo Group Ltd.(Motorola Mobility LLC)
- Nokia Corp.
- ZTE Corp.
- Cisco Systems, Inc.
- Ericsson AB
- Qualcomm Inc.
- MediaTek Inc.
- Quectel Wireless Solutions Co., Ltd.
- Fibocom Wireless Inc.
- Sierra Wireless, Inc.(Semtech)
- Telit Cinterion Ltd.
- Keysight Technologies, Inc.
- TCL Technology Group Corp.
- Honor Device Co., Ltd.
- Realme Mobile Telecommunications(Shenzhen)Co., Ltd.
- HMD Global Oy
- OnePlus Technology(Shenzhen)Co., Ltd.
- AsusTek Computer Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the 5G devices market size in terms of shipment volume is expected to grow from 6.11 billion units in 2025 to 7.42 billion units in 2026 and is forecast to reach 14.56 billion units by 2031 at 14.43% CAGR over 2026-2031.
This report is Segmented by Form Factor (Smartphones, CPE, Industrial Routers, Modules, Laptops and Tablets, Hotspots, and Wearables and XR), Spectrum Support (Sub-6 GHz, Mmwave, and Hybrid), End-User (Consumer, Industrial, Automotive, Healthcare, Energy, and Enterprise), Application (eMBB, URLLC, MMTC, FWA, and V2X), and Geography. The Market Forecasts are Provided in Terms of Volume (Units).
Global 5G Devices Market Trends and Insights
Explosive Mobile-Data Demand in Emerging Economies
Monthly data consumption per user in India surpassed 20 gigabytes in 2025, driven by cloud gaming, augmented-reality filters, and real-time translation tools that require latency under 100 milliseconds. Although global 5G coverage reached 55%, penetration in low-income nations was only 4%, so affordability rather than infrastructure dictated adoption. Carriers responded with financing schemes that lowered upfront handset costs, prompting brands to release sub-USD 150 smartphones trimmed of high-end features. This dynamic expanded the 5G device market beyond early adopters, even as margins tightened. The result is a broadening unit base that underpins double-digit shipment growth.
Declining ASP of 5G Chipsets and RF Front-Ends
Qualcomm's Snapdragon 4-series average selling price dropped 22% year over year in fiscal 2024, mainly because MediaTek discounted Dimensity 6000 processors. GaAs power amplifiers for sub-6 gigahertz bands fell below USD 2 per unit in 2025, down from USD 3.50 in 2022. As a result, the bill-of-materials premium for 5G over 4G fell below USD 15, dismantling the largest barrier to mass-market adoption. MmWave front-end modules still cost USD 12-18, confining that band to premium devices. Even so, falling core silicon prices widen the 5G devices market by making entry-level models affordable in emerging economies.
Supply-Chain Volatility for RF Semiconductors
Gallium-nitride wafer shortages pushed RF front-end lead times to 30 weeks in 2024, compared with 14 weeks for baseband silicon. Only three fabs worldwide can mass-produce gallium-nitride-on-silicon-carbide substrates, so premium mmWave gear often reaches stores late. Original equipment manufacturers mitigate risk by shipping dual stock-keeping units: volume sub-6 gigahertz models and limited mmWave variants. The bifurcation blunts the overall 5G devices market CAGR until new fab capacity comes online.
Other drivers and restraints analyzed in the detailed report include:
- Aggressive Carrier Device-Subsidy Programs
- Enterprise Private-Network Rollouts
- Patchy mmWave Coverage Outside Dense Urban Zones
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Smartphones accounted for 64.96% of shipments in 2025, underscoring their central role as primary access devices for more than 4.5 billion users worldwide. Yet replacement intervals lengthened to 31 months in 2025, signaling maturation. Wearables and extended-reality hardware are on a 15.52% CAGR path to 2031, lifted by insurer wellness incentives and workplace safety mandates. Apple reported that cellular-enabled watches formed 38% of its wearable mix in 2024, up from 22% in 2022. Customer-premises equipment for fixed wireless has risen with rural broadband initiatives, while industrial routers priced at USD 500-1,200 thrive in harsh-environment deployments. Modules, critical for machine-to-machine automotive and metering links, scale in parallel with the Internet of Things.
Growth leadership shows why pocket-centric demand is plateauing while body-worn and ambient endpoints surge. Augmented-reality glasses lower maintenance errors in factories by overlaying instructions in workers' fields of view. However, battery anxiety persists because users expect multi-day endurance on wrist and eyewear devices. Continuous silicon advances that push power draw below 300 milliwatts therefore remain decisive for form-factor migration. As these advances materialize, the 5G devices market will rely less on handsets for its next 7 billion-unit expansion.
Sub-6 gigahertz radios captured 58.22% share in 2025 since they deliver 300-600 megabits per second across kilometer-scale cells at front-end costs below USD 6. MmWave shipments grow at 14.86% but start from a lower base because modules cost USD 12-18 and require network densification that is still underway. Hybrid devices that combine both bands represented 18% of 2025 smartphones, catering to early adopters keen on peak speeds. Carriers must install 10-15 times more mmWave small cells than sub-6 gigahertz sites to match signal reach, a heavy capital burden that delays ubiquitous coverage.
Momentum favors sub-6 gigahertz for nationwide availability, with mmWave reserved for stadiums, airports, and high-density downtown corridors. Consequently, sub-6 gigahertz hardware will stay the volume backbone of the 5G devices market while mmWave targets premium tiers. Once densities rise and front-end prices fall, the share of mmWave could approach 30% by 2031, but its upside hinges on solving both infrastructure and component supply bottlenecks.
Complete Report Scope:
- By Form Factor
- Smartphones
- Customer-Premises Equipment (Indoor / Outdoor)
- Industrial Grade Routers / Gateways
- Modules
- Laptops/Tablets
- Hotspots
- Wearables and XR Devices
- By Spectrum Support
- Sub-6 GHz
- mmWave
- Hybrid (Sub-6 GHz + mmWave)
- By End-User Industry
- Consumer Electronics
- Industrial and Manufacturing
- Automotive and Transportation
- Healthcare
- Energy and Utilities
- Enterprise/Commercial
- By Application
- Enhanced Mobile Broadband (eMBB)
- Ultra-Reliable Low-Latency Comms (URLLC)
- Massive Machine-Type Comms (mMTC)
- Fixed Wireless Access
- Vehicle-to-Everything (V2X)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific shipped 55.73% of global units in 2025, buoyed by China's 420 million-device output and India's production-linked incentive program that drew USD 15 billion in assembly investments. Japan and South Korea punch above their volume-based rank by owning 40% of the premium tier above USD 1,000. Southeast Asian markets expand rapidly on sub-USD 300 handsets, whereas Australia and New Zealand see 36-month cycles that temper growth. Localized component ecosystems give Asia-Pacific up to 30% cost advantages versus Europe and North America, locking in its leadership of the 5G devices market.
The Middle East is one of the fastest risers, with a 16.01% CAGR to 2031. Saudi Arabia allocated USD 20 billion to 5G smart-city projects under Vision 2030, and the United Arab Emirates achieved 95% population coverage in 2024. Device uptake lags network rollout because average selling prices remain high; continued chipset cost erosion will unlock the next leg of adoption.
North America and Europe face countervailing forces: mature 5G footprints coexist with regulatory pressures that slow handset churn. The European Union tightened e-waste rules in 2023, adding end-of-life fees of USD 2-5 per phone. U.S. right-to-repair debates encourage longer use, holding region-wide CAGR to low double digits. South America and Africa together account for 12% of shipments, though fixed wireless presents a mid-term leapfrog path in underserved rural areas.
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Huawei Technologies Co., Ltd.
- Xiaomi Corp.
- Guangdong OPPO Mobile Telecommunications Corp., Ltd.
- Vivo Mobile Communication Co., Ltd.
- Lenovo Group Ltd. (Motorola Mobility LLC)
- Nokia Corp.
- ZTE Corp.
- Cisco Systems, Inc.
- Ericsson AB
- Qualcomm Inc.
- MediaTek Inc.
- Quectel Wireless Solutions Co., Ltd.
- Fibocom Wireless Inc.
- Sierra Wireless, Inc. (Semtech)
- Telit Cinterion Ltd.
- Keysight Technologies, Inc.
- TCL Technology Group Corp.
- Honor Device Co., Ltd.
- Realme Mobile Telecommunications (Shenzhen) Co., Ltd.
- HMD Global Oy
- OnePlus Technology (Shenzhen) Co., Ltd.
- AsusTek Computer Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosive Mobile-Data Demand In Emerging Economies
- 4.2.2 Declining ASP of 5G Chipsets and RF Front-Ends
- 4.2.3 Aggressive Carrier Device-Subsidy Programs
- 4.2.4 Enterprise Private-Network Roll-Outs
- 4.2.5 Regulatory Spectrum-Sharing Models (CBRS, UK LSA) Catalysing Industrial Devices
- 4.2.6 Multi-Access Edge AI Chips Enabling Ultra-Low-Power 5G Wearables
- 4.3 Market Restraints
- 4.3.1 Supply-Chain Volatility For RF Semiconductors
- 4.3.2 Patchy Mmwave Coverage Outside Dense Urban Zones
- 4.3.3 E-Waste Regulations Restricting Rapid Handset Refresh
- 4.3.4 Cross-Border Security Certifications Delaying Industrial Routers
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Form Factor
- 5.1.1 Smartphones
- 5.1.2 Customer-Premises Equipment (Indoor / Outdoor)
- 5.1.3 Industrial Grade Routers / Gateways
- 5.1.4 Modules
- 5.1.5 Laptops/Tablets
- 5.1.6 Hotspots
- 5.1.7 Wearables and XR Devices
- 5.2 By Spectrum Support
- 5.2.1 Sub-6 GHz
- 5.2.2 mmWave
- 5.2.3 Hybrid (Sub-6 GHz + mmWave)
- 5.3 By End-User Industry
- 5.3.1 Consumer Electronics
- 5.3.2 Industrial and Manufacturing
- 5.3.3 Automotive and Transportation
- 5.3.4 Healthcare
- 5.3.5 Energy and Utilities
- 5.3.6 Enterprise/Commercial
- 5.4 By Application
- 5.4.1 Enhanced Mobile Broadband (eMBB)
- 5.4.2 Ultra-Reliable Low-Latency Comms (URLLC)
- 5.4.3 Massive Machine-Type Comms (mMTC)
- 5.4.4 Fixed Wireless Access
- 5.4.5 Vehicle-to-Everything (V2X)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Apple Inc.
- 6.4.2 Samsung Electronics Co., Ltd.
- 6.4.3 Huawei Technologies Co., Ltd.
- 6.4.4 Xiaomi Corp.
- 6.4.5 Guangdong OPPO Mobile Telecommunications Corp., Ltd.
- 6.4.6 Vivo Mobile Communication Co., Ltd.
- 6.4.7 Lenovo Group Ltd. (Motorola Mobility LLC)
- 6.4.8 Nokia Corp.
- 6.4.9 ZTE Corp.
- 6.4.10 Cisco Systems, Inc.
- 6.4.11 Ericsson AB
- 6.4.12 Qualcomm Inc.
- 6.4.13 MediaTek Inc.
- 6.4.14 Quectel Wireless Solutions Co., Ltd.
- 6.4.15 Fibocom Wireless Inc.
- 6.4.16 Sierra Wireless, Inc. (Semtech)
- 6.4.17 Telit Cinterion Ltd.
- 6.4.18 Keysight Technologies, Inc.
- 6.4.19 TCL Technology Group Corp.
- 6.4.20 Honor Device Co., Ltd.
- 6.4.21 Realme Mobile Telecommunications (Shenzhen) Co., Ltd.
- 6.4.22 HMD Global Oy
- 6.4.23 OnePlus Technology (Shenzhen) Co., Ltd.
- 6.4.24 AsusTek Computer Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 5G設備、智慧型手機和穿戴式裝置研究服務
 亞太地區5G設備:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)北美5G設備:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)南美洲5G設備:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)歐洲 5G 設備:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 2026-2030年全球5G設備市場
 2026年超低成本(ULC)行動電話全球市場報告5G-Advanced 行動裝置、穿戴式裝置和配件5G行動裝置、功能與技術:供應商、趨勢與預測5G行動裝置、功能與技術:供應商、趨勢與預測:市場數據概覽(2026年第二季)