

 |
市場調查報告書
商品編碼
2035160
日本智慧家庭:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Japan Smart Home - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
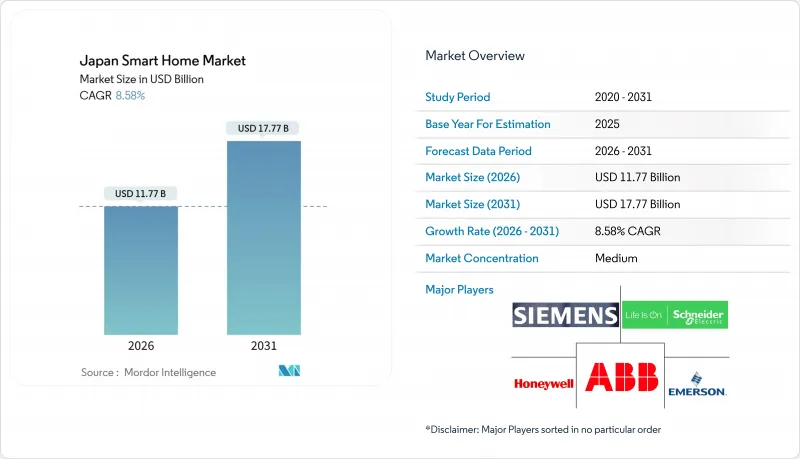
日本智慧家庭市場預計到 2026 年將達到 117.7 億美元,到 2031 年將達到 177.7 億美元,複合年成長率為 8.58%。
人口老化帶來的強大人口壓力、日益嚴格的能源效率法規以及政府對零能耗住宅的補貼,正將市場需求從單純的新奇設備轉向生活方式支持和能源管理解決方案。連網安全設備的保險折扣、Matter認證設備的普及以及通訊業者提供的配套服務,進一步降低了普及門檻。各廠商競相鎖定生態系統,消費性電子巨頭利用其值得信賴的品牌影響力,而全球平台則透過支援語音助理設備來確保持續的業務收益。基於線程的感測器正在緩解人口密集公寓大樓的Wi-Fi堵塞,而邊緣人工智慧處理則透過將資料儲存在設備本身來降低隱私擔憂。
日本智慧家庭市場的趨勢與洞察
老年人居家養老的需求推動了輔助科技的發展。
到2025年,日本65歲以上人口將達到3,620萬人。目前,地方政府正在為老年人提供補貼,用於購買運動感測器、跌倒偵測穿戴裝置和聲控照明系統,使他們能夠居家養老,無需入住養老院。Panasonic的「HomeX」平台整合了門鎖、緊急按鈕和看護者控制面板,而NEC正在試行一套人工智慧異常檢測系統,該系統會在老年人的行為偏離日常作息時通知家屬。這些解決方案在醫療設施匱乏、響應時間長的農村地區越來越受歡迎。透過通訊合約銷售硬體套裝,可以將費用分攤到24個月,這種模式正在加速這些技術的普及。由於人口結構的變化,輔助技術將在未來十年及以後繼續成為日本智慧家庭市場成長的核心驅動力。
物聯網、人工智慧和語音控制助理技術的進步
到2025年,Alexa和Google Assistant的累積安裝量將超過1500萬台,但SONY等日本公司正在將日語人工智慧整合到電視和家用電器中,以解決隱私和方言方面的擔憂。 Matter 1.3認證允許使用者在一個應用程式中控制Panasonic空調和夏普冷藏庫,消除了先前阻礙多品牌家庭使用的設備碎片化問題。三菱馬達的邊緣AI控制器無需將原始資料傳送到雲端伺服器即可最佳化空調系統,符合嚴格的資料居住要求。硬體補貼、語音辨識準確率的提高以及品牌間的互通性正在縮短更換週期,從而擴大日本智慧家庭市場的規模,覆蓋從都市區到農村的各個地區。
高昂的初始硬體和安裝成本
請專業人員安裝全套智慧家庭系統,費用可能超過80萬日圓(約5,400美元),這使得智慧家庭對於許多中等收入的消費者來說難以負擔。進口關稅、規模經濟的限制以及對高階裝修的需求,都導致設備價格高於北美。此外,大城市電工的時薪超過8,000日圓(約54美元),人事費用佔總成本的20%至30%。雖然電信業者提供捆綁套餐和訂閱模式,可以分期付款,但高昂的價格仍然是日本智慧家居市場,特別是低收入農村地區,面臨的最大障礙。
細分市場分析
預計到2031年,安防設備將帶來最大的增量收入,年複合成長率將達到10.81%,主要得益於保險公司鼓勵採用安防設備以及都市區對遠端監控的需求。然而,到2025年,智慧家庭設備將主導日本智慧家庭市場,佔27.43%的市場佔有率,這主要得益於Panasonic的生態系統,這些系統能夠與能源管理儀表板同步運作。
如今,安防產品將生物識別鎖、人工智慧攝影機和雲端儲存捆綁銷售,由此產生的業務收益足以抵消硬體價格的下跌。亞馬遜和谷歌的控制中心和音箱可以連接多個設備,而家庭娛樂領域的競爭對手則在農村地區尋求成長,因為寬頻普及正在縮小數位落差。零能耗住宅強制要求安裝能源管理設備,這迫使製造商整合先前各自獨立的產品類別,並壓縮單一功能產品線的利潤空間。
由於現有的路由器基礎設施,到 2025 年,Wi-Fi 將佔連接方式的 45.12%,但 Thread Sensors 的市佔率預計將在 2031 年前以 9.23% 的複合年成長率成長。 Thread 的低功耗網狀網路可減少人口密集的多用戶住宅的電池消耗和網路堵塞,深受推動 DIY 產品購買的年輕居住者的青睞。
藍牙技術在智慧音箱和智慧門鎖領域仍然很受歡迎,但其有限的傳輸距離難以覆蓋整個住宅。由於頻率限制和廠商支援不足,Z-Wave技術的普及速度較為緩慢。 Matter認證正在加速品牌間的兼容性,而向IPv6的過渡則為未來智慧城市部署大量設備奠定了基礎,因此,隨著日本智慧家庭市場的擴張,互通性已成為重中之重。
《日本智慧家庭市場報告》按產品類型(舒適照明、控制連接及其他)、技術(Wi-Fi、藍牙、Zigbee、Z-Wave及其他)、銷售管道(離線零售、線上零售、專業安裝商及其他)、安裝方式(DIY、專業安裝商)和住宅類型(獨棟住宅、公寓及其他)進行細分。市場預測以美元計價。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人們越來越關注家庭安全和安保問題。
- 物聯網、人工智慧和語音控制助理技術的進步
- 老年人居家養老的需求推動了輔助科技的發展。
- 政府對智慧型設備的節能補貼
- 為整合住宅資料的智慧城市示範計畫提供補貼
- 智慧家庭設備產物保險折扣
- 市場限制因素
- 高昂的初始硬體和安裝成本
- 互通性和舊有系統問題
- 資料居住法規限制海外雲端平台
- 農村地區合格安裝人員短缺
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 技術展望
- 監理情勢
- 波特五力分析
- 供應商的議價能力
- 買方的議價能力
- 新進入者的威脅
- 替代品的威脅
- 競爭公司之間的競爭
第5章 市場規模與成長預測
- 依產品類型
- 舒適度和照明
- 智慧照明(燈泡、開關、調光器)
- 智慧窗簾和百葉窗
- 控制和連接
- 智慧中心/控制器
- 智慧音箱
- 能源管理
- 智慧型恆溫器
- 智慧電錶
- 家庭娛樂
- 智慧電視
- 串流媒體設備
- 安全
- 智慧型相機
- 智慧門鈴
- 智慧鎖
- 智慧家庭設備
- 智慧冷藏庫
- 智慧型洗衣機
- 暖通空調控制
- 智慧空調
- 舒適度和照明
- 透過技術
- Wi-Fi
- Bluetooth
- Zigbee
- Z-Wave
- Thread
- 其他技術(LTE、PLC 等)
- 按銷售管道
- 實體店/消費性電子產品量販店
- 線上零售和市場
- 專業經銷商和銷售代理商通路
- 通訊業者捆綁
- 按安裝類型
- DIY(自行安裝)
- 由專業公司安裝
- 按住宅類型
- 獨立式住宅
- 公寓和住宅
- 其他住宅類型
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Schneider Electric SE
- Emerson Electric co.
- ABB Ltd
- Honeywell International Inc.
- Siemens AG
- Signify Holding
- Microsoft Corporation
- Google LLC
- Buffalo Inc.
- Hitachi Ltd.
- Zhejiang Dahua Technology Co., Ltd.
- D-Link Corporation
- Panasonic Holdings Corporation
- Sony Group Corp.
- Mitsubishi Electric Corporation
- Toshiba Corporation
- NEC Corporation
- Sharp Corporation
- Amazon.com Inc.
- Rakuten Group Inc.
第7章 市場機會與未來展望
The Japan smart home market size is USD 11.77 billion in 2026 and is projected to reach USD 17.77 billion by 2031, advancing at an 8.58% CAGR.
Strong demographic pressure from an aging population, rising energy-efficiency mandates, and government subsidies for zero-energy houses are redirecting demand from novelty devices toward assistive living and energy-management solutions. Insurance discounts for connected security equipment, the spread of Matter-certified devices, and telecom-operator bundles are further lowering adoption hurdles. Competition revolves around ecosystem lock-in, with domestic appliance majors leveraging trusted brands while global platforms subsidize voice-assistant hardware to win recurring service revenue. Thread-based sensors are mitigating Wi-Fi congestion in dense apartments, and edge AI processing is easing privacy concerns by keeping data on-device.
Japan Smart Home Market Trends and Insights
Ageing-in-Place Needs Driving Assistive Technologies
Japan's over-65 cohort reached 36.2 million in 2025, and municipalities now subsidize motion sensors, fall-detection wearables, and voice-activated lighting to let seniors remain at home rather than relocate to care facilities. Panasonic's HomeX platform integrates locks, emergency buttons, and caregiver dashboards, while NEC pilots AI anomaly detection that alerts families when routines deviate. These solutions resonate in rural prefectures where medical facilities are sparse and response times long. Uptake is accelerating as hardware bundles spread through telecom contracts that spread costs over 24 months. The demographic shift will keep assistive technology at the center of Japan smart home market growth well into the next decade.
Advances in IoT, AI, and Voice-Controlled Assistants
Cumulative Alexa and Google Assistant installations surpassed 15 million units by 2025, yet local players such as Sony embed Japanese-language AI in TVs and appliances to overcome privacy and dialect concerns. Matter 1.3 certification lets users mix Panasonic air conditioners with Sharp refrigerators under one app, reducing fragmentation that previously deterred multi-brand households. Edge AI controllers from Mitsubishi Electric optimize HVAC without sending raw data to cloud servers, aligning with strict data-residency rules. Hardware subsidies, tighter speech recognition, and cross-brand interoperability are shortening replacement cycles, and in turn enlarging the Japan smart home market base across urban and rural regions.
High Upfront Hardware and Installation Cost
A professionally installed whole-home package can top JPY 800,000 (USD 5,400), placing smart automation beyond many middle-income buyers. Import tariffs, limited economies of scale, and premium finish requirements inflate equipment prices above North American norms. Labor adds 20-30% because electricians in major cities charge more than JPY 8,000 (USD 54) per hour. Telecom bundles and subscription models spread payments over time, yet sticker shock remains the largest brake on the Japan smart home market, especially in rural districts where incomes are lower.
Other drivers and restraints analyzed in the detailed report include:
- Rising Concern About Home Security and Safety
- Government Energy-Efficiency Subsidies for Smart Devices
- Interoperability and Legacy System Issues
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Security devices will generate the highest incremental revenue, advancing at a 10.81% CAGR through 2031 as insurers incentivize adoption and urban residents seek remote monitoring. Smart appliances nonetheless dominated the Japan smart home market share at 27.43% in 2025 on the back of Panasonic, Hitachi, and Sharp ecosystems that sync with energy-management dashboards.
Security offerings now bundle biometric locks, AI cameras, and cloud storage, creating service revenue that offsets hardware price erosion. Control hubs and speakers from Amazon and Google bridge multiple devices, while home entertainment rivals seek growth in rural prefectures where broadband rollout is closing the digital divide. Energy-management devices are mandated in zero-energy houses, forcing manufacturers to integrate across formerly stand-alone categories and compressing margins in single-function product lines.
Wi-Fi accounted for 45.12% of connectivity in 2025 thanks to existing router infrastructure, yet Thread sensors are set to erode share with a 9.23% CAGR through 2031. Thread's low-power mesh reduces battery drain and network congestion in dense apartments, traits valued by younger renters who lead DIY purchases.
Bluetooth remains popular for smart speakers and locks, though range limits restrict full-home coverage. Z-Wave adoption lags due to frequency restrictions and limited vendor support. Matter certification is accelerating cross-brand compatibility, and IPv6 transition is laying groundwork for massive device counts in future smart-city deployments, keeping interoperability front and center in the Japan smart home market size expansion.
The Japan Smart Home Market Report is Segmented by Product Type (Comfort and Lighting, Control and Connectivity, and More), Technology (Wi-Fi, Bluetooth, Zigbee, Z-Wave, and More), Sales Channel (Offline Retail, Online Retail, Professional Installer, and More), Installation Type (DIY, and Professional), Dwelling Type (Detached Houses, Apartments, and More). The Market Forecasts are in Value (USD).
List of Companies Covered in this Report:
- Schneider Electric SE
- Emerson Electric co.
- ABB Ltd
- Honeywell International Inc.
- Siemens AG
- Signify Holding
- Microsoft Corporation
- Google LLC
- Buffalo Inc.
- Hitachi Ltd.
- Zhejiang Dahua Technology Co., Ltd.
- D-Link Corporation
- Panasonic Holdings Corporation
- Sony Group Corp.
- Mitsubishi Electric Corporation
- Toshiba Corporation
- NEC Corporation
- Sharp Corporation
- Amazon.com Inc.
- Rakuten Group Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Concern About Home Security and Safety
- 4.2.2 Advances in IoT, AI and Voice-Controlled Assistants
- 4.2.3 Ageing-in-Place Needs Driving Assistive Technologies
- 4.2.4 Government Energy-Efficiency Subsidies for Smart Devices
- 4.2.5 Smart-City Pilot Subsidies Integrating Residential Data
- 4.2.6 Property-Insurance Discounts for Smart-Home Devices
- 4.3 Market Restraints
- 4.3.1 High Upfront Hardware and Installation Cost
- 4.3.2 Interoperability and Legacy System Issues
- 4.3.3 Data-Residency Rules Limiting Foreign Cloud Platforms
- 4.3.4 Shortage of Certified Installers in Rural Prefectures
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Comfort and Lighting
- 5.1.1.1 Smart Lighting (Bulbs, Switches, Dimmers)
- 5.1.1.2 Smart Curtains/Blinds
- 5.1.2 Control and Connectivity
- 5.1.2.1 Smart Hubs/Controllers
- 5.1.2.2 Smart Speakers
- 5.1.3 Energy Management
- 5.1.3.1 Smart Thermostats
- 5.1.3.2 Smart Meters
- 5.1.4 Home Entertainment
- 5.1.4.1 Smart TVs
- 5.1.4.2 Streaming Devices
- 5.1.5 Security
- 5.1.5.1 Smart Cameras
- 5.1.5.2 Smart Doorbells
- 5.1.5.3 Smart Locks
- 5.1.6 Smart Appliances
- 5.1.6.1 Smart Refrigerators
- 5.1.6.2 Smart Washing Machines
- 5.1.7 HVAC Control
- 5.1.7.1 Smart Air-Conditioners
- 5.1.1 Comfort and Lighting
- 5.2 By Technology
- 5.2.1 Wi-Fi
- 5.2.2 Bluetooth
- 5.2.3 Zigbee
- 5.2.4 Z-Wave
- 5.2.5 Thread
- 5.2.6 Other Technologies (LTE, PLC, etc.)
- 5.3 By Sales Channel
- 5.3.1 Offline Retail/CE Stores
- 5.3.2 Online Retail and Marketplaces
- 5.3.3 Professional Installer/Dealer Channel
- 5.3.4 Telecom-Operator Bundles
- 5.4 By Installation Type
- 5.4.1 DIY (Self-Install)
- 5.4.2 Professional Install
- 5.5 By Dwelling Type
- 5.5.1 Detached Houses
- 5.5.2 Apartments and Condominiums
- 5.5.3 Other Dwelling Types
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Schneider Electric SE
- 6.4.2 Emerson Electric co.
- 6.4.3 ABB Ltd
- 6.4.4 Honeywell International Inc.
- 6.4.5 Siemens AG
- 6.4.6 Signify Holding
- 6.4.7 Microsoft Corporation
- 6.4.8 Google LLC
- 6.4.9 Buffalo Inc.
- 6.4.10 Hitachi Ltd.
- 6.4.11 Zhejiang Dahua Technology Co., Ltd.
- 6.4.12 D-Link Corporation
- 6.4.13 Panasonic Holdings Corporation
- 6.4.14 Sony Group Corp.
- 6.4.15 Mitsubishi Electric Corporation
- 6.4.16 Toshiba Corporation
- 6.4.17 NEC Corporation
- 6.4.18 Sharp Corporation
- 6.4.19 Amazon.com Inc.
- 6.4.20 Rakuten Group Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 智慧家庭安防:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)東協智慧家庭:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)美國智慧家庭:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2034年家庭節水技術市場預測-按安裝類型、技術類型、銷售管道、應用領域、最終用戶和地區分類的全球分析智慧家庭安裝服務:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 智慧家庭市場報告:趨勢、預測和競爭分析(至2035年)智慧家庭:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)北美智慧家庭:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 2026年全球自主防禦平台市場報告
 智慧家庭市場:2026-2032年全球市場預測(按產品、使用者介面、安裝類型、技術、應用、最終用戶和分銷管道分類)