


 |
市場調查報告書
商品編碼
2124927
全球資料外洩檢測解決方案:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Global Leak Detection Solutions - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
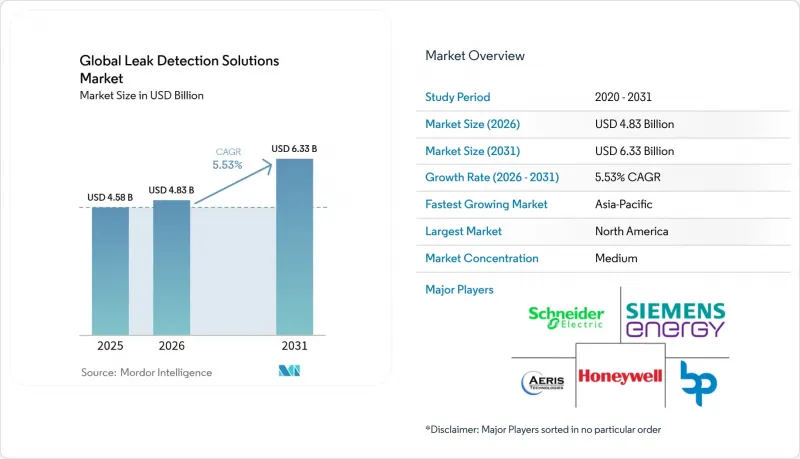
據 Mordor Intelligence 稱,2025 年洩漏檢測解決方案市值為 45.8 億美元,預計到 2031 年將達到 63.3 億美元,而 2026 年為 48.3 億美元,預測期(2026-2031 年)的複合年成長率為 5.53%。
本報告按技術(聲學/超音波、壓力分析等)、終端用戶行業(石油和天然氣、化學、水處理等)、組件(硬體、軟體、服務)、部署類型(固定/固定式、可攜式/手持式等)、管道階段(上游、中游等)和地區(北美、南美、歐洲、亞太、中東和非洲)進行分類。
全球洩漏檢測解決方案市場趨勢及洞察
嚴格的甲烷洩漏法規正在推動市場轉型。
根據《通膨控制法案》,甲烷收費將於2024年起徵收,每噸900美元,2026年將增加至1,500美元。此附加費的徵收使得持續監測的成本低於支付收費,從而重塑了計畫的經濟結構。同時,「超級發送器」協定允許第三方在洩漏量超過每小時100公斤時要求營運商做出回應,這加速了固定感測器和衛星資料饋送的部署。營運商已用光學氣體成像和光纖陣列取代了傳統的「21號方法」調查,以避免運作,從而推動了高解析度相機組件的訂單成長。
氫能和碳捕獲、利用與封存(CCUS)管道計畫的快速擴張
由於氫分子比甲烷分子更小、擴散性更強,因此需要能夠偵測濃度低於1ppm的洩漏的檢測器。拉曼分析儀已被證明即使在幾公尺遠的距離也能展現出如此高的靈敏度。美國能源局已撥款2,500萬美元用於氫氣專用檢測技術的研發,目標是在2025年前完成。包括印度天然氣公司(GAIL)在內的印度國有企業已對專用氫氣幹線管道進行了評估,這使得對專用感測器的需求持續成長。
在現有管道中引入光纖和LiDAR需要大量資金投入。
分散式光纖感測的成本為每公里5萬至10萬美元,改造通常需要鑽孔和機架改造,進而影響處理能力。適用於危險區域的LiDAR探頭成本為20萬至50萬美元,原油價格下跌時,其部署受到限制。因此,儘管攜帶式超音波探測器的探測範圍有限,但低利潤生產的運營商仍然更傾向於使用此類探測器。
細分市場分析
到2025年,聲學和超音波系統將佔銷售額的26.74%,成為洩漏檢測解決方案市場中最大的單一技術類別。壓電感測器可在40公尺半徑範圍內提供即時警報,且無需校準,已成為陸上石油收集管線的重要提案。雷射吸收和雷射雷達平台雖然絕對銷售額仍然小規模,但其複合年成長率達到8.41%,這主要得益於監管機構對量化排放測量協議的批准。
隨著煉油廠營運商從手持式系統過渡到雲端連接系統,熱成像器因其能夠傳輸輻射數據進行預測分析而日益受到青睞。光纖分散式感測技術已在以往維護受限的海底回接管道沿線獲得了大量合約。分析模型表明,聲學技術在固定資產領域具有優越性,基於聲音發射的儲存槽監測定位誤差小於1%。
2025年,石油和天然氣產業佔銷售額的60.35%,反映了法定洩漏處罰以及碳氫化合物洩漏的重大影響。然而,受老化的輸水管道和乾旱導致的強制性節水措施的推動,供水事業實現了最快的成長,複合年成長率達到5.76%。供水事業部署了人工智慧分類器,在判斷飲用水管網是否有洩漏方面達到了98.3%的準確率。化學和發電企業根據其淨零排放政策採用了夾裝式流量計,而氫氣開發商則尋求基於拉曼光譜的檢測器以滿足安全論證要求。
區域分析
預計到2025年,北美將佔全球銷售額的37.70%,這主要得益於更嚴格的甲烷排放法規、管道安全法規以及諸如MethaneSAT等衛星檢驗項目的部署,該項目旨在監測頁岩盆地。加拿大的氫能發展藍圖進一步增加了專用洩漏感測器的訂單,而墨西哥跨境管道的建設也催生了對中游監測解決方案的額外需求。隨著煉油商逐步推進老舊設備的數位化改造,該地區洩漏檢測解決方案的市場規模預計將穩定成長。
亞太地區預計到2031年將以7.62%的複合年成長率成長。印度擴大了硬體進口和本地組裝,於2025年投資13億美元,用於建造一條2800公里長的液化石油氣管道並投入運作,同時撥款50億美元用於開發新的天然氣走廊。日本簽署了一項雙邊協議,旨在遏制甲烷洩漏,並資助了基於無人機的城市污水管道檢測技術的研究與開發。在中國,結合L波段雷達和透地雷達的技術被應用於偵測主要都市區道路下方水管的損壞,這促使地方政府加快了訂單。
在歐洲,隨著歐盟收緊企業永續發展報告和甲烷排放強度揭露要求,這一動能得以延續。業者沿著北海互聯線路鋪設光纖電纜,並投資購置配備雷射雷達的直升機來監測電網。儘管中東和非洲存在技術純熟勞工短缺的問題,但沿岸地區與封存(CCUS)樞紐的增加以及東非新建原油出口管道的建設,促成了承包洩漏檢測方案的合約簽訂。區域公共產業利用技術轉移協議來彌補產能缺口。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對甲烷洩漏實施嚴格監管(例如,美國的《通膨控制法》)
- 氫能和碳捕獲、利用與封存(CCUS)管道計畫的快速擴張
- 人工智慧驅動的預測分析可以減少誤報。
- 引入「洩漏檢測即服務(LDaaS)」經營模式
- 提供高解析度輻射資料的衛星星系
- 強制性ESG報告正在促進主動式漏洞管理。
- 市場限制因素
- 在現有管道中引入光纖和LiDAR需要大量資金投入。
- 新興市場缺乏熟練的熱成像和聲學技術人員
- 雲端連接LD系統中的網路安全漏洞
- 多相流條件下的誤報會降低操作人員的可靠性。
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素的影響
第5章 市場規模與成長預測
- 透過技術
- 聲學/超音波
- 壓力分析
- 熱成像
- 光纖
- 雷射吸收和LiDAR
- 蒸氣檢測
- E-RTTM
- 其他技術
- 按最終用戶行業分類
- 石油和天然氣
- 化學品
- 水處理
- 發電
- 其他最終用戶
- 按組件
- 硬體
- 軟體
- 服務
- 部署模式
- 固定式/固定式
- 可攜式/手持式
- 無人機搭載/航拍攝影
- 管道階段
- 上游工程
- 中游
- 下游工藝
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Honeywell International Inc.
- Aeris Technologies Inc.
- Bridger Photonics Inc.
- Schneider Electric SE
- Siemens Energy AG
- Xylem Inc.
- Krohne Messtechnik GmbH
- PSI Software AG
- Teledyne FLIR LLC
- ClampOn AS
- PermAlert(Division of Tremco Incorporated)
- OptaSense Ltd.(a Luna Innovations company)
- Physical Sciences Inc.
- Veeder-Root Company
- Atmos International Limited
- Emerson Electric Co.
- Baker Hughes Company-Avitas Systems
- Perma-Pipe International Holdings Inc.
- Sensit Technologies LLC
- Pentair plc
- Synodon Inc.
- INGU Solutions Inc.
- New Cosmos Electric Co. Ltd.
- Pressure Pipe Inspection Company(PPIC)
- Enagas SA
- TTK SAS
第7章 市場機會與未來展望
According to Mordor Intelligence, the leak detection solutions market size was valued at USD 4.58 billion in 2025 and estimated to grow from USD 4.83 billion in 2026 to reach USD 6.33 billion by 2031, at a CAGR of 5.53% during the forecast period (2026-2031).
This report is Segmented by Technology (Acoustic/Ultrasonic, Pressure Analysis, and More), End-User Industry (Oil and Gas, Chemical, Water Treatment, and More), Component (Hardware, Software, and Services), Deployment Mode (Fixed/Stationary, Portable/Handheld, and More), Pipeline Stage (Upstream, Midstream, and More), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa).
Global Leak Detection Solutions Market Trends and Insights
Stringent fugitive-methane regulations drive market transformation
The Inflation Reduction Act's methane surcharge, which started at USD 900 per metric ton in 2024 and climbs to USD 1,500 by 2026, re-shaped project economics by making continuous monitoring cheaper than paying fees. Complementary "Super Emitter" protocols allowed third parties to trigger operator response on leaks above 100 kg/hr, accelerating the adoption of fixed sensors and satellite data feeds. Operators substituted legacy Method 21 surveys with optical gas imaging and fiber-optic arrays to avoid downtime, lifting order volumes for high-resolution camera packages.
Rapid expansion of hydrogen and CCUS pipeline projects
Hydrogen molecules are smaller and more diffusive than methane, demanding detectors that spot leaks below 1 ppm; Raman analyzers demonstrated such sensitivity at several-meter stand-off distances. The U.S. Department of Energy earmarked USD 25 million for hydrogen-specific detection R&D in 2025. India's state operators, including GAIL, evaluated dedicated hydrogen trunklines, creating follow-on demand for specialized sensors.
High CAPEX for fiber-optic and LiDAR deployments in brown-field pipelines
Distributed fiber-optic sensing costs USD 50,000-100,000 per kilometer, and retrofits often require trenching or rack modifications that disrupt throughput. LiDAR heads suitable for hazardous zones were priced between USD 200,000 and USD 500,000, restricting adoption when crude prices softened. Operators in lower-margin basins thus favored portable ultrasonic detectors despite narrower coverage.
Other drivers and restraints analyzed in the detailed report include:
- AI-enabled predictive analytics lower false positives
- Satellite constellations enable global emissions transparency
- Scarcity of skilled thermography and acoustics technicians in emerging markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acoustic and ultrasonic systems held 26.74% of 2025 revenues, making them the largest single technology cohort in the leak detection solutions market. Piezo-electric sensors delivered instantaneous alerts within a 40 m radius and required no calibration, a value proposition that suited onshore gathering lines. Laser absorption and LiDAR platforms, while still smaller in absolute sales, expanded at an 8.41% CAGR, buoyed by regulatory recognition of quantified emission measurement protocols.
Thermal imagers moved from handheld to cloud-connected variants that streamed radiometric data for predictive analytics, broadening appeal among refinery operators. Fiber-optic distributed sensing gained contracts along subsea tiebacks where maintenance access was limited. Analytical modeling showed sub-1% localization error for acoustic-emission-based storage-tank monitoring, validating acoustic dominance in fixed assets.
The oil and gas sector captured 60.35% of 2025 revenue, reflecting statutory leak fees and the high-consequence nature of hydrocarbon releases. Nevertheless, water treatment utilities logged the quickest expansion at 5.76% CAGR, spurred by aging mains and drought-linked loss-reduction mandates. Utilities deployed AI classifiers that achieved 98.3% accuracy on leak/no-leak differentiation in potable networks. Chemical and power-generation operators adopted clamp-on flowmeters following corporate net-zero policies, while hydrogen developers demanded Raman-based detectors to satisfy safety case requirements.
Complete Report Scope:
- By Technology
- Acoustic / Ultrasonic
- Pressure Analysis
- Thermal Imaging
- Fiber Optic
- Laser Absorption and LiDAR
- Vapor Sensing
- E-RTTM
- Other Technologies
- By End-User Industry
- Oil and Gas
- Chemical
- Water Treatment
- Power Generation
- Other End-Users
- By Component
- Hardware
- Software
- Services
- By Deployment Mode
- Fixed / Stationary
- Portable / Handheld
- Drone-Mounted / Aerial
- By Pipeline Stage
- Upstream
- Midstream
- Downstream
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 37.70% of global revenue in 2025 owing to methane-fee statutes, enhanced pipeline safety regulations, and the rollout of satellite verification programs such as MethaneSAT that scrutinized shale basins. Canada's hydrogen roadmap further boosted orders for specialized leak sensors, while Mexico's cross-border pipeline build created incremental demand for midstream monitoring solutions. The leak detection solutions market size in the region is forecast to advance steadily as refiners digitize aging assets.
Asia-Pacific recorded a 7.62% CAGR through 2031. India commissioned a USD 1.3 billion, 2,800 km LPG pipeline in 2025 and earmarked USD 5 billion for new gas corridors, lifting hardware imports, and local assembly. Japan signed bilateral pacts to curb methane leakage and funded R&D on drone-based inspections for municipal sewer lines. China expanded L-band SAR combined with ground-penetrating radar to detect water-line failures beneath urban arteries, accelerating municipal orders.
Europe maintained momentum as the EU tightened corporate sustainability reporting and methane-intensity disclosure. Operators integrated fiber-optic strings along North Sea interconnectors and invested in LiDAR-equipped helicopters to monitor distribution grids. The Middle East and Africa lagged in skilled labor, but rising CCUS hubs in the Gulf and new crude export pipelines in East Africa unlocked contracts for turnkey leak detection packages. Regional utilities leveraged technology transfer agreements to bridge capability gaps.
- Honeywell International Inc.
- Aeris Technologies Inc.
- Bridger Photonics Inc.
- Schneider Electric SE
- Siemens Energy AG
- Xylem Inc.
- Krohne Messtechnik GmbH
- PSI Software AG
- Teledyne FLIR LLC
- ClampOn AS
- PermAlert (Division of Tremco Incorporated)
- OptaSense Ltd. (a Luna Innovations company)
- Physical Sciences Inc.
- Veeder-Root Company
- Atmos International Limited
- Emerson Electric Co.
- Baker Hughes Company - Avitas Systems
- Perma-Pipe International Holdings Inc.
- Sensit Technologies LLC
- Pentair plc
- Synodon Inc.
- INGU Solutions Inc.
- New Cosmos Electric Co. Ltd.
- Pressure Pipe Inspection Company (PPIC)
- Enagas S.A.
- TTK SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent fugitive-methane regulations (e.g., U.S. Inflation Reduction Act)
- 4.2.2 Rapid expansion of hydrogen and CCUS pipeline projects
- 4.2.3 AI-enabled predictive analytics lowers false positives
- 4.2.4 Adoption of leak-detection-as-a-service (LDaaS) business models
- 4.2.5 Satellite constellations providing high-resolution emissions data
- 4.2.6 Mandatory ESG reporting driving proactive leak management
- 4.3 Market Restraints
- 4.3.1 High CAPEX for fiber-optic and LiDAR deployments in brown-field pipelines
- 4.3.2 Scarcity of skilled thermography and acoustics technicians in emerging markets
- 4.3.3 Cyber-security vulnerabilities in cloud-linked LD systems
- 4.3.4 False alarms in multiphase flow conditions reducing operator confidence
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Acoustic / Ultrasonic
- 5.1.2 Pressure Analysis
- 5.1.3 Thermal Imaging
- 5.1.4 Fiber Optic
- 5.1.5 Laser Absorption and LiDAR
- 5.1.6 Vapor Sensing
- 5.1.7 E-RTTM
- 5.1.8 Other Technologies
- 5.2 By End-User Industry
- 5.2.1 Oil and Gas
- 5.2.2 Chemical
- 5.2.3 Water Treatment
- 5.2.4 Power Generation
- 5.2.5 Other End-Users
- 5.3 By Component
- 5.3.1 Hardware
- 5.3.2 Software
- 5.3.3 Services
- 5.4 By Deployment Mode
- 5.4.1 Fixed / Stationary
- 5.4.2 Portable / Handheld
- 5.4.3 Drone-Mounted / Aerial
- 5.5 By Pipeline Stage
- 5.5.1 Upstream
- 5.5.2 Midstream
- 5.5.3 Downstream
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Honeywell International Inc.
- 6.4.2 Aeris Technologies Inc.
- 6.4.3 Bridger Photonics Inc.
- 6.4.4 Schneider Electric SE
- 6.4.5 Siemens Energy AG
- 6.4.6 Xylem Inc.
- 6.4.7 Krohne Messtechnik GmbH
- 6.4.8 PSI Software AG
- 6.4.9 Teledyne FLIR LLC
- 6.4.10 ClampOn AS
- 6.4.11 PermAlert (Division of Tremco Incorporated)
- 6.4.12 OptaSense Ltd. (a Luna Innovations company)
- 6.4.13 Physical Sciences Inc.
- 6.4.14 Veeder-Root Company
- 6.4.15 Atmos International Limited
- 6.4.16 Emerson Electric Co.
- 6.4.17 Baker Hughes Company - Avitas Systems
- 6.4.18 Perma-Pipe International Holdings Inc.
- 6.4.19 Sensit Technologies LLC
- 6.4.20 Pentair plc
- 6.4.21 Synodon Inc.
- 6.4.22 INGU Solutions Inc.
- 6.4.23 New Cosmos Electric Co. Ltd.
- 6.4.24 Pressure Pipe Inspection Company (PPIC)
- 6.4.25 Enagas S.A.
- 6.4.26 TTK SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 手持式鋰電池洩漏檢測儀市場:全球市場預測,2026-2032年洩漏檢測市場-2026-2032年全球市場預測
 智慧洩漏檢測包裝市場預測至2034年-全球分析(按檢測方法、包裝類型、整合、應用、最終用戶和地區分類)
 2026年全球交易不一致檢測與修復市場報告
 氣體洩漏檢測器市場:按產品類型、應用、技術和地區分類2026年全球無人機輔助大壩滲漏檢測市場報告
 油氣管道洩漏檢測市場規模、佔有率和趨勢分析報告:按技術、管道類型、應用、地區和細分市場分類(2026-2033 年)2026年全球洩漏檢測與修復市場報告超音波氣體洩漏檢測儀市場:全球市場預測(按產品類型、技術、最終用戶、應用和銷售管道),2026-2032年洩漏檢測燈市場:按技術、檢測類型、組件、服務類型、應用和最終用戶分類-2026-2032年全球預測