


 |
市場調查報告書
商品編碼
2124637
歐洲可生物分解杯:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Europe Biodegradable Cups - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
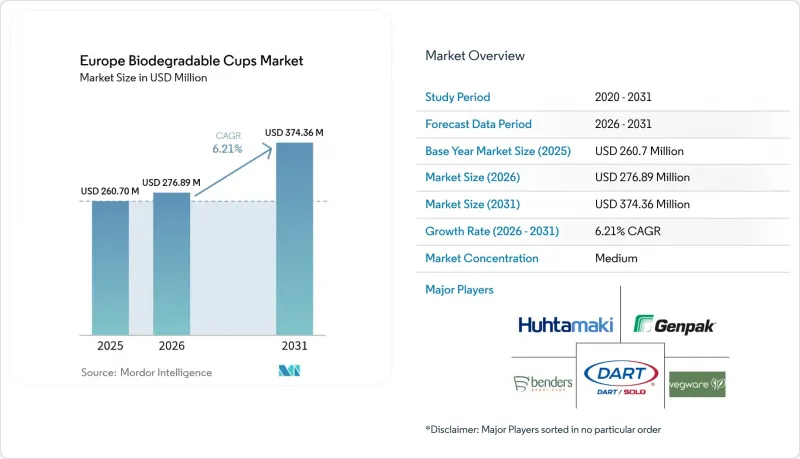
根據 Mordor Intelligence 預測,歐洲可生物分解杯市場規模將從 2025 年的 2.607 億美元成長到 2026 年的 2.7689 億美元,然後在 2031 年達到 3.7436 億美元,2026 年至 2031 年的複合成長率為 6.21%。
本報告按材料類型(生質塑膠、紙張、甘蔗渣、植物纖維)、應用領域(飲料、食品)、最終用戶(餐飲服務業、公共機構、一般家庭)、分銷管道(線下、線上)和地區(英國、德國、法國、義大利、西班牙、比荷盧經濟聯盟及其他歐洲國家)進行細分。市場預測以美元計價。
歐洲可生物分解杯市場的趨勢與洞察
餐飲服務業對永續包裝材料的需求日益成長
歐洲消費者越來越反感一次性塑膠製品。根據2024年歐洲晴雨表調查,78%的消費者在選擇購買商品時會考慮永續性。餐飲公司和快餐連鎖店正在採購政策中體現這種消費者意識;例如,指南針集團已在其2000家門市將62%的杯子採購替換為可堆肥材料。麥當勞於2025年2月承諾,將在其英國和愛爾蘭的所有門市停止使用聚乙烯內襯杯,並引入水塗層纖維杯。歐盟法規也在推動這一趨勢,規定到2030年所有包裝都必須是可回收或可堆肥的。價格接受度因情況而異;瑞典消費者願意接受高達12%的價格上漲,而義大利和西班牙等價格敏感型企業則要求在進行轉換時成本保持不變。
歐盟對一次性塑膠製品製定了嚴格的法規
預計各成員國將在2024年前全面實施一次性塑膠指令,阻塞漏洞並擴大禁令範圍。在西班牙,自2024年1月起,餐飲場所將禁止使用不可堆肥的杯子,違者最高可處以60萬歐元的罰款。在法國,AGEC法案設定了2025年可重複使用包裝佔比達到20%的目標,同時禁止Oxo可分解塑膠,這將導致短期內對經認證的可堆肥杯子的需求增加。在義大利,一次性杯子現在必須含有至少40%的生物基材料,這有效地為PLA塗層和纖維材料的替代品騰出了貨架空間。在德國和荷蘭,對不可回收的杯子徵收生產者延伸責任(EPR)費用,並且傳統塑膠的相對成本正在上升,這加速了歐洲對可生物分解杯子的採用。
與傳統紙杯和塑膠杯相比,成本差異
2025年第一季,12盎司PLA內襯杯的售價為0.09歐元至0.12歐元,而聚乙烯塗層杯的售價為0.07歐元至0.09歐元,這意味著15%至25%的價格溢價,對於利潤空間有限的咖啡館來說難以負擔。獨立企業,尤其是在南歐,對價格的彈性很高,54%的企業表示,如果單價上漲超過0.03歐元,他們將推遲更換杯子。雖然德國和法國的生產者延伸責任制(EPR)費用可以減輕更換認證杯帶來的成本負擔,但在義大利和中歐,類似的抵銷作用仍然微乎其微,阻礙了歐洲可生物分解杯市場銷售量的轉變。
細分市場分析
生質塑膠是成長最快的材料類別,預計將以8.02%的複合年成長率成長,這主要得益於供應過剩導致PLA樹脂價格下降,並促進了其對聚乙烯內襯的替代方案。 PBAT共混物由於耐熱性提升,在熱飲領域佔了18%的市佔率。聚羥基烷酯等新興材料因其在海洋環境中的生物分解性,降低了與廢棄物問題相關的法律責任,正吸引沿海企業的注意。紙張仍以37.92%的市佔率保持領先地位,但其成長緩慢,部分原因是纖維杯在高溫耐熱性方面仍落後於PLA。歐洲牛皮紙漿的平均價格居高不下,預計到2025年第一季將達到每噸1,420歐元(1,562美元),這也對加工商的利潤率造成了壓力。甘蔗渣和麥秸等基材在歐盟農業廢棄物利用計畫下獲得了政策支持,但由於模塑能力有限,仍屬於小眾市場。生質塑膠的興起凸顯了更廣泛的轉變。隨著不同材料性能差距的縮小,歐洲可生物分解杯市場的成長正日益轉向那些既能提供高阻隔性能又不影響可堆肥性的樹脂。
紙杯由於耐高溫液體性能差以及依賴水性塗層,其長期發展前景受到限制。儘管如此,紙杯在製造商生產線上的高普及率和消費者的熟悉度使其成為價格敏感型買家永續級選擇。相較之下,生質塑膠在機構投資者的詢價中越來越受到關注,這表明採購團隊正在優先考慮認證和耐熱性,而不是傳統的供應鏈。這種成分的轉變意味著,即使紙杯在冷飲領域保持其傳統地位,預計到本十年末,生質塑膠的銷售將接近紙杯。在歐洲可生物分解杯市場,能夠靈活運用纖維塗層杯和樹脂塗層杯的公司將獲得最廣泛的基本客群。
到2025年,飲料業將佔據歐洲可生物分解杯市場70.12%的主導佔有率,預計到2031年將以7.05%的複合年成長率穩步成長。雖然熱飲的需求量最大,但冷飲在夏季的需求量激增,這為生產計畫靈活的加工商帶來了機會。飲料企業優先考慮嚴格的尺寸公差,以實現自動杯蓋的精準匹配,這推動了高規格PLA杯和層級構造纖維杯的普及。
包括湯、麵條和甜點在內的食品市場預計將以約6.55%的複合年成長率成長,這主要得益於快餐連鎖店熱食外帶菜單的擴張。與飲料杯相比,大容量杯的平均售價更高,從而提升了製造商的利潤率。然而,由於填充溫度和油含量不穩定,需要採用多層結構,這導致成本增加,限制了小規模咖啡館的採用。在歐洲,可生物分解食品杯的市場佔有率正在緩慢但穩定成長,因為機構買家優先考慮包含食物廢棄物和杯子堆肥的閉合迴路廢棄物管理合約。隨著這些合約的普及,食品杯與飲料杯一樣,市場地位日益穩固。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 餐飲服務業對永續包裝材料的需求日益成長
- 歐盟對一次性塑膠製品製定了嚴格的法規
- 咖啡連鎖店的政策是逐步過渡到100%可堆肥咖啡杯
- PLA產能過剩導致價格下降。
- 零售商主導的自有品牌環保包裝競爭
- 人工智慧最佳化的塗裝生產線可降低缺陷率。
- 市場限制因素
- 與傳統紙杯和塑膠杯相比,價格較高
- 工業堆肥基礎設施因地區而異。
- 紙漿價格上漲和供應波動
- 可重複使用杯子的押金制度正在蠶食市場需求。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 依材料類型
- 生質塑膠
- 聚乳酸(PLA)
- 聚(己二酸對苯二甲酸丁二醇酯)(PBAT)
- 聚丁二酸丁二醇酯(PBS)
- 聚羥基烷酯(PHA)
- 其他生質塑膠
- 紙
- 甘蔗渣和植物纖維
- 生質塑膠
- 透過使用
- 飲料
- 食物
- 最終用戶
- 餐飲場所(咖啡館和飯店)
- 機構(購物中心和商業設施)
- 家
- 透過分銷管道
- 離線
- 線上
- 國家
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 比荷盧經濟聯盟
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Huhtamaki Oyj
- Vegware Ltd.
- Dart Container Corporation
- Benders Paper Cups Ltd.
- Genpak LLC
- Pactiv LLC
- Seda International Packaging Group SpA
- Stora Enso Oyj
- Eco-Products LLC
- International Paper Company
- Graphic Packaging Holding Company
- Fabri-Kal LLC
- Go-Pak Holdings Ltd.
- Bio Futura BV
- BVO International GmbH
- Scyphus Ltd.
- Colpac Ltd.
- Seda Group UK Ltd.
- World Centric Inc.
- NatureWorks LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe biodegradable cups market size is expected to grow from USD 260.7 million in 2025 to USD 276.89 million in 2026 and is forecast to reach USD 374.36 million by 2031 at 6.21% CAGR over 2026-2031.
This report is Segmented by Material Type (Bio-Plastics, Paper, Bagasse and Plant Fibre), Application (Beverages, Food), End User (Food Service Outlets, Institutional, Household), Distribution Channel (Offline, and Online), and Geography (United Kingdom, Germany, France, Italy, Spain, Benelux, Rest of Europe). Market Forecasts are Provided in Terms of Value (USD).
Europe Biodegradable Cups Market Trends and Insights
Growing Demand for Sustainable Foodservice Packaging
European consumers are showing a growing intolerance for single-use plastics. A 2024 Eurobarometer survey reported that 78% now factor sustainability into venue choice. Contract caterers and quick-service chains translate sentiment into procurement policies, as evidenced by Compass Group shifting 62% of cup purchases to compostable materials across 2,000 sites. McDonald's committed in February 2025 to fiber cups with water-based coatings for every UK and Ireland outlet, eliminating polyethylene liners. EU regulations reinforce preference, mandating that all packaging be recyclable or compostable by 2030. Willingness to pay varies-Swedish patrons accept price increases of up to 12%, while operators in price-sensitive Italy and Spain demand cost parity before switching.
Stringent EU Single-Use Plastics Regulations
Member states are expected to reach full enforcement of the Single-Use Plastics Directive in 2024, closing loopholes and expanding bans. Spain prohibited the use of non-compostable cups in hospitality venues as of January 2024, with fines of up to EUR 600,000. France's AGEC law set a 2025 target for 20% reusable packaging but simultaneously banned Oxo-degradable plastics, boosting short-run demand for certified compostable cups. Italy now requires single-use cups to contain at least 40% bio-based content, essentially reserving shelf space for PLA-lined or fiber alternatives. Extended producer responsibility fees on non-recyclable cups in Germany and the Netherlands raise the relative cost of traditional plastics, accelerating the adoption of biodegradable cups in Europe.
Cost Premium Versus Conventional Paper and Plastic Cups
In Q1 2025, a 12-ounce PLA-lined cup sold for EUR 0.09-0.12, compared to EUR 0.07-0.09 for polyethylene-coated units, resulting in a 15-25% premium that margin-constrained cafes struggle to absorb. Independent operators, especially in Southern Europe, exhibit high price elasticity: 54% would postpone switching if unit costs rise more than EUR 0.03. While EPR fees reduce the penalty on certified cups in Germany and France, similar offsets remain minimal in Italy or Central Europe, tempering volume conversion in the Europe biodegradable cups market.
Other drivers and restraints analyzed in the detailed report include:
- Excess PLA Production Capacity Drives Price Cuts
- Coffee Chain Commitments to 100% Compostable Cups
- Patchy Industrial Composting Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bio-plastics represent the fastest-growing material class, forecast to rise at 8.02% CAGR as oversupply trims PLA resin prices and spurs substitution away from polyethylene liners. PBAT blends captured an additional 18% share, thanks to their improved heat resistance for hot drinks. Emerging polyhydroxyalkanoates attract coastal operators because marine degradability eases litter liability. Paper retains the largest slice at 37.92% but expands more slowly, partly because fiber cups still underperform PLA in high-temperature service. Elevated pulp costs, with European kraft pulp averaging EUR 1,420 per ton (USD 1,562) in Q1 2025, also weigh on converter margins. Bagasse and wheat-straw substrates draw policy support under EU agricultural-waste valorization schemes, yet remain niche due to limited forming capacity. The traction of bioplastics underlines a broader pivot: as material parity improves, the Europe biodegradable cups market growth increasingly flows to resins that deliver high barrier performance without compromising compostability.
The paper's durability issues with steaming liquids and its reliance on water-based coatings constrain its long-term outlook. Nonetheless, its ubiquity in converter lines and consumer familiarity keep it the entry-level sustainable option for price-sensitive buyers. In contrast, bio-plastics now command greater attention in requests for quotation issued by institutional buyers, signaling that procurement teams value certifications and heat performance over legacy supply relationships. This mix shift ensures that bio-plastics' unit volumes will close in on paper by the end of the decade, even if the latter maintains a legacy footprint in the cold-drink service. Europe biodegradable cups market players, able to flex between fiber- and resin-lined cups, stand to secure the widest customer base.
In 2025, beverages held a dominant 70.12% share of the Europe biodegradable cups market, with projections indicating a robust 7.05% CAGR growth rate extending through 2031. Hot drinks drive most demand, yet iced beverages deliver incremental summer spikes that reward converters with agile scheduling. Beverage operators prize tight dimensional tolerances for automated lid fit, nudging them toward higher-spec PLA or dual-layer fiber cups.
The food segment, encompassing soups, noodles, and desserts, is projected to grow at a rate of approximately 6.55% CAGR, driven by the expansion of quick-service chains into hot-food-to-go menus. Larger cup formats push average selling prices higher than those of drinks, thereby cushioning converter margins. However, variable fill temperatures and oil content necessitate multilayer construction, which raises costs and limits uptake in smaller cafes. Europe biodegradable cups market share in food applications grows slowly but steadily because institutional buyers value closed-loop waste contracts that include food residues plus cup composting. As these contracts proliferate, food cups gain a firmer beachhead alongside beverages.
Complete Report Scope:
- By Material Type
- Bio-Plastics
- Polylactic Acid (PLA)
- Poly(Butylene Adipate-co-Terephthalate) (PBAT)
- Polybutylene Succinate (PBS)
- Polyhydroxyalkanoates (PHA)
- Other Bio-Plastics
- Paper
- Bagasse and Plant Fibre
- Bio-Plastics
- By Application
- Beverages
- Food
- By End User
- Food Service Outlets (Cafes and Hotels)
- Institutional (Malls and Commercial Establishments)
- Household
- By Distribution Channel
- Offline
- Online
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Benelux
- Rest of Europe
List of Companies Covered in this Report:
- Huhtamaki Oyj
- Vegware Ltd.
- Dart Container Corporation
- Benders Paper Cups Ltd.
- Genpak LLC
- Pactiv LLC
- Seda International Packaging Group S.p.A.
- Stora Enso Oyj
- Eco-Products LLC
- International Paper Company
- Graphic Packaging Holding Company
- Fabri-Kal LLC
- Go-Pak Holdings Ltd.
- Bio Futura B.V.
- B-V-O International GmbH
- Scyphus Ltd.
- Colpac Ltd.
- Seda Group UK Ltd.
- World Centric Inc.
- NatureWorks LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for Sustainable Foodservice Packaging
- 4.2.2 Stringent EU Single-Use Plastics Regulations
- 4.2.3 Coffee Chain Commitments to 100 % Compostable Cups
- 4.2.4 Excess PLA Production Capacity Drives Price Cuts
- 4.2.5 Retailer-Led Private-Label Eco-Packaging Race
- 4.2.6 AI-Optimised Coating Lines Reduce Scrap Rates
- 4.3 Market Restraints
- 4.3.1 Cost Premium Versus Conventional Paper and Plastic Cups
- 4.3.2 Patchy Industrial Composting Infrastructure
- 4.3.3 Rising Pulp Prices and Supply Volatility
- 4.3.4 Reusable Cup Deposit Systems Cannibalise Demand
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Bio-Plastics
- 5.1.1.1 Polylactic Acid (PLA)
- 5.1.1.2 Poly(Butylene Adipate-co-Terephthalate) (PBAT)
- 5.1.1.3 Polybutylene Succinate (PBS)
- 5.1.1.4 Polyhydroxyalkanoates (PHA)
- 5.1.1.5 Other Bio-Plastics
- 5.1.2 Paper
- 5.1.3 Bagasse and Plant Fibre
- 5.1.1 Bio-Plastics
- 5.2 By Application
- 5.2.1 Beverages
- 5.2.2 Food
- 5.3 By End User
- 5.3.1 Food Service Outlets (Cafes and Hotels)
- 5.3.2 Institutional (Malls and Commercial Establishments)
- 5.3.3 Household
- 5.4 By Distribution Channel
- 5.4.1 Offline
- 5.4.2 Online
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Benelux
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Huhtamaki Oyj
- 6.4.2 Vegware Ltd.
- 6.4.3 Dart Container Corporation
- 6.4.4 Benders Paper Cups Ltd.
- 6.4.5 Genpak LLC
- 6.4.6 Pactiv LLC
- 6.4.7 Seda International Packaging Group S.p.A.
- 6.4.8 Stora Enso Oyj
- 6.4.9 Eco-Products LLC
- 6.4.10 International Paper Company
- 6.4.11 Graphic Packaging Holding Company
- 6.4.12 Fabri-Kal LLC
- 6.4.13 Go-Pak Holdings Ltd.
- 6.4.14 Bio Futura B.V.
- 6.4.15 B-V-O International GmbH
- 6.4.16 Scyphus Ltd.
- 6.4.17 Colpac Ltd.
- 6.4.18 Seda Group UK Ltd.
- 6.4.19 World Centric Inc.
- 6.4.20 NatureWorks LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


