


 |
市場調查報告書
商品編碼
2120748
美國Li-Fi:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)US Li-Fi - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,美國 Li-Fi 市場規模預計在 2025 年達到 4.2 億美元,2026 年達到 4.549 億美元,到 2031 年達到 6.788 億美元,2026 年至 2031 年的複合年成長率為 8.31%。
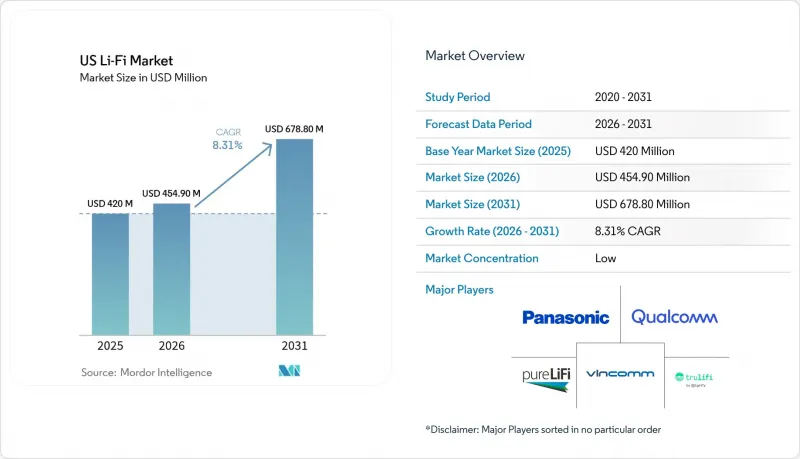
本報告按組件(LED光源、光電二極體等)、技術(基於LED的Li-Fi [VLC]、基於雷射的Li-Fi [NIR]、混合Li-Fi/RF系統)和終端用戶行業(醫療保健、交通運輸、教育、軍事與國防、零售與酒店以及其他終端用戶行業)進行細分。市場預測以美元(USD)計價。
美國Li-Fi市場的趨勢與洞察
加速強制更換LED燈具將推動基礎設施發展。
加州第24號法規和IECC 2021標準正在推動LED照明的普及,導致天花板內安裝了兼具Li-Fi網路基地台功能的發送器。 ASHRAE 90.1標準提倡網路化照明控制,使建築物業主能夠透過一次投資同時實現節能和Gigabit連接。乙太網路供電(PoE)回程傳輸簡化了安裝工作,因為低壓電纜和資料電纜共用同一條線路。設施管理人員意識到,每個燈具都成為受管理的網路節點,Li-Fi自然而然地整合到智慧建築控制面板中,而不是作為獨立系統運作。因此,與透過疊加方式增加Wi-Fi密度相比,每平方英尺的總成本更低。
射頻頻譜擁塞正在推動企業採用射頻技術。
在都市區校園中,6 GHz Wi-Fi 頻道已飽和。 Li-Fi 透過遷移到 400-800 THz 頻段繞過了這一瓶頸,該頻段提供的可用頻寬是 6 GHz Wi-Fi 的 10,000 倍。由於光線無法穿透牆壁或天花板,因此可以按樓層重複使用,無需任何調整即可將吞吐量增加一倍。銀行和律師事務所非常欣賞這種封閉式訊號,因為它降低了被竊聽的風險。在工廠中,Li-Fi 可以忽略焊接設備周圍干擾射頻通訊的電磁干擾,從而能夠記錄更精確的機器遙測數據。弗勞恩霍夫研究所的「GigaDock」演示實現了 12.5 Gbps 的通訊速度和低於 1 毫秒的延遲,展示了一種可支援工業 4.0 工作負載的確定性通訊鏈路。
視線距離的限制制約了覆蓋範圍的經濟性。
由於每個隔間的牆壁和移動的人員都會阻擋光路,因此Li-Fi所需的網路基地台密度高於Wi-Fi。反射式天花板可以擴大覆蓋範圍,但會降低吞吐量,因此負責人必須權衡冗餘性和預算。零售商表示,商店佈局的季節性變化會擾亂線性視圖,增加維護負擔。光束控制雷射有望提供更寬的光束角,但其設備比通用LED燈更昂貴。在自動覆蓋映射軟體成熟之前,各場所必須權衡Li-Fi的行動風險和安全優勢。
細分市場分析
到2025年,LED光源將佔據Li-Fi市場49.12%的佔有率,這意味著照明裝置也將兼具寬頻閘道器的功能。由於每盞燈本身就消耗電力並佔用天花板空間,因此額外的成本只需涵蓋調製驅動器和檢測器。這種綜效縮短了那些計劃改用LED以滿足能源法規要求的建築業主的投資回收期。光電二極體在硬體中佔比第二大。這是因為每個連結都需要一個接收通道,而在雙向通訊的雙工配置中,二極體的數量會翻倍。微控制器負責管理超過50 MHz的脈衝寬度調製,同時防止閃爍,符合IEEE PAR1789標準。
軟體和韌體的複合年成長率 (CAGR) 為 10.08%,是整個組件產品線中成長最快的。這主要是由於混合 Li-Fi 和 Wi-Fi編配中需要演算法來確定哪些會話在哪些頻寬上傳輸。網路管理主機現在類似於照明儀錶板,將照度等級、佔用偵測和吞吐量圖表整合到一個通用螢幕上。調製器 ASIC 現在整合了先前位於插件卡上的訊號調理功能,從而縮小了機殼尺寸,使得收發器可以安裝在檯燈內部。系統整合服務也隨之成長,整合了光度功能和射頻規劃工具,使設計人員能夠在單一模型中檢驗覆蓋範圍和法規符合性。因此,隨著早期採用者對可靠性能的需求不斷成長,Li-Fi 市場中服務的投入成長速度超過了硬體支出。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 美國正在加快商業建築強制改用LED照明的腳步。
- 射頻頻段擁塞以及對安全室內無線通訊的需求。
- 聯邦政府為軍事和國防部門的Li-Fi示範計畫提供資金。
- 工業4.0對確定性、低延遲連結的需求
- 支援PoE供電的智慧照明回程傳輸的經濟性
- 根據《晶片和整合產品法案》(CHIPS Act)對國內供應的光接收器給予優惠待遇
- 市場限制因素
- 視野範圍有限
- 消費性設備缺乏原生Li-Fi晶片組
- 區域性閃爍差異以及與遵守建築規範相關的挑戰。
- 來自 Wi-Fi 7 和 5G 企業級分散式天線系統的競爭威脅
- 價值鏈分析
- 監理情勢
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按組件
- LED光源
- 光電二極體
- 微控制器
- 調製器/訊號處理專用積體電路
- 軟體韌體
- 系統整合和服務
- 透過技術
- 以LED為基礎的Li-Fi(VLC)
- 以雷射為基礎的Li-Fi(近紅外線)
- 混合式Li-Fi/RF系統
- 按最終用戶行業分類
- 衛生保健
- 運輸
- 教育
- 軍事/國防
- 零售和酒店
- 其他終端用戶產業(航太、工業自動化等)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- pureLiFi Ltd.
- Signify Holding(Trulifi)
- VLNComm Inc.
- Acuity Brands, Inc.(Atrius)
- Qualcomm Technologies, Inc.
- Panasonic Holdings Corporation
- OLEDCOMM SAS
- LVX System Corporation
- Vibrint Inc.
- SaNoor Technologies Inc.
- Outstanding Technology Corp.
第7章 市場機會與未來展望
According to Mordor Intelligence, the US li-Fi market size is projected to be USD 420 million in 2025, USD 454.90 million in 2026, and reach USD 678.80 million by 2031, growing at a CAGR of 8.31% from 2026 to 2031.
This report is Segmented by Component (LED Light Sources, Photodiodes, and More), Technology (LED-Based Li-Fi [VLC], Laser-Based Li-Fi [NIR], Hybrid Li-Fi/RF Systems), and End-User Industry (Healthcare, Transportation, Education, Military and Defense, Retail and Hospitality, Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
US Li-Fi Market Trends and Insights
Accelerated LED Retrofit Mandates Drive Infrastructure Foundation
California's Title 24 codes and the IECC 2021 model elevate LED adoption, inadvertently wiring ceilings with transmitters that double as Li-Fi access points . ASHRAE 90.1 pushes connected-lighting controls, letting building owners recover both energy savings and gigabit connectivity in a single investment. Power-over-Ethernet backhaul trims installation labor because low-voltage cable and data share the same run. Facility managers discover that every luminaire becomes a managed network node, so Li-Fi slips naturally into smart-building dashboards rather than standing alone. The outcome is a lower total cost per square foot compared with overlay Wi-Fi densification.
RF Spectrum Congestion Catalyzes Enterprise Adoption
Urban campuses already saturate 6 GHz Wi-Fi channels; Li-Fi escapes that bottleneck by moving up to the 400-800 THz band that offers 10,000 times the available spectrum. Light cannot leak through walls or ceilings, so floor-by-floor reuse multiplies throughput without coordination overhead. Banks and law firms appreciate the room-contained signal that curbs eavesdropping risk. Factories record cleaner machine telemetry because Li-Fi ignores electromagnetic interference that cripples RF near welders. Fraunhofer's GigaDock demo hit 12.5 Gbps with sub-millisecond latency, proving deterministic links for Industry 4.0 workloads .
Line-of-Sight Limitations Constrain Coverage Economics
Every cubicle wall and moving body can sever an optical path, forcing denser access-point grids than Wi-Fi needs. Reflective ceilings extend reach but cut throughput, so planners must balance redundancy with budget. Retailers find that seasonal aisle resets break line-of-sight maps, adding maintenance overhead. Although beam-steered lasers promise wider cones, the gear costs more than commodity LED lamps. Until automated coverage-mapping software matures, facilities weigh mobility risk against Li-Fi's security upside.
Other drivers and restraints analyzed in the detailed report include:
- Federal Defense Funding Accelerates Military Applications
- Industry 4.0 Demands Deterministic Connectivity
- Device Integration Barriers Limit Market Expansion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
LED light sources held 49.12% of the Li-Fi market share in 2025, demonstrating how illumination assets double as broadband gateways. Each lamp already draws power and occupies ceiling real estate, so incremental cost covers only modulation drivers and photodetectors. That synergy compresses payback periods for building owners who planned LED conversions to meet energy codes. Photodiodes follow as the next-largest hardware slice because every link needs a receive channel, and bidirectional traffic doubles diode counts in duplex installations. Microcontrollers oversee pulse-width modulation that exceeds 50 MHz yet stays flicker-free under IEEE PAR1789 guidance.
Software and firmware post a 10.08% CAGR, the fastest across component lines, because hybrid Li-Fi/Wi-Fi orchestration demands algorithms that decide which band carries which session. Network-management consoles now resemble lighting dashboards, merging lux level, occupancy sensing, and throughput graphs on a common pane. Modulator ASICs integrate signal conditioning that once lived on plug-in cards, trimming enclosure volume so transceivers fit inside desk lamps. System-integration services grow in lockstep, bundling photometrics with RF planning tools so architects can validate coverage and code compliance in one model. The Li-Fi market size allocation for services, therefore, rises faster than hardware outlays as early adopters seek guaranteed performance.
Complete Report Scope:
- By Component
- LED Light Sources
- Photodiodes
- Microcontrollers
- Modulators/Signal-Processing ASICs
- Software and Firmware
- System Integration and Services
- By Technology
- LED-based Li-Fi (VLC)
- Laser-based Li-Fi (NIR)
- Hybrid Li-Fi/RF Systems
- By End-user Industry
- Healthcare
- Transportation
- Education
- Military and Defense
- Retail and Hospitality
- Other End-user Industries (Aerospace, Industrial Automation,and others)
List of Companies Covered in this Report:
- pureLiFi Ltd.
- Signify Holding (Trulifi)
- VLNComm Inc.
- Acuity Brands, Inc. (Atrius)
- Qualcomm Technologies, Inc.
- Panasonic Holdings Corporation
- OLEDCOMM SAS
- LVX System Corporation
- Vibrint Inc.
- SaNoor Technologies Inc.
- Outstanding Technology Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated LED retrofit mandates in US commercial buildings
- 4.2.2 RF spectrum congestion and secure indoor-wireless demand
- 4.2.3 Federal funding for military/defense Li-Fi pilots
- 4.2.4 Industry 4.0 demand for deterministic low-latency links
- 4.2.5 PoE-enabled smart-lighting backhaul economics
- 4.2.6 CHIPS-Act incentives for domestic optical-receiver supply
- 4.3 Market Restraints
- 4.3.1 Limited line-of-sight coverage range
- 4.3.2 Lack of native Li-Fi chipsets in mass-market devices
- 4.3.3 Fragmented local flicker and building-code compliance hurdles
- 4.3.4 Competitive threat from Wi-Fi 7 and 5G enterprise DAS
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 LED Light Sources
- 5.1.2 Photodiodes
- 5.1.3 Microcontrollers
- 5.1.4 Modulators/Signal-Processing ASICs
- 5.1.5 Software and Firmware
- 5.1.6 System Integration and Services
- 5.2 By Technology
- 5.2.1 LED-based Li-Fi (VLC)
- 5.2.2 Laser-based Li-Fi (NIR)
- 5.2.3 Hybrid Li-Fi/RF Systems
- 5.3 By End-user Industry
- 5.3.1 Healthcare
- 5.3.2 Transportation
- 5.3.3 Education
- 5.3.4 Military and Defense
- 5.3.5 Retail and Hospitality
- 5.3.6 Other End-user Industries (Aerospace, Industrial Automation,and others)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 pureLiFi Ltd.
- 6.4.2 Signify Holding (Trulifi)
- 6.4.3 VLNComm Inc.
- 6.4.4 Acuity Brands, Inc. (Atrius)
- 6.4.5 Qualcomm Technologies, Inc.
- 6.4.6 Panasonic Holdings Corporation
- 6.4.7 OLEDCOMM SAS
- 6.4.8 LVX System Corporation
- 6.4.9 Vibrint Inc.
- 6.4.10 SaNoor Technologies Inc.
- 6.4.11 Outstanding Technology Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 Li-Fi技術市場-全球及區域分析:按應用、組件和地區分類-分析與預測,2026-2035年
 Li-Fi市場規模、佔有率、趨勢和預測:按組件、應用、傳輸方式、最終用戶和地區分類,2026-2034年
 2026年全球光學相機通訊市場報告
 光照上網技術市場:按應用和地區分類
 Li-Fi全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)Li-Fi(光照上網)/可見光通訊全球市場報告(2026 年)
 光照上網技術(Li-Fi):市佔率分析、產業趨勢與統計、成長預測(2026-2031)
 光學保真市場-全球產業規模、佔有率、趨勢、機會及預測(按組件、最終用途、地區和競爭格局分類,2021-2031年)
 Li-Fi市場規模、佔有率和成長分析(按組件、應用、最終用戶、傳輸方式和地區分類)—產業預測(2026-2033年)
 全球Li-Fi市場(至2035年):依組件、硬體、傳輸方式、應用、公司規模、商業模式、最終用戶和地區劃分