


 |
市場調查報告書
商品編碼
2123410
穿戴式機器人和外骨骼:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Wearable Robots And Exoskeletons - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
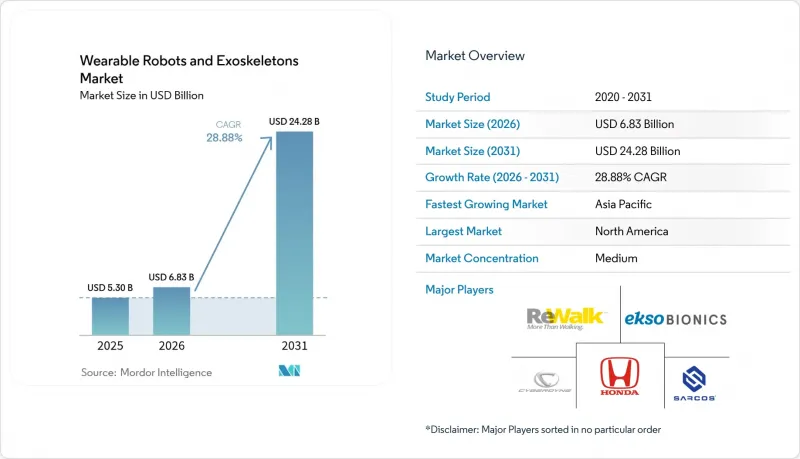
根據 Mordor Intelligence 預測,穿戴式機器人和外骨骼市場將從 2025 年的 53 億美元成長到 2026 年的 68.3 億美元,然後在 2031 年達到 242.8 億美元,2026 年至 2031 年的複合年成長率為 28.88%。
本報告按類型(動力型和被動型)、組件(硬體,包括感測器和執行器)、身體部位(下肢、上肢等)、最終用戶行業(醫療保健、工業和物流等)、移動方式(移動式或穿戴式式、固定式或有線式)以及地區進行細分。市場預測以價值(美元)表示。
全球穿戴式機器人和外骨骼市場趨勢及洞察
人口老化導致肌肉骨骼疾病快速增加
中風的發生率在55歲以後急劇上升,預計到2025年,老年人口將佔世界人口的16%。根據世界衛生組織(WHO)估計,由肌肉骨骼疾病導致的失能調整後存活年(DALYs)高達17.1億年。電動步行訓練設備透過提供可調式扭矩,能夠實現比手動方法更高強度的復健。在日本,2024年4月起實施的輔助機器人租賃費用保險政策加速了混合輔助肢體(HALs)在護理機構的應用。同時,美國醫療保險和醫療補助服務中心(CMS)為家用處方箋創建了新的代碼E1399。臨床試驗表明,經過12週的HAL治療後,患者的步行速度提高了23%。這些趨勢凸顯了醫療產業為何仍是穿戴式機器人和外骨骼的核心市場。
執行器和電池成本快速降低
隨著中國工廠大規模生產不含稀土元素的轉子,2022年至2024年間,無刷直流馬達的價格下降了18%,用於高放電率穿戴裝置的鋰離子電池組價格也降至每千瓦時137美元。德國仿生公司為其4.8公斤重的Apogee ULTRA配備了1.2千瓦時的電池組,實現了12小時的運作,並在一個季度內簽訂了300份租賃合約。派克漢尼芬公司的緊湊型電液執行器可提供150牛頓米的扭矩,而重量僅為同類氣動產品的三分之一。這些變化正在降低零件成本,使穿戴式矯正器具和外骨骼的成本更接近被動式義肢。
高昂的初始部署成本和生命週期維修成本
工業級設備的售價在 4 萬至 8 萬美元之間,而醫療系統,即使是家用設備,售價也高達 7.7 萬美元。包括電池和執行器更換在內的年度維護成本可能達到初始投資的 20%。德國仿生公司每月 250 歐元的租賃費,相當於每年 3,396 美元,對利潤率低的公司來說是一筆不小的負擔。每兩年更換一次電池需要花費 2500 至 4000 美元,而執行器大修則需要 5000 至 8000 美元。這些經濟因素限制了價格敏感地區的普及,也限制了穿戴式機器人和外骨骼產業的短期成長潛力。
細分市場分析
到2025年,動力型設計將佔銷售額的66.85%,預計到2031年將以31.2%的複合年成長率成長,凸顯了其在醫療、國防和重型運輸領域的高需求。受執行器價格下降和訂閱模式(可平滑資本支出)的推動,動力型產品驅動的穿戴式機器人和外骨骼市場規模預計到2031年將達到近162億美元。德國仿生公司的租賃計畫可將擁有成本降低40%,而洛克希德·馬丁公司ONYX的現場數據顯示,其耐用性實現了兩位數的提升,這對軍工領域的買家至關重要。
到2025年,被動式解決方案將佔據33.15%的市場佔有率,建築、農業和維護業對耐用、無電池設備的需求強勁。 SuitX的「IX BACK VOLTON」將被動式腰部支撐與可選的電動模式相結合,融合了多種設計,滿足了那些既追求柔軟性又不願犧牲正常運作的用戶的需求。雖然在充電基礎設施有限的地區,被動式外骨骼的需求仍然旺盛,但由於扭矩性能的預期提升,電動系統預計將在全球穿戴式機器人和外骨骼市場繼續擴大其市場佔有率。
2025年,硬體收入佔總收入的73.05%,但由於感測器和馬達價格下降,產品同質化導致利潤率下降。感測器佔組件成本的15%,而執行器仍佔最大佔有率,達45%,儘管其重量和功耗的降低正在取得進展。電池創新也即將到來,預計2027年,固態電池原型將使能量密度提高50%。軟體收入正以32.05%的複合年成長率成長,目前車隊管理儀錶板正在支撐持續的收入模式。
Fourier Intelligence 的設備內建人工智慧可即時調節扭矩,從而減輕疲勞,使該公司在醫院競標中脫穎而出。因此,隨著數據分析和遠距離診斷成為所有合約的標配,該公司在穿戴式機器人和外骨骼市場的軟體佔有率將會擴大。
區域分析
到2025年,北美將佔全球銷售額的39.85%,位居榜首。美國食品藥物管理局(FDA)的510(k)計畫簡化了醫療設備的核准流程,而美國陸軍在2025會計年度投入的1,280萬美元研發與測試(RDT&E)資金累計了其長期承諾。此外,美國退伍軍人事務部(VA)的政策調整取消了監管義務,擴大了退伍軍人的使用範圍。加拿大卑詩省工作安全局(WorkSafeBC)補貼了50%的採購成本,儘管缺乏培訓,被動式設備仍在墨西哥的汽車工業帶進行試點。這些因素使得北美能夠在穿戴式機器人和外骨骼市場排名中保持領先地位。
亞太地區是成長最快的市場,複合年成長率高達32.1%。在日本,長期照護保險的保障範圍已擴大至輔助機器人的租賃費用。傅立葉智慧公司計畫在2024年底在中國醫院部署120套外骨骼。在韓國,隨著工廠自動化和職業安全法規的完善,現代汽車計劃在2026年部署1000套「X-ble Shoulder」外骨骼。印度和澳洲目前仍處於起步階段,但新的資金籌措和試點計畫為它們帶來了可觀的未來前景。該地區的人口結構變化以及保險報銷制度的改革是穿戴式機器人和外骨骼市場發展的關鍵驅動力。
預計到2025年,歐洲將佔全球銷售額的約24.95%。奧托博克(Ottobock)和Wondercraft等現有公司正受益於醫療設備法規(MDR)將核准週期延長至24個月。德國勞工保險基金為高風險職業的醫護人員報銷80%的設備費用。英國國家醫療服務體系(NHS)的初步試驗表明,與傳統復健方式相比,治療時間縮短了30%,這進一步促進了穿戴式機器人和外骨骼的普及。儘管監管瓶頸在短期內會減緩市場擴張,但人們對工人安全的日益重視正在支撐穿戴式機器人和外骨骼市場的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人口老化導致肌肉骨骼疾病快速增加
- 輕型致動器和電池組成本的快速下降。
- 重工業減少工作場所事故的強制性目標
- 用於軍事增強技術的國防預算已達歷史新高。
- 核准居家神經復健的保險福利。
- 面向外骨骼機器人群集的新型「租賃即服務」模式
- 市場限制因素
- 高昂的初始實施成本和生命週期維修成本
- 跨越多個司法管轄區的長期醫療設備認證程序
- 全班次工業應用中扭矩重量比的局限性
- 設備易用性和過熱問題阻礙了使用者接受度。
- 產業價值鏈分析
- 宏觀經濟因素的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 動力外骨骼
- 被動式外骨骼
- 按組件
- 硬體
- 感應器
- 執行器
- 電源
- 軟體
- 服務
- 硬體
- 按身體部位
- 下肢
- 上肢
- 全身
- 按最終用戶行業分類
- 衛生保健
- 工業與物流
- 軍事/國防
- 其他終端用戶產業(公共安全、一般消費者)
- 依行程類型
- 行動/穿戴裝置
- 固定式/有線式
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cyberdyne Inc.
- ReWalk Robotics Ltd.
- Ekso Bionics Holdings Inc.
- Sarcos Technology and Robotics Corporation
- Honda Motor Co., Ltd.
- Myomo Inc.
- Ottobock SE and Co. KGaA
- SuitX Inc.(Ottobock Group)
- Parker Hannifin Corporation
- Bionik Laboratories Corp.
- Wandercraft SAS
- Fourier Intelligence Co., Ltd.
- Skelex BV
- Wearable Robotics Srl
- Daiya Industry Co., Ltd.
- Panasonic Holdings Corporation
- Lockheed Martin Corporation
- Hyundai Motor Company
第7章 市場機會與未來展望
According to Mordor Intelligence, the wearable robots and exoskeletons market size is expected to grow from USD 5.30 billion in 2025 to USD 6.83 billion in 2026 and is forecast to reach USD 24.28 billion by 2031 at 28.88% CAGR over 2026-2031.
This report is Segmented by Type (Powered, and Passive), Component (Hardware Including Sensors, Actuators, and More), Body Part Assisted (Lower Extremity, Upper Extremity, and More), End-User Industry (Healthcare, Industrial and Logistics, and More), Mobility Type (Mobile or Wearable, and Stationary or Tethered), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Wearable Robots And Exoskeletons Market Trends and Insights
Aging-Population Surge in Musculoskeletal Disorders
Stroke prevalence climbs sharply after age 55, and older adults already represent 16% of the world population in 2025. The World Health Organization estimates 1.71 billion disability-adjusted life years from musculoskeletal conditions. Powered gait trainers provide adjustable torque that enables higher-intensity therapy than manual techniques. Japan's reimbursement for assistive-robot rentals, effective April 2024, accelerated Hybrid Assistive Limb adoption in nursing homes, while the U.S. Centers for Medicare and Medicaid Services opened code E1399 for home-use prescriptions. Clinical trials showed a 23% bump in walking speed after 12-week HAL therapy cycles. These signals demonstrate why healthcare remains the anchor of the wearable robots and exoskeletons market.
Rapid Cost Declines in Actuators and Batteries
Brushless DC motor prices slid 18% between 2022 and 2024 as Chinese plants scaled rare-earth-free rotors, and lithium-ion packs for high-discharge wearables fell to USD 137 per kWh. German Bionic embedded a 1.2 kWh pack in the 4.8 kg Apogee ULTRA, securing 12-hour runtime and 300 rental subscriptions within one quarter. Parker Hannifin's compact electro-hydraulic actuator now delivers 150 Nm at one-third the weight of pneumatic peers . These shifts lower the bill of materials, propelling the wearable robots and exoskeletons market toward cost-parity with passive braces.
High Upfront Acquisition and Lifecycle Maintenance Costs
Industrial units list at USD 40,000-80,000, while healthcare systems face USD 77,000 price tags for home-use devices. Annual maintenance adds up to 20% of initial spend, driven by battery and actuator replacements. German Bionic's EUR 250 monthly rental still equates to USD 3,396 per year, straining thin-margin firms . Battery swaps every two years cost USD 2,500-4,000; actuator overhauls run USD 5,000-8,000. These economics temper adoption in price-sensitive regions, limiting the near-term upside of the wearable robots and exoskeletons industry.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory Workplace-Injury Reduction Targets
- Record Defense Budgets for Soldier Augmentation
- Lengthy Multi-Jurisdictional Certification
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Powered designs captured 66.85% of 2025 revenue and are forecast to expand at 31.2% CAGR through 2031, underscoring their pull across healthcare, defense, and heavy-lifting tasks. The wearable robots and exoskeletons market size attributed to powered units is projected to near USD 16.2 billion by 2031, driven by falling actuator prices and subscription models that smooth capital outlays. German Bionic's rental plan reduces ownership costs 40%, while Lockheed Martin's ONYX field data signal double-digit endurance gains that military buyers value.
Passive solutions held 33.15% share in 2025, steady demand for rugged, battery-free rigs in construction, agriculture, and maintenance. SuitX's IX BACK VOLTON blends passive lumbar support with an optional powered mode, illustrating design convergence as buyers seek flexibility without compromising uptime. Passive exoskeletons remain attractive where charging infrastructure is scarce, yet incremental torque benefits mean powered systems will keep widening their reach across the global wearable robots and exoskeletons market.
Hardware delivered 73.05% of 2025 revenue, but commoditization is eroding margins as sensor and motor prices fall. Sensors accounted for 15% of bill-of-materials cost, while actuators still dominate at 45% but are shedding weight and energy draw. Battery innovation looms; solid-state prototypes promise 50% density gains by 2027. Software revenue is pacing at 32.05% CAGR, and fleet dashboards now underpin recurring-revenue bundles.
Fourier Intelligence's on-device AI tweaks torque in real time, reducing fatigue and differentiating bids in hospital tenders. As a result, software's slice of the wearable robots and exoskeletons market share will widen as data analytics and remote diagnostics cement themselves in every contract.
Complete Report Scope:
- By Type
- Powered Exoskeletons
- Passive Exoskeletons
- By Component
- Hardware
- Sensors
- Actuators
- Power Sources
- Software
- Services
- Hardware
- By Body Part Assisted
- Lower Extremity
- Upper Extremity
- Full Body
- By End-user Industry
- Healthcare
- Industrial and Logistics
- Military and Defense
- Other End-user Industrys (Public Safety, Consumer)
- By Mobility Type
- Mobile / Wearable
- Stationary / Tethered
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led with 39.85% revenue in 2025. FDA 510(k) streamlines medical clearances, while USD 12.8 million in FY 2025 Army RDT&E exoskeleton funding signals long-run commitment. VA policy changes removed supervision mandates, boosting veteran access. Canada's WorkSafeBC offers 50% purchase subsidies, and Mexico's automotive belt is piloting passive rigs despite training gaps. These factors keep North America atop the wearable robots and exoskeletons market rankings.
Asia Pacific is the fastest climber at 32.1% CAGR. Japan expanded long-term care insurance to cover assistive-robot rentals. Fourier Intelligence installed 120 exoskeletons in Chinese hospitals by late-2024. Hyundai plans 1,000 X-ble Shoulder units by 2026 as South Korea aligns factory automation with labor-safety mandates. India and Australia are early-stage yet promising due to new funding lines and pilot trials. The region's demographic urgency and reimbursement reforms make it the pivotal growth engine for the wearable robots and exoskeletons market.
Europe held roughly 24.95% of 2025 revenue. MDR lengthens approval cycles to 24 months, benefiting incumbents such as Ottobock and Wandercraft. Germany's accident-insurance funds reimburse 80% of device costs for high-risk trades. The U.K. National Health Service pilot shows a 30% reduction in therapy hours versus conventional rehab, aiding adoption. Regulatory bottlenecks moderate short-term expansion, yet strong worker-safety cultures sustain demand across the wearable robots and exoskeletons market.
- Cyberdyne Inc.
- ReWalk Robotics Ltd.
- Ekso Bionics Holdings Inc.
- Sarcos Technology and Robotics Corporation
- Honda Motor Co., Ltd.
- Myomo Inc.
- Ottobock SE and Co. KGaA
- SuitX Inc. (Ottobock Group)
- Parker Hannifin Corporation
- Bionik Laboratories Corp.
- Wandercraft SAS
- Fourier Intelligence Co., Ltd.
- Skelex B.V.
- Wearable Robotics S.r.l.
- Daiya Industry Co., Ltd.
- Panasonic Holdings Corporation
- Lockheed Martin Corporation
- Hyundai Motor Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ageing-population led surge in musculoskeletal disorders
- 4.2.2 Rapid cost declines in lightweight actuators and battery packs
- 4.2.3 Mandatory workplace-injury reduction targets in heavy industry
- 4.2.4 Record defence budgets earmarked for soldier-augmentation tech
- 4.2.5 Insurance-reimbursement approvals for in-home neuro-rehab
- 4.2.6 Emerging lease-as-a-service models for exoskeleton fleets
- 4.3 Market Restraints
- 4.3.1 High upfront acquisition and lifecycle maintenance costs
- 4.3.2 Lengthy multi-jurisdictional medical-device certification
- 4.3.3 Limited torque-to-weight ratios for full-shift industrial use
- 4.3.4 User-acceptance barriers due to device discomfort and heat
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type
- 5.1.1 Powered Exoskeletons
- 5.1.2 Passive Exoskeletons
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.1.1 Sensors
- 5.2.1.2 Actuators
- 5.2.1.3 Power Sources
- 5.2.2 Software
- 5.2.3 Services
- 5.2.1 Hardware
- 5.3 By Body Part Assisted
- 5.3.1 Lower Extremity
- 5.3.2 Upper Extremity
- 5.3.3 Full Body
- 5.4 By End-user Industry
- 5.4.1 Healthcare
- 5.4.2 Industrial and Logistics
- 5.4.3 Military and Defense
- 5.4.4 Other End-user Industrys (Public Safety, Consumer)
- 5.5 By Mobility Type
- 5.5.1 Mobile / Wearable
- 5.5.2 Stationary / Tethered
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cyberdyne Inc.
- 6.4.2 ReWalk Robotics Ltd.
- 6.4.3 Ekso Bionics Holdings Inc.
- 6.4.4 Sarcos Technology and Robotics Corporation
- 6.4.5 Honda Motor Co., Ltd.
- 6.4.6 Myomo Inc.
- 6.4.7 Ottobock SE and Co. KGaA
- 6.4.8 SuitX Inc. (Ottobock Group)
- 6.4.9 Parker Hannifin Corporation
- 6.4.10 Bionik Laboratories Corp.
- 6.4.11 Wandercraft SAS
- 6.4.12 Fourier Intelligence Co., Ltd.
- 6.4.13 Skelex B.V.
- 6.4.14 Wearable Robotics S.r.l.
- 6.4.15 Daiya Industry Co., Ltd.
- 6.4.16 Panasonic Holdings Corporation
- 6.4.17 Lockheed Martin Corporation
- 6.4.18 Hyundai Motor Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need assessment


