


 |
市場調查報告書
商品編碼
2124135
鋁罐:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Aluminum Cans - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,全球鋁罐市場預計到 2026 年價值 581.3 億美元,高於 2025 年的 558.9 億美元,預計到 2031 年將達到 707.2 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.01%。
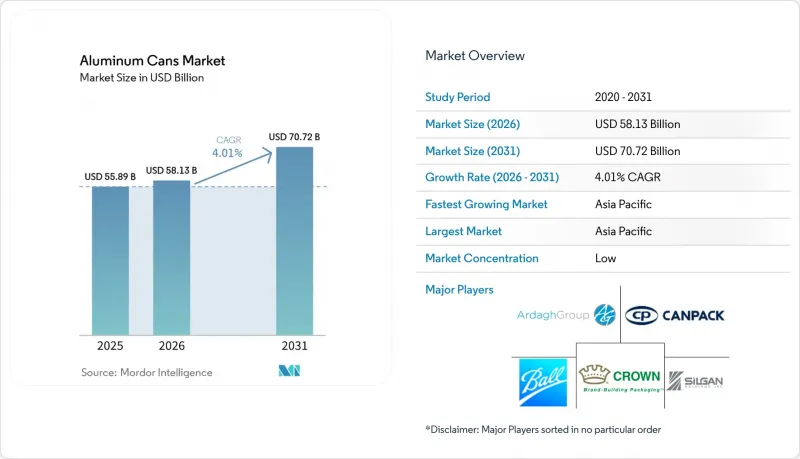
本報告按類型(標準型、時尚型、纖薄型等)、終端用戶行業(飲料[酒精飲料、非酒精飲料]、食品[罐頭食品、寵物食品]、氣霧劑等)、結構(兩件式、三件式)、容量(250毫升以下、251-500毫升、500毫升以上)及細分地區(北美、美國以上)及細分地區。市場預測以美元計價。
全球鋁罐市場趨勢與洞察
高可回收性和閉合迴路收集系統
由於鋁的冶金性能幾乎可以無限期地保持不變,因此它能夠實現塑膠或玻璃無法實現的真正材料回收。據美國罐頭製造商協會(Can Manufacturers Institute)稱,迄今為止生產的鋁中仍有75%在使用,而且再生鋁的重熔比原生提煉所需的能源少95%。歐洲冶煉廠康斯坦鋁業(Constellium)、埃爾瓦爾(Elval)、諾貝麗斯(Novelis)和斯佩拉(Speira)於2024年4月統一了合金規格,因此能夠生產高達100%再生材料含量的飲料罐。這每噸金屬可減少2.6噸二氧化碳排放,並降低致力於實現科學氣候目標的填充廠的營運成本。儘管美國的回收率在2023年下降至43%,但業界支持的投資旨在到2030年將回收率提高到70%,到2050年提高到90%,從而確保罐頭製造商長期穩定的原料供應。在歐洲、加拿大和美國部分州,已實施了每年涵蓋超過400億個容器的押金返還計劃,顯著提高了廢棄物的回收量。因此,廢料溢價降低,擁有整合生產系統的罐體製造商的利潤率也得到提升。這些結構性優勢共同推動了預計複合年成長率(CAGR)提高1.2個百分點,鞏固了鋁作為飲料包裝領域首選循環材料的地位。
從PET/玻璃到鋁的轉變是由強制實施生產者責任延伸制度和塑膠稅所推動的。
生產者延伸責任制(EPR)從根本上重新定義了原料成本的優先順序。英國2025年的EPR基準費率設定為每噸鋁266英鎊,遠低於PET、多層包裝袋或難以回收的軟包裝所徵收的附加稅。 2024年1月,加州將容器回收價值計畫擴展至葡萄酒和烈酒,使符合資格的飲料罐市場規模立即每年增加4億個。同時,歐盟法規要求在2029年一次性飲料容器的回收率達到90%,這項標準對鋁材極為有利,因為鋁材使用後的回收價值很高。在澳大利亞,到2040年食品級鋁材的再生材料含量要求達到80%,這將進一步增強整個環太平洋全部區域的需求前景。這些政策的綜效正在提升鋁材的吸引力,導致中期成長預測值進一步上調1.5個百分點。
與軟性PET和紙盒包裝形式的競爭
多層紙盒和輕量寶特瓶繼續主導價格敏感型細分市場,尤其是自有品牌果汁、乳類飲料和常溫水。在這些領域,品牌所有者優先考慮單位成本而非可回收性。新型乙二醇改質技術正在延長PET在碳酸飲料和含有敏感營養成分的產品中的保存期限,從而削弱鋁的功能優勢。在新興市場,消費者仍不願意為永續性支付溢價,這阻礙了其在商品化品類中的應用。然而,歐盟和加拿大計畫禁止使用不可回收塑膠容器,加上日益難以實現的生產者責任延伸制度(EPR)基準值,將逐步削弱軟包裝的競爭優勢。因此,預計2025年至2027年間,鋁罐市場將出現0.8%的暫時性負複合年成長率。
細分市場分析
到2025年,標準330毫升和355毫升罐裝飲料的銷量比將達到55.38%。這一佔有率得益於其與填充線的兼容性、極高的生產線速度以及最佳的托盤密度。此外,該品類在終端用戶中的廣泛普及也是一大優勢,降低了全球裝瓶商的轉換成本。然而,纖細型罐裝飲料(例如250毫升和310毫升規格)正以4.06%的複合年成長率快速擴張市場佔有率,這主要歸功於其更佳的視覺效果以及在擁擠的零售陳列架上更顯著的「廣告牌效應」。機能飲料、低卡路里飲料和即飲酒精飲料領域的飲料開發商高度重視纖細型罐裝飲料,認為其能夠提升貨架展示效果和冷藏櫃中的可見度。 Ball公司的Dynamark可變圖形平台使負責人能夠在不中斷生產線的情況下,為標準罐和纖細型罐設計限量版圖案,從而降低庫存風險並提高宣傳活動的靈活性。隨著印刷技術的進步和單位成本的降低,纖細罐有望在利潤率較高的SKU中獲得更大的市場佔有率。特殊形狀和觸感壓紋等技術雖然仍在發展中,但體現了持續的創新,進一步豐富了消費者的體驗。總體而言,鋁罐市場預計將繼續呈現標準量產規格和纖細高階規格並存的局面,其中後者預計相對於產能而言將帶來更高的收入成長。
標準形狀的易拉罐仍具有卓越的物流經濟優勢。一箱24罐355毫升的易拉罐比同等容量的玻璃容器輕20%,這不僅減少了運輸過程中的排放氣體,也降低了零售商在將易拉罐上架時造成人員受傷的風險。自1990年代以來採用的更厚的金屬板材,即使在金屬價格飆升的情況下,也能確保加工商獲得穩定的利潤。然而,品牌所有者願意為纖細易拉罐承擔略微增加的成本,因為纖細易拉罐的目標市場是「生活方式」市場,在這個市場中,視覺上的新穎性和健康意識比每盎司的價值更為重要。預計到2030年,纖細易拉罐的市佔率將達到兩位數,在保持與現有生產線設備向下相容的同時,豐富了包裝產品組合。因此,產品類型的多樣化增強了整個鋁罐市場的韌性,並有助於希望進入細分飲料市場的裝瓶商降低轉換成本。
到2025年,飲料將佔全球銷售額的48.35%,這反映了碳酸飲料與輕質金屬容器之間長達一個世紀的共生關係。碳酸飲料、能量飲料和運動補水產品仍然是關鍵產品,為鋁罐軋延廠帶來了規模經濟效益。酒精蘇打水、CBD滋補品和氮氣咖啡等新產品以兩位數的成長率不斷湧現,進一步拓寬了飲料品類,即使在主流碳酸飲料銷量下降的淡季,鋁罐生產線也能接近滿負荷運作。同時,從除臭劑到烹飪噴霧等氣霧劑產品預計將以5.21%的複合年成長率成長,成為鋁罐市場成長最快的細分市場。品牌擁有者非常重視鋁罐在含有油、推進劑或酒精的配方中的耐腐蝕性,因為這些成分會劣化其他類型的馬口鐵罐。牆面熨燙工藝的改進使其能夠承受高達 18 巴的壓力,從而可以將該技術應用於慕斯、油漆和鮮奶油等產品。
儘管寵物食品和罐裝人類食品的市場佔有率較小,但在存貨周轉和緊急儲備的支撐下,預計全年需求將保持穩定。 Sigan Holdings 2024 年寵物食品罐頭銷售額實現了兩位數成長,這表明高品質寵物食品與金屬的氧氣阻隔性能具有良好的兼容性。醫藥和營養補充品應用代表著一個新的成長領域,充分利用了小容量管瓶的防竄改和精確定量分裝功能。整體而言,終端用戶的多角化提供了多個成長點,不僅能進一步保護鋁罐市場免受單一品類低迷的影響,還能分散生產成本並加速資產回收。
區域分析
亞太地區佔全球鋁罐銷售額的40.74%,預計到2031年,該地區鋁罐市場將以5.52%的年均成長率成長。推動這一成長的因素包括中產階級可支配收入的增加、都市區便利消費觀念的盛行,以及中國、印度和日本政府對一次性塑膠製品的監管。中國憑藉國內軋延能力和蓬勃發展的國內飲料產業,保持領先地位,這兩大優勢使其對進口的依賴程度大大降低。印度鋁業公司(Hindalco)斥資100億美元擴張,旨在擴大印度國內金屬供應,以期當地可樂、能量飲料和酒精飲料(預調酒)生產商採用鋁罐。日本成熟的飲料市場正在推動高階茶和精品咖啡罐的創新,朝日集團致力於實現淨零排放,並積極推動採購方式的變革。東南亞也正在經歷蓬勃發展,NS-Siam United Steel 投資 5,850 萬美元加強馬口鐵生產能力,並與海外罐板供應商合作,這表明鋼鐵和鋁供應鏈正在走一條混合發展道路。
北美是全球第二大鋁罐市場,但其出貨量已趨於穩定。該地區正致力於升級產品,採用更先進、更纖薄的設計以及利潤更高的特殊熱敏罐。 2023年,波爾公司出貨約490億個鋁罐,佔該地區鋁罐市佔率的36%。隨著回收系統的擴展,波爾公司在再生材料的使用方面取得了顯著進展。美國各州所推行的罐體押金制度,以及加拿大實施的生產者責任再利用(EPR)制度,都增強了再生廢棄物的供應。因此,罐體板材的再生材料含量達到了歷史新高,加工商的金屬採購成本也隨之降低。
儘管歐洲市場已趨於成熟,但仍高度依賴監管措施來加速從PET到鋁的過渡。隨著歐盟90%回收率目標的臨近,品牌所有者正透過簽訂多年合約來確保鋁罐供應,以穩定加工商的訂單訂單,並預付合規成本。英國即將實施的押金返還計畫將每年把140億個金屬容器整合到一個閉合迴路通路中,鞏固原料供應。德國和法國不僅在啤酒產業站穩腳跟,也積極推動葡萄酒罐的試點計畫。這些因素使得歐洲製造商能夠引入新的產能,提高生產線運作速度,並推進現場可再生能源的應用,從而確保歐盟鋁罐市場的價值(即使僅體現在銷售方面)必將成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 高可回收性和閉合迴路收集系統
- 隨著生產者延伸責任制 (EPR) 和塑膠稅的引入,塑膠製品正在從 PET 和玻璃轉向鋁。
- 即飲飲料、精釀飲料和機能飲料的蓬勃發展
- 罐裝葡萄酒和烈酒包裝的快速成長(未充分報告)
- 電子商務對耐衝擊初級包裝的需求(媒體報告不足)
- 市場限制因素
- 來自軟性PET和紙質容器的競爭
- 原生鋁價格和供應波動
- 各地區罐頭生產能力瓶頸(報告不足)
- 範圍 3 脫碳合規成本上升(瞞報)
- 產業供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 標準
- 光滑
- 苗條的
- 其他類型
- 按最終用戶行業分類
- 飲料
- 酒精飲料
- 不含酒精的飲料
- 食物
- 罐頭食品
- 寵物食品(濕糧和零食)
- 氣霧劑
- 其他終端用戶產業
- 飲料
- 按結構
- 2 件
- 3 件
- 按產能
- 250毫升或以下
- 251~500 ml
- 超過500毫升
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 馬來西亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Ball Corporation
- Crown Holdings Inc.
- Ardagh Group SA
- Silgan Holdings Inc.
- CAN-PACK SA
- Novelis Inc.
- ORG Technology Co. Ltd.
- Toyo Seikan Group Holdings Ltd.
- CPMC Holdings Limited
- Baosteel Packaging Co. Ltd.
- Envases Universales
- Tecnocap Group
- CCL Container Inc.
- Massilly Holding SAS
- Nampak Ltd.
- Saudi Arabia Packaging Industry(SAPIN)
- Can-One Berhad
- Alltub Deutschland GmbH
- Baofeng Group Co. Ltd.
- Trivium Packaging BV
第7章 市場機會與未來展望
According to Mordor Intelligence, the global aluminum cans market size in 2026 is estimated at USD 58.13 billion, growing from 2025 value of USD 55.89 billion with 2031 projections showing USD 70.72 billion, growing at 4.01% CAGR over 2026-2031.
This report is Segmented by Type (Standard, Sleek, Slim, and More), End-User Industry (Beverage [Alcoholic Beverages, and Non-Alcoholic Beverages], Food [Canned Food, and Pet Food], Aerosol, and More), Structure (2-Piece, and 3-Piece), Capacity (Up To 250 Ml, 251-500 Ml, and Above 500 Ml), and Geography (North America, Europe, Asia Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Aluminum Cans Market Trends and Insights
High Recyclability and Closed-Loop Recovery Systems
Aluminum retains its metallurgical properties indefinitely, enabling genuine material circularity that plastic and glass cannot match. The Can Manufacturers Institute notes that 75% of all aluminum ever produced remains in active use today, and remelting secondary aluminum consumes 95% less energy than primary smelting. European smelters Constellium, Elval, Novelis, and Speira harmonized alloy specifications in April 2024 to allow beverage cans with up to 100% recycled content, cutting carbon emissions by 2.6 tons of CO2 per ton of metal and lowering operating costs for fillers committed to science-based climate targets. U.S. recycling rates slipped to 43% in 2023, but industry-backed investments aim to lift recovery to 70% by 2030 and 90% by 2050, ensuring long-term feedstock security for can plants. Deposit return programs covering more than 40 billion containers annually in Europe, Canada, and select U.S. states materially raise collection volumes, translating into lower scrap premiums and stronger margins for integrated can makers. These structural advantages collectively add 1.2 percentage points to forecast CAGR, cementing aluminum's reputation as the definitive circular beverage package.
Shift from PET/Glass to Aluminum Amid EPR and Plastics-Tax Mandates
Extended Producer Responsibility schemes fundamentally reshape material cost hierarchies. The United Kingdom's 2025 base EPR fee is set at GBP 266 per tonne for aluminum, far below levies applied to PET, multilayer pouches, or difficult-to-recycle flexibles. California expanded its Container Redemption Value program to wine and spirits in January 2024, immediately widening the addressable beverage can universe by 400 million units a year. Meanwhile, EU rules compel 90% collection of single-use beverage containers by 2029, a benchmark that heavily favors aluminum due to its high post-consumer scrap value. Australia will require 80% recycled content in food-grade aluminum by 2040, again reinforcing demand visibility along the entire Pacific Rim. These converging policies collectively boost aluminum's attractiveness and inject an additional 1.5 percentage point lift into medium-term growth forecasts.
Competition from Flexible PET and Carton Formats
Multilayer cartons and lightweight PET bottles continue to dominate price-sensitive segments, especially for private-label juices, dairy drinks, and shelf-stable water, where brand owners prioritize unit cost over recyclability. New glycol-modification techniques have extended PET shelf life for carbonation and sensitive nutrient blends, narrowing aluminum's functional advantage. In developing economies, consumer willingness to pay sustainability premiums remains low, restraining penetration in commoditized categories. However, upcoming bans on non-recyclable plastic formats across the EU and Canada, alongside hard-to-reach EPR thresholds, will gradually erode the competitive edge of flexibles. Net effect is a temporary 0.8% drag on the aluminum cans market CAGR from 2025-2027.
Other drivers and restraints analyzed in the detailed report include:
- Boom in RTD, Craft, and Functional Beverages
- Rapid Growth of Can-Friendly Wine and Spirits Packaging
- Price and Supply Volatility of Primary Aluminum
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standard 330-mL and 355-mL bodies retained 55.38% of 2025 revenue, a share underpinned by filling-line compatibility, the highest line speeds, and optimal pallet density. The segment also capitalizes on broad end-user familiarity, which reduces changeover costs for global bottlers. Nevertheless, sleek cans, typified by 250-mL and 310-mL footprints, are advancing swiftly at a 4.06% CAGR thanks to their premium visual ratio and enhanced billboard effect in crowded retail aisles. Beverage formulators serving functional, low-calorie, and alcohol-ready-to-drink segments prize the elongated profile for differentiated shelf blocking and cold-box visibility. Ball's Dynamark variable-graphics platform lets marketers design limited-run art across both standard and sleek formats without line-stopovers, trimming inventory risk and fostering campaign agility. As printing technology lowers per-unit cost, sleek cans should secure incremental penetration in higher-margin SKUs. Specialty shapes and tactile embossing remain nascent but reflect ongoing innovation that further enriches consumer experience. Altogether, the aluminum cans market expects continued coexistence of standard mass-volume formats and sleek premium variants, with the latter responsible for outsized revenue gains relative to capacity installed.
Standard bodies still benefit from superior logistics economics: a 24-count case of 355-mL cans weighs 20% less than an equivalent glass pack, cutting freight emissions and reducing shelf-stack injuries for retailers. Their thicker gauge, tooled since the 1990s, affords converters a stable margin capture even at high metal premiums. Yet brand owners are willing to absorb a slight cost uplift for sleek cans targeting lifestyle positioning where visual disruption and perceived health cues trump per-ounce value. By 2030, sleek units are likely to reach double-digit market share, adding breadth to packaging portfolios while maintaining backward compatibility with legacy line equipment. As such, type diversification reinforces the broader aluminum cans market's resilience and keeps switching costs low for bottlers contemplating entry into niche beverage sub-categories.
Beverages claimed 48.35% of global revenues in 2025, mirroring a century-long symbiosis between carbonated drinks and lightweight metal containers. Carbonated soft drinks, energy shots, and sports hydration products remain workhorse volumes that secure economies of scale for can-sheet rolling mills. Sustained double-digit launches of spiked seltzers, CBD-infused tonics, and nitro-coffee further widen beverage category breadth, allowing can lines to run at near-full utilization even during off-season contractions for mainstream sodas. Meanwhile, aerosol fillings from deodorants to cooking sprays are forecast to post a 5.21% CAGR, marking them the fastest mover within the aluminum cans market. Brand owners appreciate aluminum's corrosion resistance for formulations containing oils, propellants, or alcohols that degrade tinplate alternatives. Enhanced wall ironing processes enable pressure ratings up to 18 bar, paving the way for mousse, paint, and whipped-cream formats as well.
Pet food and human canned foods hold a smaller slice but deliver stable year-round demand anchored in inventory rotation and emergency-stock purchasing behaviors. Silgan Holdings witnessed double-digit pet food can revenue growth in 2024, illustrating premium pet nutrition's alignment with metal's oxygen-barrier features. Pharmaceutical and nutraceutical applications occupy an emerging frontier, leveraging tamper-evidence and precise metering features of small-volume aluminum vials. Collectively, end-user diversification further insulates the aluminum cans market against single-category downturns while providing multiple growth vectors that absorb manufacturing overhead and accelerate asset payback.
Complete Report Scope:
- By Type
- Standard
- Sleek
- Slim
- Other Types
- By End-user Industry
- Beverage
- Alcoholic Beverages
- Non-alcoholic Beverages
- Food
- Canned Food
- Pet Food (Wet and Treats)
- Aerosol
- Other End-user Industries
- Beverage
- By Structure
- 2-piece
- 3-piece
- By Capacity
- Up to 250 ml
- 251 - 500 ml
- More than 500 ml
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia
- Malaysia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia Pacific contributes 40.74% of global sales, and its aluminum cans market size is projected to advance 5.52% annually to 2031, underwritten by rising middle-class disposable incomes, urban convenience culture, and authoritative restrictions on single-use plastics in China, India, and Japan. China retains pole position with in-house rolling capacity and a vibrant domestic beverage sector that collectively eclipses import dependence. Hindalco's USD 10 billion expansion amplifies India's domestic metal supply in anticipation of can adoption by local cola, energy drink, and alcopop producers. Japan's mature beverage environment spurs innovation in premium tea and craft coffee cans, aided by Asahi Group's net-zero pledges driving procurement switch-overs. Southeast Asia is equally dynamic; NS-Siam United Steel allocated USD 58.5 million to bolster tinplate output, yet concurrently partners with foreign can-sheet suppliers, signaling blended development paths for both ferrous and aluminum supply chains.
North America ranks second in absolute size, though its unit volumes plateau. Instead, the region focuses on trading up to sleek, slim, and specialty thermochromic cans that fetch higher margins. Ball shipped roughly 49 billion containers in 2023, representing 36% regional aluminum cans market share and delivering significant recycled content progress as reclamation systems scale. U.S. state-level container deposit expansions plus Canada's EPR rollouts strengthen secondary scrap supply, raising recycled content in can body sheet to record highs and lowering metal purchase costs for converters.
Europe, while mature, leans heavily on regulatory levers to accelerate modal shift from PET to aluminum. With the EU's 90% collection target looming, brand owners pre-pay for compliance by booking multi-year aluminum can supply contracts that stabilize converter order books. The United Kingdom's upcoming deposit return program will funnel 14 billion metal containers into closed-loop paths yearly, solidifying feedstock security. Germany and France aggressively promote wine-in-can pilots, expanding beyond beer's established foothold. These factors allow European producers to deploy new capacity while raising line speeds and integrating on-site renewable energy, ensuring that the aluminum cans market in the bloc grows in value even where volumes edge upward modestly.
- Ball Corporation
- Crown Holdings Inc.
- Ardagh Group S.A.
- Silgan Holdings Inc.
- CAN-PACK S.A.
- Novelis Inc.
- ORG Technology Co. Ltd.
- Toyo Seikan Group Holdings Ltd.
- CPMC Holdings Limited
- Baosteel Packaging Co. Ltd.
- Envases Universales
- Tecnocap Group
- CCL Container Inc.
- Massilly Holding S.A.S
- Nampak Ltd.
- Saudi Arabia Packaging Industry (SAPIN)
- Can-One Berhad
- Alltub Deutschland GmbH
- Baofeng Group Co. Ltd.
- Trivium Packaging B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High recyclability and closed-loop recovery systems
- 4.2.2 Shift from PET/glass to aluminum amid EPR and plastics-tax mandates
- 4.2.3 Boom in RTD, craft and functional beverages
- 4.2.4 Rapid growth of can-friendly wine and spirits packaging (under-reported)
- 4.2.5 E-commerce's need for dent-resistant primary packaging (under-reported)
- 4.3 Market Restraints
- 4.3.1 Competition from flexible PET and carton formats
- 4.3.2 Price and supply volatility of primary aluminum
- 4.3.3 Regional can-making capacity bottlenecks (under-reported)
- 4.3.4 Rising Scope-3 decarbonization compliance costs (under-reported)
- 4.4 Industry Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Standard
- 5.1.2 Sleek
- 5.1.3 Slim
- 5.1.4 Other Types
- 5.2 By End-user Industry
- 5.2.1 Beverage
- 5.2.1.1 Alcoholic Beverages
- 5.2.1.2 Non-alcoholic Beverages
- 5.2.2 Food
- 5.2.2.1 Canned Food
- 5.2.2.2 Pet Food (Wet and Treats)
- 5.2.3 Aerosol
- 5.2.4 Other End-user Industries
- 5.2.1 Beverage
- 5.3 By Structure
- 5.3.1 2-piece
- 5.3.2 3-piece
- 5.4 By Capacity
- 5.4.1 Up to 250 ml
- 5.4.2 251 - 500 ml
- 5.4.3 More than 500 ml
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Malaysia
- 5.5.4.7 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Ball Corporation
- 6.4.2 Crown Holdings Inc.
- 6.4.3 Ardagh Group S.A.
- 6.4.4 Silgan Holdings Inc.
- 6.4.5 CAN-PACK S.A.
- 6.4.6 Novelis Inc.
- 6.4.7 ORG Technology Co. Ltd.
- 6.4.8 Toyo Seikan Group Holdings Ltd.
- 6.4.9 CPMC Holdings Limited
- 6.4.10 Baosteel Packaging Co. Ltd.
- 6.4.11 Envases Universales
- 6.4.12 Tecnocap Group
- 6.4.13 CCL Container Inc.
- 6.4.14 Massilly Holding S.A.S
- 6.4.15 Nampak Ltd.
- 6.4.16 Saudi Arabia Packaging Industry (SAPIN)
- 6.4.17 Can-One Berhad
- 6.4.18 Alltub Deutschland GmbH
- 6.4.19 Baofeng Group Co. Ltd.
- 6.4.20 Trivium Packaging B.V.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 2026-2030年全球鋁罐市場
 鋁罐市場報告:趨勢、預測和競爭分析(至2035年)
 全球鋁罐市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 鋁罐市場商機、成長要素、產業趨勢分析及2026-2035年預測。
 鋁罐市場:依產品類型、類型、最終用途產業及地區分類杯架市場:按產品類型、材料、最終用戶、分銷管道和地區分類。
 鋁罐市場報告:按應用和地區分類 2026-2034 年日本鋁罐市場:規模、佔有率、趨勢和預測:按應用、地區分類,2026-2034年
 罐裝飲料支架市場:按支架類型、容量、材料、最終用途和分銷管道分類,全球預測(2026-2032年)
 鋁罐市場規模、佔有率及成長分析(按產品類型、銷售、最終用途及地區分類)-2026-2033年產業預測