


 |
市場調查報告書
商品編碼
2124917
汽車共享遠端資訊處理:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Car Sharing Telematics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
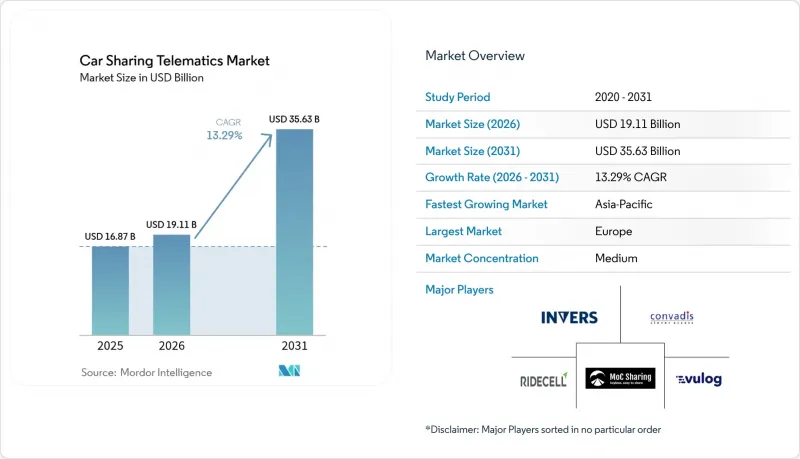
據 Mordor Intelligence 稱,汽車共享遠端資訊處理市場預計到 2026 年價值 191.1 億美元,高於 2025 年的 168.7 億美元,預計到 2031 年將達到 356.3 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 13.29%。
本報告按通路(原始設備製造商 (OEM)、售後市場)、外形尺寸(嵌入式、有線、整合式)、汽車共享模式(往返/站點類型、企業/車隊、點對點 (P2P)、其他)、車輛動力(內燃機 (ICE)、電池式電動車(BEV)、混合動力汽車(HEV/PHEV))和地區進行分類。
全球汽車共享遠端資訊處理市場趨勢及洞察
都市區對共享出行的興趣日益濃厚
隨著城市擁塞加劇和擁塞收費系統的擴展,通勤經濟模式正向共享汽車轉變,市政負責人正在重新分配路肩空間,用於建造整合汽車共享、微出行和公共交通的多模態樞紐。自由浮動業者利用即時熱力圖遙測技術,將車輛重新部署到需求高峰區域,從而減少乘客等待時間和車輛閒置時間。在慕尼黑和柏林,高使用率區域與人口密度高且接近性地鐵轉換站的區域相吻合,這證實了地點分析是盈利的核心因素。動態定價引擎透過學習天氣資料和活動日曆,最佳化車輛分配,同時降低每次行程的排放量。這些城市網路效應凸顯了投資者為何持續支持那些能夠將交通和環境外部性內部化的汽車共享遠端資訊處理市場平台。
政府關於車輛遠端資訊處理(緊急呼叫、安全)的法規
監管機構正透過立法強制推行車載資訊技術,加速其普及。根據歐盟《一般安全條例II》,自2024年7月起,所有新購入的M1和N1類車輛都必須配備智慧速度輔助系統、自動緊急煞車系統和事件資料記錄器。隨著緊急呼叫基礎設施從2G/3G升級到4G/5G,下一代eCall系統將需要對整個共享汽車車隊進行硬體升級。俄羅斯和巴西正在引入類似的框架,美國聯邦通訊委員會(FCC)也在考慮制定類似的法規。這將為能夠跨多個地區實現合規標準化的供應商帶來規模經濟效益。升級到支援NG-eCall系統的車輛將提供更豐富的事故資料集,營運商可以透過安全駕駛計劃和更精確的保險費計算從中獲利。
高昂的硬體和安裝成本
由於半導體供應受限以及感測器數量的不斷增加,預計到2030年,每輛車的半導體成本將達到1,200美元,是2022年的兩倍。印度國家轉型委員會(NITI Aayog)對零件成本的追蹤也凸顯了這一趨勢。將車輛無線通訊從4G升級到5G會推高模組價格,但在低延遲應用普及之前,投資回報將十分有限。因此,小規模業者要么推遲升級週期,要么探索將資本支出分攤到合約期間的訂閱模式。原始設備製造商(OEM)與一級供應商(Tier 1 Supplier)之間的策略夥伴關係正在興起,例如Geotab與大眾汽車集團,以及Samsara與Stellantis,這些合作關係能夠帶來採購折扣和聯合研發,同時確保合規性更新透過空中下載(OTA)而非成本高昂的服務宣傳活動進行推送。
細分市場分析
到2025年,售後改裝將佔據市場主導地位,銷量佔比高達57.42%,這主要得益於龐大的現有車輛數量。然而,OEM嵌入式單元正以14.92%的複合年成長率快速成長,這主要得益於工廠為遵守eCall等法規以及加強網路安全措施而採取的措施。汽車製造商目前正在發布汽車API,提供有關電池、ADAS和空調系統的詳細數據,為營運商提供更多工具來提高車隊的運轉率。 Geotab與大眾集團儀錶板的直接連接等合作,標誌著產業正朝著生態系統策略轉型,該策略將硬體、軟體和可現場更新的韌體到單一的生命週期堆疊中。
隨著純電動車(BEV)的普及,汽車共享遠端資訊處理市場在整車廠商(OEM)整合部署方面預計將快速成長。這是因為電池診斷需要直接存取驅動系統,而這無法透過售後市場的適配器可靠地實現。售後市場供應商繼續服務於混合燃料車隊和平均車齡超過八年的新興市場,預計這種雙軌化的通路結構在中期內將持續存在。
隨著半導體價格上漲,嵌入式解決方案和售後解決方案之間的成本差距正在縮小,而無線配置技術則降低了工廠安裝設備所需的人工成本。大規模業者正透過結合這兩種策略來規避風險。新購買的車輛配備了嵌入式車載資訊系統,而現有的汽油和混合動力汽車則使用經過認證的第三方設備並整合詳細的資料饋送。這種混合模式使企業能夠避免對單一供應商的依賴風險,並在不佔用大量資金的情況下縮短更新週期。這些做法正在重塑整個汽車共享車載資訊系統市場的採購策略。
到2025年,嵌入式模組將佔總收入的45.48%,但包含4G/5G數據機、邊緣人工智慧和安全引導載入程式的完全整合連接平台預計將以16.65%的複合年成長率成長。這些設備整合了先前需要單獨設備才能實現的功能,從而減少了線束並提高了計算吞吐量。整合架構提供開放的API,使開發人員能夠基於相同遙測骨幹網路建立出行即服務(MaaS)收費引擎、預測性維護儀表板和碳足跡運算工具。依賴智慧型手機配對的有線解決方案正在逐漸被淘汰,因為車隊營運商優先考慮始終線上鎖定/解鎖、防盜器和遠端停用命令的運作功能。隨著5G網路在大都會圈的覆蓋範圍擴大,並支援諸如遠端駕駛和遠端代客泊車服務等對延遲敏感的應用,預計到2027年,採用整合部署的汽車共享遠端資訊處理市場收入將超過有線解決方案。
邊緣容器化使多個虛擬化應用程式能夠在單一車載資訊系統控制單元內安全共存,從而打造面向未來的車隊環境,並能適應不斷發展的標準。標準化有助於跨原始設備製造商 (OEM) 的資料融合,簡化多品牌車隊運營,並降低軟體整合帶來的額外開銷。因此,整合解決方案擴大支持 RFP(徵求提案)標準,這不僅對新參與企業有利,也對現有營運商有利,從而加速了其在汽車共享車載資訊系統市場的發展勢頭。
區域分析
歐洲憑藉36.62%的市場佔有率,繼續保持領先地位,這得益於成熟的法規,這些法規強制要求所有新車配備先進的安全和互聯功能。德國、法國和北歐國家等地的獎勵計劃為電動車共享車隊津貼,使電池式電動車(BEV)訂閱對營運商具有經濟吸引力。 ShareNow向東方的擴張體現了歐洲大陸內部的技術轉移,而雷諾在烏特勒支開展的V2G(車網互動)試點計畫則展示了將移動出行與電網融合的潛力。亞太地區正以14.33%的複合年成長率快速成長,這得益於各國快速的都市區進程和智慧城市預算。光是在中國當地,就有超過50個城市正在進行無人駕駛計程車試點項目,每個項目都需要將超低延遲連線整合到車隊遠端資訊處理系統中。該地區擁有18億行動用戶,這些用戶構成了即時車隊協調和空中下載(OTA)更新的連接基礎。東南亞各國政府也紛紛津貼基於遠端資訊處理的車輛管理系統的普及,為汽車共享遠端資訊處理市場創造了肥沃的土壤。在北美,發展勢頭並不均衡。雖然一些科技發達的大都會圈正在實施基於5G的遠端駕駛試點項目,但郊區的擴張卻減緩了車輛的更新換代速度。 Verizon Business與Vay在拉斯維加斯的合作凸顯了向遠端駕駛電動車發展的趨勢,這種電動車利用毫米波頻寬,同時降低了車輛重新部署所需的成本。然而,農村地區和城市郊區仍然依賴LTE和較舊的3G網路,這限制了服務擴展的經濟效益。在加拿大和美國,符合ISO/SAE 21434等聯邦標準的網路安全措施正變得越來越重要。雖然合規要求不斷提高,但同時也增強了消費者的信心,而消費者信心對於汽車共享遠端資訊處理市場的持續滲透至關重要。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 都市區對共享出行的興趣日益濃厚
- 政府關於車輛遠端資訊處理(緊急呼叫、安全)的法規
- 將物聯網、人工智慧和機器學習 (ML) 整合到車輛運行最佳化中
- 汽車共享車輛的快速電氣化
- 透過與合作夥伴開展基於里程的保險業務來降低營運成本 (OPEX)。
- 一個以 API 為先導的遠端資訊處理平台,能夠聚合出行即服務 (MaaS)。
- 市場限制因素
- 高昂的硬體和安裝成本
- 對資料隱私和網路安全的擔憂
- 缺乏遠端資訊處理互通性標準
- 郊區和農村地區的運轉率較低
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 投資和資金籌措趨勢
第5章 市場規模與成長預測
- 通道特異性
- 原始設備製造商 (OEM)
- 售後市場
- 按形式
- 嵌入式
- 有線型
- 融合的
- 汽車共享模式
- 往返/車站類型
- 自由浮動(單向使用)
- 點對點(P2P)
- 企業/車隊
- 車輛推進類型
- 內燃機(ICE)
- 電池式電動車(BEV)
- 混合動力汽車(HEV/PHEV)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 南美洲其他地區
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 亞太其他地區
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- INVERS GmbH
- Vulog
- Ridecell Inc.
- Convadis AG
- Continental Aftermarket and Services
- OCTO Group SpA
- Geotab Inc.
- Targa Telematics
- Fleetster
- OpenFleet
- Mobility Tech Green
- WeGo BV
- MoC Sharing
- Free2Move
- Miles Mobility
- Share Now
- Sixt share
- Getaround
- Zity
- Bolt Drive
第7章 市場機會與未來展望
According to Mordor Intelligence, car sharing telematics market size in 2026 is estimated at USD 19.11 billion, growing from 2025 value of USD 16.87 billion with 2031 projections showing USD 35.63 billion, growing at 13.29% CAGR over 2026-2031.
This report is Segmented by Channel (Original Equipment Manufacturer (OEM) and Aftermarket), Form (Embedded, Tethered, and Integrated), Car-Sharing Model (Round-Trip / Station-Based, Corporate / Fleet, Peer-To-Peer (P2P), and More), Vehicle Propulsion (Internal-Combustion Engine (ICE), Battery-Electric Vehicle (BEV), and Hybrid Electric Vehicle (HEV/PHEV)), and Geography.
Global Car Sharing Telematics Market Trends and Insights
Growing Urban Preference for Shared Mobility
Continued densification and escalating congestion-charging schemes are shifting commuter economics toward shared fleets, nudging municipal planners to re-allocate curb space for multimodal mobility hubs that integrate car sharing, micro-mobility, and public transit. Free-floating operators use real-time heat-map telemetry to reposition vehicles in zones of peak demand, cutting customer wait times and trimming fleet idle minutes. In Munich and Berlin, usage clusters align with demographic density and proximity to subway interchanges, confirming location analytics as a core profitability lever. Dynamic-pricing engines, trained on weather feeds and event calendars, optimize vehicle distribution while lowering per-ride emissions footprints. Such urban network effects underscore why investors continue to back car sharing telematics market platforms that internalize both transportation and environmental externalities.
Government Mandates for Vehicle Telematics (eCall, Safety)
Regulators are accelerating adoption by making telematics a legal obligation. Under the EU General Safety Regulation II, all new M1 and N1 vehicles must feature intelligent speed assistance, automatic emergency-braking, and event-data recorders from July 2024. Next-Generation eCall shifts the emergency-alert backbone from 2G/3G to 4G/5G, demanding hardware refreshes across car-sharing fleets.Comparable frameworks are rolling out in Russia and Brazil, and the FCC is reviewing a similar mandate, giving scale economies to vendors able to standardize multi-region compliance. Vehicles upgraded for NG-eCall deliver richer crash datasets that operators now monetize through safer-driving programs and refined insurance pricing.
High Hardware and Installation Costs
Silicon supply constraints and escalating sensor counts are pushing semiconductor content per vehicle toward USD 1,200 by 2030, doubling 2022 levels, a trend highlighted by NITI Aayog's component-cost tracking. Upgrading fleets from 4G to 5G radios elevates module prices yet delivers minimal payback until low-latency apps reach scale. Consequently, smaller operators defer refresh cycles or seek subscription models that spread capital outlay across contractual terms. Strategic OEM-tier-one alliances-Geotab with Volkswagen Group, Samsara with Stellantis-are emerging to unlock purchase discounts and shared R&D while ensuring compliance updates flow over-the-air rather than via costly service campaigns.
Other drivers and restraints analyzed in the detailed report include:
- Integration of IoT/AI/ML for Fleet Optimization
- Rapid Electrification of Car-Sharing Fleets
- Data-Privacy and Cyber-Security Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, aftermarket retrofits dominated with 57.42% revenue, reflecting the sizeable legacy vehicle pool. Yet OEM-embedded units are advancing at 14.92% CAGR, helped by factory-level compliance with eCall-style mandates and tighter cybersecurity hardening. Automakers now expose on-board APIs that furnish granular battery, ADAS, and climate data, giving operators more levers to drive up fleet utilization. Partnerships such as Geotab's direct pipeline into Volkswagen Group dashboards exemplify the gravitation toward ecosystem plays that marry hardware, software, and field-updatable firmware in a single lifecycle stack.
The car sharing telematics market size for OEM-integrated deployments is projected to climb sharply as BEV adoption widens, because battery diagnostics demand direct traction-system access that retrofit dongles cannot match reliably. Nonetheless, retrofit vendors still serve mixed-fuel fleets and emerging markets where vehicle ages average above eight years, keeping a two-speed channel landscape intact through the mid-term.
Cost parity between embedded and aftermarket is narrowing as silicon prices climb, while over-the-air provisioning reduces fit-out labor for factory units. Larger operators hedge by blending both strategies: new acquisitions arrive with embedded telematics, but veteran gasoline or hybrid units receive certified third-party devices to unify granular data feeds. This hybrid posture insulates businesses from single-vendor risk and shortens refresh cycles without stranding capital-practices that shape procurement playbooks across the broader car sharing telematics market.
Embedded modules accounted for 45.48% revenue in 2025, but fully integrated connectivity platforms-encompassing 4G/5G modems, edge AI, and secure bootloaders-exhibit a 16.65% CAGR. These units aggregate functions that once required discrete devices, trimming wiring harnesses while expanding compute throughput. Integrated architectures expose open APIs, enabling developers to layer MaaS billing engines, predictive-maintenance dashboards, and carbon-footprint calculators atop the same telemetry backbone.Tethered solutions that depend on smartphone pairing are receding as fleet operators prioritize always-on redundancy for lock/unlock, immobilizer, and remote-disabling commands. The car sharing telematics market size attached to integrated-form deployments is forecast to outstrip tethered revenues by 2027 as 5G coverage proliferates across metropolitan corridors, permitting latency-sensitive applications such as tele-driving and remote-valet services.
Edge-side containerization now allows multiple virtualized applications to coexist securely within one telematics control unit, future-proofing fleets against evolving standards. Standardization drives cross-OEM data fusion, simplifying multi-brand fleet operations and trimming software-integration overhead. As a result, integrated solutions increasingly underpin RFP criteria among both new entrants and incumbent operators, accelerating their momentum within the car sharing telematics market.
Complete Report Scope:
- By Channel
- Original Equipment Manufacturer (OEM)
- Aftermarket
- By Form
- Embedded
- Tethered
- Integrated
- By Car-Sharing Model
- Round-trip / Station-based
- Free-floating (One-way)
- Peer-to-Peer (P2P)
- Corporate / Fleet
- By Vehicle Propulsion
- Internal-Combustion Engine (ICE)
- Battery-Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV/PHEV)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Europe retains 36.62% revenue leadership owing to mature regulations that mandate advanced safety and connectivity suites on all new vehicles. National incentive schemes bordering Germany, France, and the Nordics subsidize electrified car-sharing fleets, making BEV subscriptions financially compelling for operators. ShareNow's expansion eastward demonstrates intra-continental knowledge transfer, while Renault's Utrecht V2G pilot showcases grid-integrated mobility potential. Asia Pacific is scaling fastest at 14.33% CAGR, underwritten by rapid urban migration and sovereign smart-city budgets. Mainland China alone fields robotaxi pilots across more than 50 municipalities, each requiring ultra-low-latency connectivity baked into fleet telematics. The region counts 1.8 billion mobile subscribers, a connectivity bedrock for real-time fleet orchestration and over-the-air updates. Southeast Asian governments are likewise subsidizing telematics-based fleet-management rollouts, cultivating a fertile runway for the car sharing telematics market. North America exhibits mixed momentum: tech-centric metros adopt 5G-enabled tele-driving pilots, whereas suburban sprawl depresses vehicle-turnover metrics. Verizon Business' Las Vegas partnership with Vay highlights the push toward remote-driven e-vehicles that cut repositioning labor while leveraging mmWave bandwidth. Rural and ex-urban districts, however, remain tethered to LTE or legacy 3G networks, tempering service-expansion economics. Canada and the United States increasingly prioritize cybersecurity alignment with federal standards such as ISO/SAE 21434, adding an additional compliance layer yet reinforcing consumer trust-crucial for sustained car sharing telematics market penetration.
- INVERS GmbH
- Vulog
- Ridecell Inc.
- Convadis AG
- Continental Aftermarket and Services
- OCTO Group S.p.A
- Geotab Inc.
- Targa Telematics
- Fleetster
- OpenFleet
- Mobility Tech Green
- WeGo B.V.
- MoC Sharing
- Free2Move
- Miles Mobility
- Share Now
- Sixt share
- Getaround
- Zity
- Bolt Drive
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing urban preference for shared mobility
- 4.2.2 Government mandates for vehicle telematics (eCall, safety)
- 4.2.3 Integration of IoT/AI/ML for fleet optimisation
- 4.2.4 Rapid electrification of car-sharing fleets
- 4.2.5 Usage-based-insurance partnerships lowering OPEX
- 4.2.6 API-first telematics platforms enabling MaaS aggregation
- 4.3 Market Restraints
- 4.3.1 High hardware and installation costs
- 4.3.2 Data-privacy and cyber-security concerns
- 4.3.3 Lack of telematics interoperability standards
- 4.3.4 Low utilisation rates in suburban and rural zones
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment and Funding Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Channel
- 5.1.1 Original Equipment Manufacturer (OEM)
- 5.1.2 Aftermarket
- 5.2 By Form
- 5.2.1 Embedded
- 5.2.2 Tethered
- 5.2.3 Integrated
- 5.3 By Car-Sharing Model
- 5.3.1 Round-trip / Station-based
- 5.3.2 Free-floating (One-way)
- 5.3.3 Peer-to-Peer (P2P)
- 5.3.4 Corporate / Fleet
- 5.4 By Vehicle Propulsion
- 5.4.1 Internal-Combustion Engine (ICE)
- 5.4.2 Battery-Electric Vehicle (BEV)
- 5.4.3 Hybrid Electric Vehicle (HEV/PHEV)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 UAE
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 INVERS GmbH
- 6.4.2 Vulog
- 6.4.3 Ridecell Inc.
- 6.4.4 Convadis AG
- 6.4.5 Continental Aftermarket and Services
- 6.4.6 OCTO Group S.p.A
- 6.4.7 Geotab Inc.
- 6.4.8 Targa Telematics
- 6.4.9 Fleetster
- 6.4.10 OpenFleet
- 6.4.11 Mobility Tech Green
- 6.4.12 WeGo B.V.
- 6.4.13 MoC Sharing
- 6.4.14 Free2Move
- 6.4.15 Miles Mobility
- 6.4.16 Share Now
- 6.4.17 Sixt share
- 6.4.18 Getaround
- 6.4.19 Zity
- 6.4.20 Bolt Drive
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026-2030年全球汽車共享市場
 汽車共享遠端資訊處理市場(第八版)
 汽車共享市場規模、佔有率和成長分析:按經營模式、車輛類型、使用模式、平台、最終用戶和地區分類-2026-2033年產業預測
 P2P汽車共享市場預測至2034年-按預訂週期、車輛類型、平台類型、收入模式、最終用戶和地區分類的全球分析基於站點的汽車共享市場預測至 2034 年—按車輛類型、驅動系統、預訂方式、使用模式、所有權模式、最終用戶和地區進行全球分析。汽車共享市場預測至2034年—全球經營模式、旅遊類型、車輛類型、動力類型、預訂方式、使用時間、應用領域、最終用戶和區域分析自由浮動汽車共享市場預測至2034年—按車輛類型、驅動方式、預訂平台、服務區域、收費系統、最終用戶和地區分類的全球分析P2P汽車共享市場預測至2034年-按車輛類型、平台類型、供應商合作夥伴、最終用戶和地區分類的全球分析
 P2P汽車共享市場:依車輛類型、租賃期限、服務模式及地區分類
 汽車共享市場規模、佔有率、趨勢和預測:按車輛類型、經營模式、應用和地區分類,2026-2034年