


 |
市場調查報告書
商品編碼
2123406
壓力標籤:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Pressure Labels - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
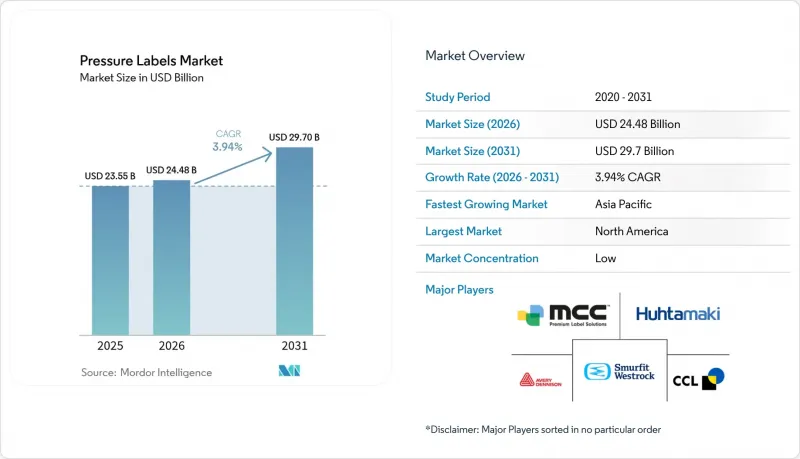
根據 Mordor Intelligence 預測,壓敏標籤市場規模預計將從 2025 年的 235.5 億美元成長到 2026 年的 244.8 億美元,到 2031 年將達到 297 億美元,2026 年至 2031 年的複合年成長率為 3.94%。
本報告按印刷過程(凹版印刷、柔版印刷、網版印刷、凸版印刷、噴墨印刷等)、終端用戶(食品、飲料、醫療保健、化妝品、家居用品、工業等)、黏合劑類型(水性丙烯酸膠、熱熔膠、溶劑型膠、UV固化膠)和地區進行細分。市場預測以美元(USD)為單位。
全球壓敏標籤市場趨勢及洞察
電子商務和即時物流的成長
隨著線上零售小包裹數量的持續成長,倉庫現在每天都要列印數百萬張壓敏黏著劑標籤。物流業者需要選用既能承受輸送機磨損,又能在紙板重複使用時輕鬆移除的黏合劑。 UPM 黏合劑材料公司推出了可剝離的物流標籤面材,能夠應對多次運輸循環。此外,隨著品牌商減少庫存緩衝,加工商必須在數小時內而非數週內交付客製化標籤。這種緊迫性正在推動感壓標籤市場的成長,因為能夠以最短停機時間切換作業的數位印刷機具有優勢。
小批量、可變數據數位印刷的興起
數位技術使加工商能夠即時個性化圖形、語言和序號。凹版印刷機在高階化妝品領域成長最快,但小批量印刷仍然需要滾筒,這增加了成本。相較之下,碳粉和噴墨平台無需製版即可列印序列化條碼和特定區域的設計。 AGH Labels 強調,高解析度單一途徑金屬化效果如今已能媲美模擬印刷,同時還能減少準備過程中的廢棄物。這些優勢預計將推動凹版印刷實現 6.13% 的複合年成長率,並增強壓標市場的整體韌性。
原料(丙烯酸壓敏膠)價格波動
石化產品現貨價格飆升,給工商的利潤率帶來壓力。美國化學工業協會 (ACC) 的報告顯示,全球化學品產量僅略有成長,顯示單體供應緊張。生產商正透過轉向使用生物基黏合劑(例如 Sasolwax)來規避風險,這種黏合劑可將「從搖籃到大門」的生產過程對環境的影響降低 35%,並有助於實現更穩定的價格。
細分市場分析
預計到2025年,柔版印刷將佔銷售額的38.12%,這表明其在食品標籤的大規模生產中具有成本效益。另一方面,凹版印刷預計將以5.86%的複合年成長率成長,因為化妝品和製藥行業的買家對照片級品質和金屬油墨的需求日益成長。凹版印刷標籤市場預計到2031年將達到75.3億美元,顯示高階細分市場正在擴張。網版印刷和凸版印刷在注重觸感的高階包裝領域仍保持著強勁的需求,而噴墨印刷在序列化領域的應用也日益廣泛。
柔版印刷企業正透過最佳化設置廢棄物和採用UV-LED固化技術來降低能耗,從而減輕原料價格波動的影響。凹版印刷企業則利用電子機械雕刻技術來縮短滾筒的前置作業時間,並加速新產品的推出。壓標市場正受益於這些技術的均衡組合,為品牌所有者提供一系列根據其應用等級量身定做的價格和服務選擇。監管審核也強調流程是否符合ISO 9001:2015認證和G7色彩標準,即使在新興市場,流程升級也穩步推進。
區域分析
2025年,北美地區佔總銷售額的39.05%,主要得益於嚴格的可追溯性法規和先進的零售自動化技術。 《藥品供應鏈安全法案》和《食品安全現代化法案》確保了醫藥和綠葉蔬菜產業對穀物標籤的全年需求。 CCL Industries在2025年第一季實現了8.6%的銷售額成長,反映出儘管原物料價格波動,加工商的利潤率依然強勁。 UPM對米爾斯河工廠的投資增加了高階葡萄酒、烈酒和郵政層壓材料的生產,確保了本地供應。
亞太地區預計將成為成長最快的地區,到2031年複合年成長率將達到5.33%,這主要得益於可支配收入的成長,這將推動對包裝化妝品和即飲茶的需求。 UPM位於柔佛新山的塗佈生產線將供應薄膜標籤和電子標籤,以滿足該地區電子產品的出口需求。菲律賓和越南實施的生產者延伸責任制(EPR)正在刺激對可水洗標籤和無底紙標籤的需求。國內加工商正在投資數位印刷機,以便為東協地區的行動用戶群提供多語言產品。隨著全球品牌將工廠遷至雅加達、胡志明市和班加羅爾附近,壓標市場正經歷供應鏈轉型。
在歐洲,由於雄心勃勃的回收目標和先進的收集系統,市場保持穩定成長。包裝和包裝廢棄物法規要求加工商證明其產品與家用分類機相容。獲得APR認證的標籤和容器系統可享有環境調整費,從而降低了生產者延伸責任的成本,並鼓勵企業採用。 2019年藥品序列化製度的全面實施也促進了代碼標籤的持續銷售。英國脫歐帶來的監管差異增加了市場的複雜性,但現有主要企業正在迅速適應並維持客戶忠誠度。這些因素共同推動歐洲壓標市場維持穩定上升的態勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務和即時物流的成長
- 數位印刷的興起,帶來了更短的交貨時間和可變數據。
- 品牌擁有者對永續面材和襯墊的需求。
- 食品和製藥行業嚴格的可追溯性要求
- 零售自動化中無底紙熱封標籤的引入
- 用於冷鏈監控的印刷電子元件的智慧標籤
- 市場限制因素
- 原料(丙烯酸壓敏膠)價格波動
- 嚴格的回收法規限制了混合材料的標籤標註。
- 在極端溫度和紫外線照射下,耐久性有其限制。
- 加工商向數位印刷機過渡過程中面臨的資本密集挑戰。
- 產業供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過印刷過程
- 凹版印刷
- 柔版印刷
- 螢幕
- 凸版印刷
- 噴墨
- 其他印刷過程
- 最終用戶
- 食物
- 飲料
- 衛生保健
- 化妝品
- 家
- 產業
- 其他終端用戶產業
- 黏合劑類型
- 水性丙烯酸
- 熱熔橡膠型
- 溶劑型
- 紫外線固化型
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Fuji Seal International Inc.
- Smurfit WestRock plc
- Huhtamaki Oyj
- Taghleef Industries LLC
- Coveris Group
- UPM Raflatac
- Taylor Corporation
- Constantia Flexibles Group GmbH
- Herma GmbH
- Skanem AS
- Resource Label Group, LLC
- Beontag Group
- Schreiner Group GmbH & Co. KG
- SATO Holdings Corporation
- Inland Packaging LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the pressure labels market size is expected to grow from USD 23.55 billion in 2025 to USD 24.48 billion in 2026 and is forecast to reach USD 29.7 billion by 2031 at 3.94% CAGR over 2026-2031.
This report is Segmented by Print Process (Gravure, Flexography, Screen, Letterpress, Inkjet, and More), End-User (Food, Beverage, Healthcare, Cosmetics, Household, Industrial, and More), Adhesive Type (Water-Based Acrylic, Hot-Melt Rubber-Based, Solvent-Based, and UV-Curable), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Pressure Labels Market Trends and Insights
Growth of e-commerce and just-in-time logistics
Parcel volumes from online retail continue to rise, and warehouses now print millions of pressure-sensitive shipping labels daily. Logistics providers specify adhesives that survive conveyor abrasion yet peel away cleanly for carton reuse. UPM Adhesive Materials released removable logistics facestocks that support multiple delivery cycles. Brand owners also compress inventory buffers, so converters must supply customized labels within hours rather than weeks. This urgency favors digital presses that swap jobs with minimal downtime, reinforcing the growth of the pressure labels market.
Rise of short-run, variable-data digital printing
Digital technology lets converters personalize graphics, languages, and serial numbers on the fly. Gravure presses, while growing fastest for premium cosmetics, still require cylinders that add cost at short lengths. By contrast, toner and inkjet platforms can print serialized barcodes or regional designs without the need for plates. AGH Labels highlighted that high-definition single-pass metalized effects now match analog quality while cutting makeready waste. These capabilities underpin the projected 6.13% CAGR for gravure and strengthen overall pressure labels market resilience.
Volatility in raw-material (acrylic PSA) prices
Spot petrochemical hikes squeeze converter margins. The American Chemistry Council reported fractional global chemical output growth, signaling tight monomer supply. Producers hedge by shifting to bio-based tackifiers, such as SASOLWAX, which offers a 35% lower cradle-to-gate footprint and more stable pricing.
Other drivers and restraints analyzed in the detailed report include:
- Brand-owner demand for sustainable facestocks and liners
- Strict traceability mandates in food and pharma
- Stringent recyclability regulations limiting mixed-material labels
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Flexography contributed 38.12% of the 2025 revenue, underscoring its cost-effectiveness for long food labeling runs. Gravure printing, however, is projected to deliver a 5.86% CAGR as beauty and pharmaceutical buyers request photographic quality and metallic inks. The pressure labels market size for gravure formats is forecast to reach USD 7.53 billion by 2031, indicating a widening premium niche. Screen and letterpress retain loyal followings in tactile luxury packaging, while inkjet widens adoption in serialization.
Flexo converters mitigate raw-material fluctuations by optimizing setup waste and implementing UV-LED curing, which reduces power consumption. Gravure facilities utilize electromechanical engraving to reduce cylinder lead times, enabling faster introductions of new products. The pressure labels market benefits from this balanced technology mix, giving brand owners price-service options across application tiers. Regulatory audits also favor processes certified to ISO 9001:2015 and G7 color targets, prompting process upgrades even in emerging economies.
Complete Report Scope:
- By Print Process
- Gravure
- Flexography
- Screen
- Letterpress
- Inkjet
- Other Print Processes
- By End-User
- Food
- Beverage
- Healthcare
- Cosmetics
- Household
- Industrial
- Other End-user Industries
- By Adhesive Type
- Water-based Acrylic
- Hot-melt Rubber-based
- Solvent-based
- UV-curable
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 39.05% of 2025 revenue, anchored by strict traceability legislation and sophisticated retail automation. The Drug Supply Chain Security Act and the Food Safety Modernization Act sustain annual demand for serialized labels across the pharmaceutical and leafy green industries. CCL Industries logged 8.6% sales growth in Q1 2025, reflecting steady converter margins despite input volatility. Investments at UPM's Mills River site add premium wine, spirits, and postal laminates, ensuring local supply.
The Asia-Pacific region is projected to record the fastest growth, with a 5.33% CAGR through 2031, as rising disposable incomes drive demand for packaged cosmetics and ready-to-drink teas. UPM's Johor Bahru coating line will supply filmic and electronics labels to meet regional electronics exports. Extended Producer Responsibility laws in the Philippines and Vietnam stimulate demand for wash-off or linerless labels. Domestic converters invest in digital presses to offer multilingual versions for ASEAN's mobile consumer base. The pressure labels market is seeing supply-chain shifts as global brands relocate plants closer to Jakarta, Ho Chi Minh City, and Bengaluru.
Europe maintains moderate growth underpinned by ambitious recycling targets and advanced collection systems. The Packaging and Packaging Waste Regulation pressures converters to prove compatibility with household sorters. APR-certified label-container systems earn eco-modulated fees that lower extended producer costs, encouraging adopters. Pharmaceutical serialization, complete since 2019, sustains recurring code-label purchases. Brexit regulatory divergence adds complexity, but established players adapt swiftly, preserving customer loyalty. Together these factors keep the pressure labels market in Europe on a stable upward path.
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Fuji Seal International Inc.
- Smurfit WestRock plc
- Huhtamaki Oyj
- Taghleef Industries LLC
- Coveris Group
- UPM Raflatac
- Taylor Corporation
- Constantia Flexibles Group GmbH
- Herma GmbH
- Skanem AS
- Resource Label Group, LLC
- Beontag Group
- Schreiner Group GmbH & Co. KG
- SATO Holdings Corporation
- Inland Packaging LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of e-commerce and just-in-time logistics
- 4.2.2 Rise of short-run, variable-data digital printing
- 4.2.3 Brand-owner demand for sustainable facestocks and liners
- 4.2.4 Strict traceability mandates in food and pharma
- 4.2.5 Adoption of liner-less pressure labels in retail automation
- 4.2.6 Smart labels with printed electronics for cold-chain monitoring
- 4.3 Market Restraints
- 4.3.1 Volatility in raw-material (acrylic PSA) prices
- 4.3.2 Stringent recyclability regulations limiting mixed-material labels
- 4.3.3 Limited durability in extreme temperatures and UV exposure
- 4.3.4 Capital-intensive transition to digital presses for converters
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Print Process
- 5.1.1 Gravure
- 5.1.2 Flexography
- 5.1.3 Screen
- 5.1.4 Letterpress
- 5.1.5 Inkjet
- 5.1.6 Other Print Processes
- 5.2 By End-User
- 5.2.1 Food
- 5.2.2 Beverage
- 5.2.3 Healthcare
- 5.2.4 Cosmetics
- 5.2.5 Household
- 5.2.6 Industrial
- 5.2.7 Other End-user Industries
- 5.3 By Adhesive Type
- 5.3.1 Water-based Acrylic
- 5.3.2 Hot-melt Rubber-based
- 5.3.3 Solvent-based
- 5.3.4 UV-curable
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 CCL Industries Inc.
- 6.4.2 Avery Dennison Corporation
- 6.4.3 Multi-Color Corporation
- 6.4.4 Fuji Seal International Inc.
- 6.4.5 Smurfit WestRock plc
- 6.4.6 Huhtamaki Oyj
- 6.4.7 Taghleef Industries LLC
- 6.4.8 Coveris Group
- 6.4.9 UPM Raflatac
- 6.4.10 Taylor Corporation
- 6.4.11 Constantia Flexibles Group GmbH
- 6.4.12 Herma GmbH
- 6.4.13 Skanem AS
- 6.4.14 Resource Label Group, LLC
- 6.4.15 Beontag Group
- 6.4.16 Schreiner Group GmbH & Co. KG
- 6.4.17 SATO Holdings Corporation
- 6.4.18 Inland Packaging LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 壓敏標籤市場:依形式、材料、黏合劑、印刷技術和應用分類-2026-2032年全球市場預測
 感壓標籤市場(2026 年)
 壓力標籤市場:依產品類型、應用、終端用戶產業和地區分類
 全球感壓標籤市場:市場規模、佔有率、成長和行業分析:按材料類型、最終用途和地區分類的預測(至2034年)
 感壓標籤市場規模、佔有率及成長分析(按類型、標籤類型、應用和地區分類)-2026-2033年產業預測
 全球感壓標籤市場
 全球無底紙感壓標籤市場規模(按標籤類型、印刷技術、應用、區域範圍和預測)全球壓力標籤市場:市場規模(按類型、印刷技術、最終用戶和地區分類)、未來預測壓力標籤市場報告:2031 年趨勢、預測與競爭分析