


 |
市場調查報告書
商品編碼
2122263
袋裝包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Pouch Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
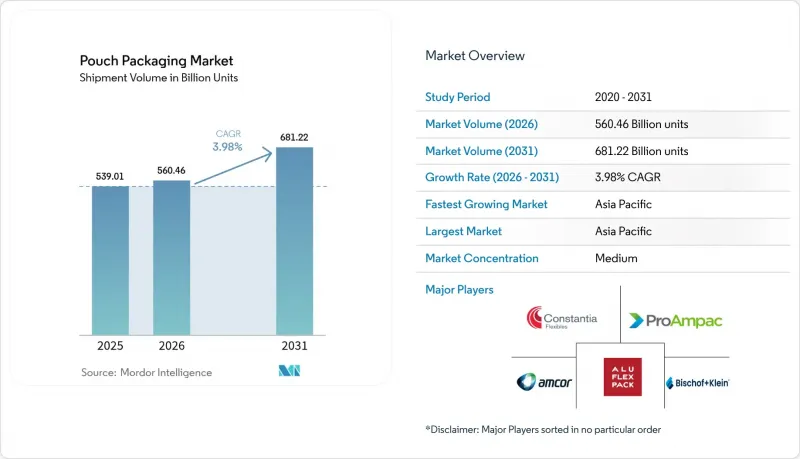
據 Mordor Intelligence 稱,2025 年袋裝包裝市場價值為 5390.1 億美元,預計到 2031 年將達到 6812.2 億美元,而 2026 年為 5604.6 億美元,預測期(2026-2031 年)的複合成長率為 3.98%。
本報告按材料(塑膠、紙張、鋁箔、可生物分解/可堆肥材料)、產品類型(扁平包裝、立式包裝、帶蒸餾、耐高溫蒸煮包裝、無菌包裝、條狀包裝/小袋包裝、捲材/預製袋包裝)、封口類型(拉鍊、吸嘴/瓶蓋、其他)、終端用戶(製藥食品、飲料市場預測以數量(單位)為基礎。
全球袋裝包裝市場趨勢與洞察
對經濟實惠的包裝和品牌差異化的需求日益成長。
在消費品利潤率面臨日益成長的通膨壓力之際,消費者對既能減少材料用量又不影響視覺吸引力的包裝的需求日益成長。與同類硬質包裝相比,軟包裝袋通常可減少70%的基材用量,並提供更大的印刷面積,便於高解析度影像的呈現。根據ProAmpac發布的2024年報告,可回收軟包裝袋可為品牌所有者節省15%至20%的材料成本。中小品牌正利用這些經濟優勢,實現與跨國企業相媲美的視覺效果,從而促進市場細分,並提升價格敏感型品類的銷售。
簡便食品和即食食品的消費量正在激增。
隨著都市化進程的推進和家庭規模的縮小,人們對單份裝、可微波加熱的已調理食品的需求日益成長,這類食品非常適合採用軟包裝。根據美國農業部數據顯示,中國二線城市的已調理食品市場正以每年12%的速度成長,其中具有均勻加熱和蒸氣釋放功能的包裝袋市場佔有率不斷擴大。像「Once Upon a Farm」這樣的高階嬰幼兒食品生產商正在利用吸嘴包裝袋來延長保存期限,並憑藉其卓越的性能來支撐更高的價格。
日益惡化的環境問題和回收的挑戰
軟包裝薄膜的回收基礎設施遠遠落後於寶特瓶和金屬罐,品牌商也因此背負了擴大生產者責任制(EPR)所帶來的成本負擔。根據軟包裝協會統計,美國僅有4%的軟包裝薄膜以機械方式回收,迫使加工商承擔昂貴的回收成本。同時,提案的PFAS(全氟烷基物質)禁令威脅食品安全所必需的阻隔化學物質,這種不確定性正在減緩對新生產線的投資。
細分市場分析
2025年,塑膠仍佔據軟包裝市場60.72%的佔有率。這主要得益於聚乙烯和聚丙烯的低成本和易加工性。然而,隨著監管機構指出,未來廢棄物處理方案的成本績效將優於傳統方案,生物基和可堆肥材料的市佔率正以6.05%的複合年成長率迅速成長。領先的加工商正將植物來源樹脂與基於奈米纖維素的阻隔塗層相結合,其氧氣阻隔性能可與EVOH相媲美。
在軟包裝市場,能夠確保產品保護並兼顧可回收性的單材料包裝創新備受重視。預計到2024年,簡化結構的專利申請量將成長40%,顯示材料科學領域的競爭日益激烈。加工商正積極投資於相容劑和無溶劑複合技術,以期在2030年截止日期前達到歐盟的回收率標準。同時,在對氧氣透過率要求極高的高階應用中,鋁箔的使用量保持穩定,但降低其厚度的努力仍在繼續。
扁平袋仍佔袋裝包裝市場36.33%的佔有率,反映出其在乾貨領域的廣泛應用。然而,隨著零售商重視自立袋在擁擠貨架上的“垂直標識效應”,立式袋正以5.43%的複合年成長率成長。品牌商也開始採用風琴褶底和逼真的印刷技術,即使在堅果零食和寵物零食等同質化品類中,也力求提升產品的高階價值。
功能性專業化的包裝形式也不斷增加。殺菌袋可用於生產常溫保存的蒸餾食品,無菌複合包裝在飲料領域尋求新的機遇,而條狀包裝則在單份營養補充劑市場佔據主導地位。從捲材到填充的一體化工作流程為大批量生產的SKU提供了成本優勢,而預製件則適用於小批量生產。 Gualapack在巴西提供的整合式複合、射出成型和填充解決方案,正是端到端管控如何降低缺陷率並縮短產品上市時間的絕佳例證。
區域分析
預計到2025年,亞太地區將以39.54%的市佔率引領軟包裝市場,並在2031年之前維持6.74%的複合年成長率。在中國,受有組織零售和嚴格的食品安全法規的推動,消費者迅速轉向加工食品,這支撐了強勁的需求。在印度,現代零售業的擴張推動了銷售成長,而韓國的K-beauty生態系統則向全球出口軟性化妝品包裝。區域加工商受益於接近性原生樹脂來源地和具有成本優勢的勞動力,從而強化了本地化的供應鏈,即便跨國品牌所有者正在尋求包裝規格的全球標準化。
在北美,成熟的需求趨勢正在顯現,重點在於優質化和電商相容性。輕量化設計降低了體積重量收費下的運輸成本,促使零售商採用自有品牌包裝袋。在歐洲,監管部門為提高可回收性而採取的措施正在加速單一材料產品的普及,而軟包裝在生命週期指標方面優於硬質玻璃和多層紙盒。在斯堪地那維亞市場,一項針對軟包裝薄膜的押金制度正在試驗推行,為歐盟範圍內的推廣提供數據支援。
南美洲、中東和非洲作為新興市場,普遍具有巨大的成長潛力。在巴西,乳製品業已採用袋裝酵母菌飲料,因為這種包裝在冷鏈運輸中具有節能優勢。海灣合作理事會(GCC)成員國正在進口採用袋裝包裝的蒸餾食品,這種包裝能夠承受沙漠地區的物流條件。在非洲特大城市,小袋裝食品正被用作價格實惠的日常用品。儘管基礎設施挑戰依然存在,但人口成長動能和可支配收入的提高預計將逐步縮小與已開發地區的差距。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對經濟實惠的包裝和品牌差異化的需求日益成長。
- 簡便食品和即食食品的消費量正在激增。
- 永續發展驅動輕量化、軟性包裝轉型
- 加速電子商務和直接面對消費者的物流
- 擴大帶傾倒嘴包裝袋在工業散裝應用中的使用。
- 阻隔性單材料薄膜取得突破性進展,實現可回收。
- 市場限制因素
- 日益惡化的環境問題和回收的挑戰
- 塑膠樹脂原料價格波動
- 來自新興纖維基軟形態的競爭
- 生物基阻隔性樹脂的供應限制
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
- 回收和永續性趨勢
第5章 市場規模與成長預測
- 材料
- 塑膠
- 聚乙烯(PE)
- 聚丙烯(PP)
- 聚對苯二甲酸乙二醇酯(PET)
- 聚氯乙烯樹脂(PVC)
- 其他塑膠
- 紙
- 鋁箔
- 可生物分解/可堆肥
- 塑膠
- 依產品類型
- 平的(枕形側密封)
- 起來
- 帶傾倒嘴
- 蒸餾
- 無菌
- 條狀包裝小袋
- 卷材/預製袋
- 閉合型
- 拉鍊
- 壺嘴和蓋子
- 蒂亞諾西
- 滑桿
- 其他閉合類型
- 按最終用戶行業分類
- 食物
- 糖果和糖果甜點
- 冷凍食品
- 生鮮食品
- 乳製品
- 乾貨和穀物
- 肉類、雞肉、魚貝類
- 寵物食品
- 其他食品(醬料、調味品、抹醬)
- 飲料
- 酒精飲料
- 非酒精性
- 醫療和藥品
- 個人護理和化妝品
- 居家照護/家庭護理
- 其他
- 食物
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 肯亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Mondi plc
- ProAmpac Intermediate, Inc.
- Constantia Flexibles Group GmbH
- Huhtamaki Oyj
- Sealed Air Corporation
- Sonoco Products Company
- Coveris Management GmbH
- Bischof+Klein SE and Co. KG
- FlexPak Services, LLC
- Goglio SpA
- Scholle IPN Corporation
- Gualapack SpA
- Aluflexpack AG
- Flair Flexible Packaging Corporation
- Hood Packaging Corporation
- Toppan Printing Co., Ltd.
- Winpak Ltd.
- Glenroy, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the pouch packaging market size was valued at USD 539.01 billion in 2025 and estimated to grow from USD 560.46 billion in 2026 to reach USD 681.22 billion by 2031, at a CAGR of 3.98% during the forecast period (2026-2031).
This report is Segmented by Material (Plastics, Paper, Aluminum Foil, Bio-degradable/Compostable), Product Type (Flat, Stand-Up, Spouted, Retort, Aseptic, Stick-Pack/Sachet, Rollstock/Premade Pouch), Closure Type (Zipper, Spout and Cap, and More), End-User Industry (Food, Beverage, Medical and Pharmaceutical, and More), and Geography. The Market Forecasts are Provided in Terms of Volume (Units).
Global Pouch Packaging Market Trends and Insights
Rising Demand for Cost-Effective Packaging and Brand Differentiation
Inflationary pressure on consumer goods margins intensifies the search for packaging formats that cut material usage without compromising shelf appeal. Pouches typically use 70% less substrate than comparable rigid packs and provide a larger printable surface that supports high-resolution graphics. ProAmpac's 2024 report shows curbside-recyclable pouches delivering 15-20% material cost savings for brand owners. Smaller brands leverage these economics to match the visual impact of multinationals, fostering market fragmentation and stimulating additional unit volumes across price-sensitive categories.
Surge in Convenience and Ready-to-Eat Food Consumption
Rising urbanization and smaller household sizes translate into greater reliance on single-serve, microwave-ready meals best suited to flexible formats. USDA data indicates 12% annual growth in ready meals across China's tier-2 cities, with pouches gaining share due to uniform heating and steam venting capabilities. Premium baby-food players such as Once Upon a Farm capitalize on spouted pouches that extend shelf life and justify price premiums through superior functionality.
Escalating Environmental and Recycling Challenges
Flexible-film recycling infrastructure lags far behind that of PET bottles or metal cans, exposing brands to Extended Producer Responsibility fees. The Flexible Packaging Association notes only 4% of flexible films are mechanically recycled in the United States, leaving converters to fund costly take-back schemes. Meanwhile, proposed PFAS bans threaten barrier chemistries vital for food safety, creating uncertainty that slows capital spending on new lines.
Other drivers and restraints analyzed in the detailed report include:
- Sustainability-Driven Shift Toward Lightweight Flexible Packs
- Acceleration of E-Commerce and Direct-to-Consumer Logistics
- Volatility in Plastic-Resin Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics retained a 60.72% pouch packaging market share in 2025, anchored by the affordability and processability of polyethylene and polypropylene. Yet bio-based and compostable materials are gaining a 6.05% CAGR foothold as regulators signal a future where end-of-life solutions trump historic cost-performance ratios. Leading converters integrate plant-derived resins with barrier coatings based on nanofibrillated cellulose that rival EVOH in oxygen-blocking capacity.
The pouch packaging market rewards mono-material breakthroughs that ensure recyclability while maintaining product protection. Patent filings for simplified structures rose 40% in 2024, demonstrating a material-science arms race. Converters investing in compatibilizers and solvent-free lamination position themselves to meet EU recyclability quotas ahead of the 2030 deadline. Meanwhile, aluminum foil usage holds steady in premium applications that demand near-zero oxygen ingress, though downgauging efforts continue.
Flat formats still constitute 36.33% of the pouch packaging market size, reflecting entrenched applications in dry goods. Stand-up pouches, however, outpace at a 5.43% CAGR as retailers reward the vertical billboard effect on crowded shelves. Brands exploit gusseted bases and photo-realistic printing to signal premium value, even in commoditized categories such as snack nuts or pet treats.
Function-specific variants proliferate. Retort pouches enable shelf-stable ready meals, aseptic laminates chase beverage opportunities, and stick packs dominate single-serve nutraceuticals. Integrated rollstock-to-fill workflows deliver cost advantages for high-volume SKUs, whereas premade formats suit small batch runs. Gualapack's integrated laminate, injection, and filling solution in Brazil exemplifies how end-to-end control lowers failure rates while accelerating time to market.
Complete Report Scope:
- By Material
- Plastics
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polyvinyl Chloride resin (PVC)
- Other Plastics
- Paper
- Aluminum Foil
- Bio-degradable/Compostable
- Plastics
- By Product Type
- Flat (Pillow and Side-Seal)
- Stand-Up
- Spouted
- Retort
- Aseptic
- Stick-Pack / Sachet
- Rollstock / Premade Pouch
- By Closure Type
- Zipper
- Spout and Cap
- Tear-Notch
- Slider
- Other Closure Type
- By End-User Industry
- Food
- Candy and Confectionery
- Frozen Foods
- Fresh Produce
- Dairy Products
- Dry Foods and Cereals
- Meat, Poultry and Seafood
- Pet Food
- Other Foods (Sauces, Condiments, Spreads)
- Beverage
- Alcoholic
- Non-Alcoholic
- Medical and Pharmaceutical
- Personal Care and Cosmetics
- Home Care and Household
- Other End-User Industry
- Food
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific led with 39.54% of the pouch packaging market share in 2025 and is forecast to record a 6.74% CAGR to 2031. China's rapid shift toward packaged foods, propelled by organized retail and stringent food-safety laws, keeps demand buoyant. India's modern trade expansion drives volume gains, while South Korea's K-Beauty ecosystem exports flexible cosmetic packs worldwide. Regional converters benefit from proximity to virgin resin suppliers and cost-competitive labor, reinforcing localized supply chains even as multinational brand owners demand global harmonization of pack specifications.
North America exhibits a mature demand profile focused on premiumization and e-commerce readiness. Lightweight designs translate into shipping cost savings under dimensional-weight tariffs, pushing retailers toward house-brand pouch adoption. Europe's regulatory drive toward recyclability accelerates mono-material rollouts, positioning flexible packs ahead of rigid glass and multilayer cartons on lifecycle metrics. Scandinavian markets pilot deposit schemes for flexible films, providing data for broader EU implementation.
South America and the Middle East, and Africa collectively offer emerging upside. Brazil's dairy sector adopts spouted pouches for yogurt drinks, citing cold-chain energy savings. Gulf Cooperation Council nations import pouch-packed ready meals that withstand desert logistics, and African megacities rely on small-sachet formats for affordable daily necessities. Infrastructure hurdles remain, yet demographic momentum and rising disposable incomes will progressively close the gap with developed regions.
- Amcor plc
- Mondi plc
- ProAmpac Intermediate, Inc.
- Constantia Flexibles Group GmbH
- Huhtamaki Oyj
- Sealed Air Corporation
- Sonoco Products Company
- Coveris Management GmbH
- Bischof + Klein SE and Co. KG
- FlexPak Services, LLC
- Goglio SpA
- Scholle IPN Corporation
- Gualapack SpA
- Aluflexpack AG
- Flair Flexible Packaging Corporation
- Hood Packaging Corporation
- Toppan Printing Co., Ltd.
- Winpak Ltd.
- Glenroy, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for cost-effective packaging and brand differentiation
- 4.2.2 Surge in convenience and ready-to-eat food consumption
- 4.2.3 Sustainability-driven shift toward lightweight flexible packs
- 4.2.4 Acceleration of e-commerce and direct-to-consumer logistics
- 4.2.5 Expansion of spouted pouches in industrial bulk applications
- 4.2.6 High-barrier mono-material film breakthroughs enabling recyclability
- 4.3 Market Restraints
- 4.3.1 Escalating environmental and recycling challenges
- 4.3.2 Volatility in plastic-resin feedstock prices
- 4.3.3 Competition from emerging fiber-based flexible formats
- 4.3.4 Supply constraints for bio-based high-barrier resins
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
- 4.9 Recycling and Sustainability Landscape
5 MARKET SIZE AND GROWTH FORECASTS(VALUE)
- 5.1 By Material
- 5.1.1 Plastics
- 5.1.1.1 Polyethylene (PE)
- 5.1.1.2 Polypropylene (PP)
- 5.1.1.3 Polyethylene Terephthalate (PET)
- 5.1.1.4 Polyvinyl Chloride resin (PVC)
- 5.1.1.5 Other Plastics
- 5.1.2 Paper
- 5.1.3 Aluminum Foil
- 5.1.4 Bio-degradable/Compostable
- 5.1.1 Plastics
- 5.2 By Product Type
- 5.2.1 Flat (Pillow and Side-Seal)
- 5.2.2 Stand-Up
- 5.2.3 Spouted
- 5.2.4 Retort
- 5.2.5 Aseptic
- 5.2.6 Stick-Pack / Sachet
- 5.2.7 Rollstock / Premade Pouch
- 5.3 By Closure Type
- 5.3.1 Zipper
- 5.3.2 Spout and Cap
- 5.3.3 Tear-Notch
- 5.3.4 Slider
- 5.3.5 Other Closure Type
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.1.1 Candy and Confectionery
- 5.4.1.2 Frozen Foods
- 5.4.1.3 Fresh Produce
- 5.4.1.4 Dairy Products
- 5.4.1.5 Dry Foods and Cereals
- 5.4.1.6 Meat, Poultry and Seafood
- 5.4.1.7 Pet Food
- 5.4.1.8 Other Foods (Sauces, Condiments, Spreads)
- 5.4.2 Beverage
- 5.4.2.1 Alcoholic
- 5.4.2.2 Non-Alcoholic
- 5.4.3 Medical and Pharmaceutical
- 5.4.4 Personal Care and Cosmetics
- 5.4.5 Home Care and Household
- 5.4.6 Other End-User Industry
- 5.4.1 Food
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi plc
- 6.4.3 ProAmpac Intermediate, Inc.
- 6.4.4 Constantia Flexibles Group GmbH
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Sealed Air Corporation
- 6.4.7 Sonoco Products Company
- 6.4.8 Coveris Management GmbH
- 6.4.9 Bischof + Klein SE and Co. KG
- 6.4.10 FlexPak Services, LLC
- 6.4.11 Goglio SpA
- 6.4.12 Scholle IPN Corporation
- 6.4.13 Gualapack SpA
- 6.4.14 Aluflexpack AG
- 6.4.15 Flair Flexible Packaging Corporation
- 6.4.16 Hood Packaging Corporation
- 6.4.17 Toppan Printing Co., Ltd.
- 6.4.18 Winpak Ltd.
- 6.4.19 Glenroy, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


