


 |
市場調查報告書
商品編碼
2120611
北美流程自動化:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)North America Process Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
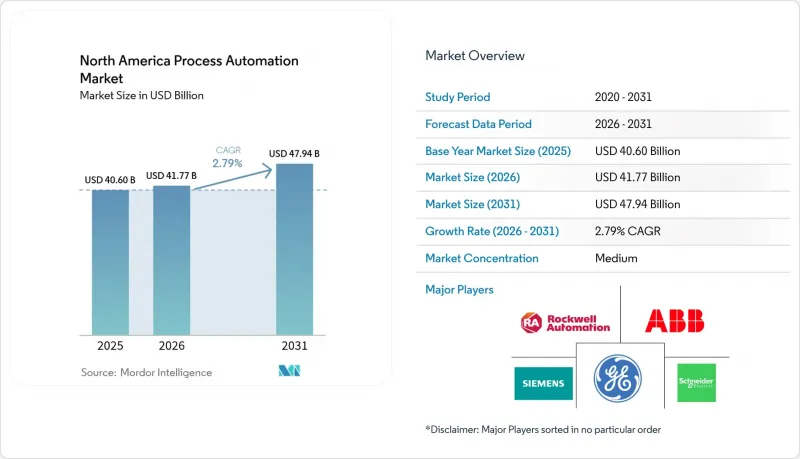
根據 Mordor Intelligence 預測,北美製程自動化市場規模將從 2025 年的 406 億美元和 2026 年的 417.7 億美元成長到 2031 年的 479.4 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 2.79%。
本報告按通訊協定(有線、無線)、系統類型(硬體、軟體)、元件(硬體、軟體、服務)、部署模式(本地部署、雲端/邊緣部署)、最終用戶產業(石油天然氣、化工和石化、電力和公共產業、用水和污水、其他)以及地區進行細分。市場預測以美元計價。
北美過程自動化市場趨勢與洞察
人們越來越關注能源效率和降低營運成本。
流程製造商正在重新定義自動化,將其作為減少排放的手段。美國能源局的《2024年工業脫碳藍圖》設定了2030年將工業能源強度降低10-15%的目標,優先考慮化學和煉油資產中的先進製程控制和即時最佳化。加拿大油砂業者面臨著2030年每噸170加幣的法定碳價,為此,他們實施了邊緣分析,以調整蒸汽產生器中的燃燒空氣比和給水成分,從而使每桶合成原油的天然氣用量減少了高達5%。墨西哥灣沿岸地區地區的一些設施利用多變量控制設備對蒸餾和熱交換器網路進行微調,其投資回收期不到18個月。這些初步成果意味著,2026年的資本預算正從單純擴大產能轉向利用數位技術解決瓶頸問題。
安全儀器系統的需求日益成長
2024-2025年間,煉油廠和化工廠發生的一系列事故促使監管機構加強了監管。美國化學品安全與危害調查委員會(CSB)將多起火災歸咎於安全完整性等級(SIL)檢驗不足,促使氣動跳閘系統進行維修,配備智慧定位器以實現線上診斷。如今,遵守美國職業安全與健康管理局(OSHA)的製程安全管理(PSM)要求進行有記錄的認證檢查,這推動了整合安全控制器的採購,這些控制器透過安全的OPC-UA閘道器連接到現有的DCS網路。隨著製藥和食品加工企業採用類似的架構來滿足無菌填充和過敏原管理方面的監管要求,供應商報告稱,安全PLC的訂單實現了兩位數的成長。
初始資本投入龐大且整合過程複雜
從專有DCS平台全面遷移到雲端歷史管理系統,每個站點的成本可能超過5,000萬美元,這與企業財務部門要求的投資回報週期不符。美國燃料和石化製造商協會的一項調查發現,62%的煉油廠由於切換風險以及試運行期間需要雙運作運行,正在推遲採用雲端歷史管理系統。對於通常依賴傳統現場現場匯流排網路且需要昂貴的協定轉換器才能連接到現代邊緣設備的棕地工廠而言,分階段檢修可能長達七年之久。
細分市場分析
到2025年,有線電視網路將佔據北美製程自動化市場61.19%的佔有率。這一主導地位源自於成熟的HART、PROFIBUS和Foundation Fieldbus迴路,這些迴路支援安全關鍵型連鎖和高速控制。然而,符合WirelessHART和ISA100.11a標準的設備預計將以3.11%的複合年成長率成長。這是因為本質安全認證的變送器允許在I類1區內部署,無需鋪設導管,從而節省了每米高達3000美元的成本。殼牌的諾科煉油廠部署了400個無線傳送器,在維持99.5%資料包可靠性的同時,將安裝時間縮短了60%。同時,邊緣閘道器對有線和無線資料進行規範化處理,使預測演算法能夠偵測感測器漂移,而無需考慮傳輸介質。 NFPA 70的修訂正式認可了這種共存模式,允許在風險評估中確認訊號完整性的情況下使用無線設備。
由於IEC 61511標準要求確定性延遲,因此對於緊急切斷閥、燃燒器管理系統和壓縮機防突波控制而言,有線連接仍然至關重要。因此,北美製程自動化市場採用混合拓樸結構,其中無線技術是關鍵有線迴路的補充,而非替代。目前,企劃團隊正在使用3D數位孿生模型來模擬射頻傳播,並在頒發熱作業許可證之前主動預防干擾。
2025年硬體銷售額佔比為58.43%,但預計到2031年,軟體將以3.56%的複合年成長率(CAGR)實現最高成長。運作在商用通用硬體上的開放標準控制器正在削弱專有DCS機櫃的定價權。基於訂閱的高級製程控制套件使營運商無需資本投資即可利用新功能。這一趨勢在紙漿和造紙廠尤其明顯,這些工廠透過實施多變量控制器,蒸氣需求降低了6%。同時,隨著製藥公司採用電子批記錄(EBR)以符合FDA的資料完整性指南,北美製造執行系統(MES)的製程自動化市場正在擴張。
升級到具備更強網路安全措施的SCADA系統,帶來了頻繁的更新迭代。這是因為許多中游管道系統仍然運作在不受支援的作業系統上,容易受到勒索軟體攻擊。供應商現在將SCADA核心嵌入到運行在安全Linux系統上的虛擬機器中,顯著縮短了修補週期,並支援快速災害復原。具備整合診斷功能的智慧感測器延長了校準週期,並加速了從資本設備向數位化生命週期服務的過渡。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人們越來越關注能源效率和降低營運成本。
- 安全儀器系統的需求日益成長
- 工業IoT平台的普及
- 向預測性維護和規範性維護分析的過渡
- 透過碳排放強度懲罰加速數位化流程控制
- 混合生產線中對無圍欄協作機器人的需求被低估了。
- 市場限制因素
- 初始資本投入龐大且整合過程複雜
- 現有系統互通性方面的挑戰
- 網路安全營運方面人員短缺
- 透過長期服務合約鎖定供應商,限制用戶更換供應商。
- 產業價值鏈分析
- 監管情勢和標準
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
- 美國和加拿大工業自動化關鍵細分市場分析
- 與疫情後復甦相關的主題(V型、溫和型、停滯型)
- 美國 - 基本和可變最終用戶性能
- 加拿大 - 基本和可變最終用戶的性能
- 供給側挑戰和經濟獎勵策略
第5章 市場規模與成長預測
- 透過通訊協定
- 有線
- 無線的
- 依系統類型
- 硬體
- SCADA
- 分散式控制系統(DCS)
- 可程式邏輯控制器(PLC)
- 人機介面(HMI)
- 製程安全系統
- 閥門執行器
- 電動機
- 感測器和發送器
- 軟體
- 高階製程控制(Arc、MVC、推理)
- 數據分析與報告撰寫
- 製造執行系統(MES)
- 其他軟體
- 硬體
- 按組件
- 硬體
- 軟體
- 服務
- 部署模式
- 現場
- 雲邊緣
- 按最終用戶行業分類
- 石油和天然氣
- 化工/石油化工
- 電力/公共產業
- 水和污水處理
- 飲食
- 紙漿和造紙
- 製藥
- 其他
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Abb Ltd.
- Siemens Ag
- Schneider Electric Se
- General Electric Company
- Rockwell Automation, Inc.
- Emerson Electric Co.
- Mitsubishi Electric Corporation
- Honeywell International Inc.
- Omron Corporation
- Fuji Electric Co., Ltd.
- Delta Electronics, Inc.
- Yokogawa Electric Corporation
- Phoenix Contact Gmbh & Co. Kg
- Bosch Rexroth Ag
- Beckhoff Automation Gmbh & Co. Kg
- Festo Se & Co. Kg
- Endress+Hauser Group Services Ag
- Aspen Technology, Inc.
- Aveva Group Plc
- Azbil Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America process automation market size is projected to expand from USD 40.60 billion in 2025 and USD 41.77 billion in 2026 to USD 47.94 billion by 2031, registering a CAGR of 2.79% between 2026 to 2031.
This report is Segmented by Communication Protocol (Wired, and Wireless), System Type (Hardware, and Software), Component (Hardware, Software, and Services), Deployment Mode (On-Premises, and Cloud and Edge), End-User Industry (Oil and Gas, Chemical and Petrochemical, Power and Utilities, Water and Wastewater, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
North America Process Automation Market Trends and Insights
Rising Focus on Energy-Efficiency and OpEx Reduction
Process manufacturers are recasting automation as an emissions-cutting tool. The U.S. Department of Energy's 2024 Industrial Decarbonization Roadmap outlines a 10%-15% reduction target for industrial energy intensity by 2030, prioritizing advanced process control and real-time optimization for chemical and refining assets. Canadian oil-sands operators face a legislated carbon price of CAD 170 per tonne by 2030, prompting the rollout of edge analytics that adjust combustion-air ratios and feedwater chemistry inside steam generators, trimming natural-gas use by up to 5% per barrel of synthetic crude. Payback periods under 18 months have been documented at Gulf Coast facilities that fine-tune distillation and heat-exchanger networks through multivariable controllers. These early wins are steering 2026 capital budgets toward digital debottlenecking rather than pure capacity expansions.
Heightened Demand for Safety-Instrumented Systems
A string of refinery and chemical-plant incidents in 2024-2025 elevated regulatory scrutiny. The U.S. Chemical Safety and Hazard Investigation Board linked several fires to inadequate safety-integrity-level verification, spurring retrofits of pneumatic trip systems with smart positioners that enable online diagnostics. Compliance with OSHA Process Safety Management now requires documented proof tests, driving purchases of integrated safety controllers that interface with existing DCS networks through secure OPC-UA gateways. Vendors report double-digit order growth for safety PLCs as pharmaceutical and food processors adopt the same architectures to satisfy sterile-fill and allergen-control mandates.
High Upfront CapEx and Integration Complexity
Comprehensive migrations from proprietary DCS platforms can exceed USD 50 million per site, a sum that clashes with payback horizons demanded by corporate finance teams. An American Fuel and Petrochemical Manufacturers survey found that 62% of refineries defer cloud historians because of cutover risks and the need for dual operations during commissioning. Brownfield plants often rely on legacy fieldbus networks that necessitate costly protocol converters when interfacing with modern edge devices, stretching project timelines to seven years when tackled in phased turnarounds.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Industrial IoT Platforms
- Shift Toward Predictive and Prescriptive Maintenance Analytics
- Operational Cybersecurity Talent Deficit
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wired networks held 61.19% of North America process automation market share in 2025. Their dominance stems from entrenched HART, PROFIBUS, and Foundation Fieldbus loops that anchor safety-critical interlocks and high-speed controls. WirelessHART and ISA100.11a devices, however, are forecast to expand at a 3.11% CAGR as intrinsic-safety-certified transmitters allow deployment inside Class I Division 1 areas, eliminating conduit runs that can cost USD 3,000 per meter. Shell's Norco refinery used 400 wireless transmitters to cut installation labour by 60% while maintaining 99.5% packet reliability. In parallel, edge gateways normalize wired and wireless data so that predictive algorithms detect sensor drift regardless of medium. Regulatory updates to NFPA 70 have formalized this coexistence by permitting wireless devices where risk assessments validate signal integrity.
Wired links remain indispensable for emergency shutdown valves, burner-management systems, and compressor anti-surge controls because IEC 61511 demands deterministic latency. Consequently, the North America process automation market retains a hybrid topology in which wireless augments, rather than replaces, critical hardwired loops. Project teams now model radio-frequency propagation in 3-D digital twins to pre-empt interference before issuing hot-work permits.
Hardware generated 58.43% of 2025 revenue, yet software is projected to register the leading 3.56% CAGR through 2031. Open-standard controllers running on commercial off-the-shelf hardware are eroding the pricing power of proprietary DCS cabinets. Subscription-based advanced process control suites mean operators can unlock new functionality without capital projects, a trend exemplified by pulp and paper mills that deploy multivariable controllers to shave 6% off steam demand. Meanwhile, North America process automation market size for manufacturing execution systems is rising as pharmaceutical firms embrace electronic batch records to comply with FDA data-integrity guidance.
Cyber-hardened SCADA upgrades form a brisk replacement cycle because many midstream pipeline systems still run on unsupported operating systems vulnerable to ransomware. Vendors now package SCADA kernels inside virtual machines hosted on hardened Linux, slashing patch windows and supporting rapid disaster recovery. Smart sensors with embedded diagnostics lengthen calibration intervals, reinforcing the shift from capital equipment toward digital lifecycle services.
Complete Report Scope:
- By Communication Protocol
- Wired
- Wireless
- By System Type
- Hardware
- Scada
- Distributed Control System (Dcs)
- Programmable Logic Controller (Plc)
- Human-Machine Interface (Hmi)
- Process Safety Systems
- Valves And Actuators
- Electric Motors
- Sensors And Transmitters
- Software
- Advanced Process Control (Arc, Mvc, Inferential)
- Data Analytics And Reporting
- Manufacturing Execution Systems (Mes)
- Other Software
- Hardware
- By Component
- Hardware
- Software
- Services
- By Deployment Mode
- On-Premises
- Cloud And Edge
- By End-User Industry
- Oil And Gas
- Chemical And Petrochemical
- Power And Utilities
- Water And Wastewater
- Food And Beverage
- Pulp And Paper
- Pharmaceutical
- Other End-User Industry
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Abb Ltd.
- Siemens Ag
- Schneider Electric Se
- General Electric Company
- Rockwell Automation, Inc.
- Emerson Electric Co.
- Mitsubishi Electric Corporation
- Honeywell International Inc.
- Omron Corporation
- Fuji Electric Co., Ltd.
- Delta Electronics, Inc.
- Yokogawa Electric Corporation
- Phoenix Contact Gmbh & Co. Kg
- Bosch Rexroth Ag
- Beckhoff Automation Gmbh & Co. Kg
- Festo Se & Co. Kg
- Endress+Hauser Group Services Ag
- Aspen Technology, Inc.
- Aveva Group Plc
- Azbil Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions And Market Definition
- 1.2 Scope Of The Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Focus On Energy-Efficiency And Opex Reduction
- 4.2.2 Heightened Demand For Safety-Instrumented Systems
- 4.2.3 Proliferation Of Industrial Iot Platforms
- 4.2.4 Shift Toward Predictive And Prescriptive Maintenance Analytics
- 4.2.5 Carbon-Intensity Penalties Accelerating Digital Process Control
- 4.2.6 Demand For Fenceless Cobots In Hybrid Process Lines (under-reported)
- 4.3 Market Restraints
- 4.3.1 High Upfront Capex And Integration Complexity
- 4.3.2 Brown-Field Interoperability Challenges
- 4.3.3 Operational Cybersecurity Talent Deficit
- 4.3.4 Long-Term Service-Contract Lock-Ins Limiting Vendor Switch
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape And Standards
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power Of Suppliers
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Threat Of New Entrants
- 4.7.4 Threat Of Substitutes
- 4.7.5 Intensity Of Competitive Rivalry
- 4.8 Impact Of Macroeconomic Factors On The Market
- 4.9 Industrial-Automation Hot-Spots Analysis (United States And Canada)
- 4.10 Pandemic Recovery Themes (V-Shape, Mid-Range, Slump)
- 4.11 United States - Base-Variable End-User Performance
- 4.12 Canada - Base-Variable End-User Performance
- 4.13 Supply-Related Challenges And Policy Stimulus
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Communication Protocol
- 5.1.1 Wired
- 5.1.2 Wireless
- 5.2 By System Type
- 5.2.1 Hardware
- 5.2.1.1 Scada
- 5.2.1.2 Distributed Control System (Dcs)
- 5.2.1.3 Programmable Logic Controller (Plc)
- 5.2.1.4 Human-Machine Interface (Hmi)
- 5.2.1.5 Process Safety Systems
- 5.2.1.6 Valves And Actuators
- 5.2.1.7 Electric Motors
- 5.2.1.8 Sensors And Transmitters
- 5.2.2 Software
- 5.2.2.1 Advanced Process Control (Arc, Mvc, Inferential)
- 5.2.2.2 Data Analytics And Reporting
- 5.2.2.3 Manufacturing Execution Systems (Mes)
- 5.2.2.4 Other Software
- 5.2.1 Hardware
- 5.3 By Component
- 5.3.1 Hardware
- 5.3.2 Software
- 5.3.3 Services
- 5.4 By Deployment Mode
- 5.4.1 On-Premises
- 5.4.2 Cloud And Edge
- 5.5 By End-User Industry
- 5.5.1 Oil And Gas
- 5.5.2 Chemical And Petrochemical
- 5.5.3 Power And Utilities
- 5.5.4 Water And Wastewater
- 5.5.5 Food And Beverage
- 5.5.6 Pulp And Paper
- 5.5.7 Pharmaceutical
- 5.5.8 Other End-User Industry
- 5.6 By Country
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share, Products And Services, Recent Developments)
- 6.4.1 Abb Ltd.
- 6.4.2 Siemens Ag
- 6.4.3 Schneider Electric Se
- 6.4.4 General Electric Company
- 6.4.5 Rockwell Automation, Inc.
- 6.4.6 Emerson Electric Co.
- 6.4.7 Mitsubishi Electric Corporation
- 6.4.8 Honeywell International Inc.
- 6.4.9 Omron Corporation
- 6.4.10 Fuji Electric Co., Ltd.
- 6.4.11 Delta Electronics, Inc.
- 6.4.12 Yokogawa Electric Corporation
- 6.4.13 Phoenix Contact Gmbh & Co. Kg
- 6.4.14 Bosch Rexroth Ag
- 6.4.15 Beckhoff Automation Gmbh & Co. Kg
- 6.4.16 Festo Se & Co. Kg
- 6.4.17 Endress+Hauser Group Services Ag
- 6.4.18 Aspen Technology, Inc.
- 6.4.19 Aveva Group Plc
- 6.4.20 Azbil Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space And Unmet-Need Assessment

 流程自動化與儀器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)歐洲過程自動化:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 零接觸配置市場:依設備類型、組件、網路複雜度、企業規模、最終用戶、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測工業製程自動化控制:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 流程自動化和儀器市場:按產品、產品類型、最終用戶和部署模式分類-2026-2032年全球市場預測
 2026年全球零接觸配置市場報告2026年全球工業製程自動化及控制系統市場報告2026年全球流程自動化與儀器市場報告流程自動化:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)流程自動化和儀器市場:按技術、最終用戶、儀器類型、自動化類型、國家和地區分類-全球產業分析、市場規模、市場佔有率及2025年至2032年預測