


 |
市場調查報告書
商品編碼
2124713
亞太地區內容服務平台:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Asia Pacific Content Services Platform - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
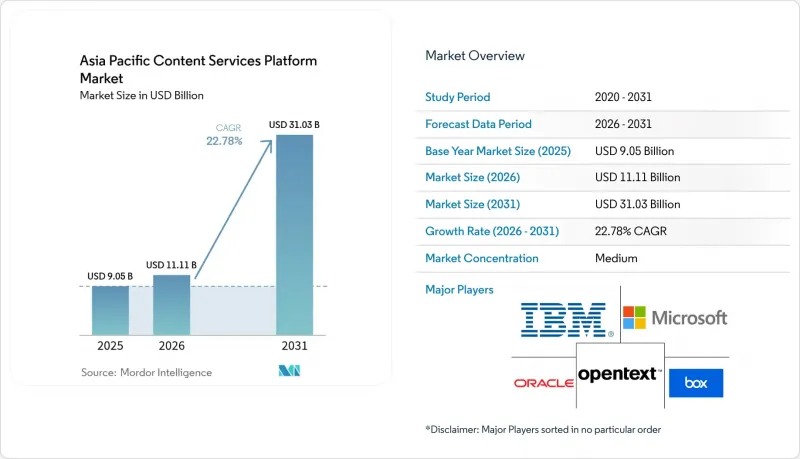
據 Mordor Intelligence 稱,亞太地區內容服務平台市場預計到 2026 年將達到 111.1 億美元,高於 2025 年的 90.5 億美元,預計到 2031 年將達到 310.3 億美元。
預計 2026 年至 2031 年的複合年成長率為 22.78%。
本報告按組件(解決方案/軟體、文件和記錄管理等)、部署模式(雲端、本地/混合部署)、組織規模(中小企業、大型企業)、最終用戶行業(銀行、金融服務和保險業、政府和公共部門等)以及地區進行細分。市場預測以美元計價。
亞太內容服務平台市場趨勢及洞察。
東協和印度掀起「雲端優先」投資熱潮。
從2019年到2024年,區域雲端基礎設施投資激增117%,推動了內容服務平台市場的發展,因為企業正從傳統儲存庫遷移到可擴展的SaaS套件。微軟在印尼投資17億美元建設雲端基礎設施,以及Office 365在亞太地區的兩位數成長,都清楚展現了廠商的決心。金融服務機構正在加速推進項目,以滿足強制性的雲端採用要求,從而推動了對合規文件工作流程的需求成長。新加坡的「先進數位解決方案」津貼計畫為專案成本提供50%的補貼,已幫助超過450個解決方案投入生產,類似的趨勢正在馬來西亞和泰國蔓延。公共部門的資金投入、超大規模資料中心業者的擴張以及同行的成功案例,共同促成了未來三年內雲端成為內容服務平台市場的預設架構。
內容智慧附加元件,融合了人工智慧生成技術
隨著平台從被動儲存向洞察引擎轉型,預計到2024年,各公司在生成式人工智慧方面的預算將成長兩倍,達到34億美元。 IBM的生成式人工智慧收入超過60億美元,這主要得益於亞太地區(APAC)對自動化分類、資訊遮罩和摘要技術的廣泛應用。 Adobe的Document Cloud整合了人工智慧功能以提取結構化數據,在2024年第三季創下了54.1億美元的收入紀錄,其中亞太地區貢獻了14.1%。 ServiceNow透過收購Raytion提高了搜尋準確率,這印證了人工智慧增強功能對於引領產業至關重要。早期採用者報告稱,人工處理時間減少了70%,投資報酬率顯著提升。這種轉變並非僅僅由功能主導;它正在重新定義買家的標準,並將內容服務平台市場重塑為一個「智慧知識網路」。
按居住的資料碎片
中國的《網路資料安全管理條例》將於2025年1月生效,該條例強制要求對「關鍵資料」進行跨境揭露審查和在地化處理,這將推高跨國公司軟體套件的合規成本。印度的《數位個人資料保護法》要求分階段獲得明確同意並進行在地化,迫使軟體架構重組。目前,供應商針對不同司法管轄區維護不同的版本,這削弱了規模經濟效益。中型企業缺乏實施多區域管治所需的預算,減緩了新規的採用速度。越南也在製定類似的法規,預示著市場將進一步分散。儘管內容服務平台市場持續成長,但這些政策正在減緩短期成長,並使成熟的本土企業獲得優勢。
細分市場分析
預計到2025年,軟體收入仍將佔總收入的61.02%,這主要得益於文件和記錄管理模組在內容服務平台市場合規性方面的重要性。然而,服務業的複合年成長率最高,達到23.95%,這主要得益於企業對專業整合和變更管理支援的需求。這項轉變凸顯了供應商生態系統中實施合作夥伴的重要性。 Hyland在海德拉巴的辦事處以及在馬來西亞為35,000名用戶部署DDMS 2.0系統,便是諮詢模式如何促成大規模公共部門合約的絕佳例證。人工智慧驅動的資料擷取創新正在縮短引進週期,而工作流程套件則正與流程自動化平台整合。隨著區域隱私法的日益嚴格,增強安全性和管治仍然是至關重要的要求。
這種向服務型模式的轉變將提高附加率和經常性收入,有利於那些擁有領域專業知識的供應商。合約模式正從許可和維護相結合的方式轉向基於結果的託管服務。因此,預計到2031年,與服務相關的內容服務平台市場規模將持續擴大。能夠提供持續最佳化和合規性更新的供應商有望鞏固其基本客群,提高轉換成本,並獲得更高的定價。
預計到2025年,雲端解決方案將佔據內容服務平台市場69.78%的佔有率,複合年成長率(CAGR)為24.99%。企業重視付費使用制和與其整體數位化藍圖相契合的無縫API整合。微軟4億份付費Office 365許可證充分證明了該平台在以內容為中心的協作領域的吸引力。儘管混合模式和本地部署模式在嚴格監管的行業中仍然存在,但即使是這些用戶也開始採用雲端連接器進行外部協作。供應商目前正專注於區域存取點(PoP)和自主雲端解決方案,以滿足資料本地化要求。
隨著超大規模資料中心業者資料中心節點的擴展和基於市場的收費模式簡化採購流程,經濟效益正在進一步提升。 Adobe Document Cloud 利用套件層級的一致性,反映了買家對統一的雲端原生生態系統的偏好。因此,隨著中小企業採用率的激增以及大型企業逐步遷移工作負載,預計到 2031 年,與雲端採用相關的內容服務平台市場規模將超過 80.54%。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 「雲端優先」的消費熱潮正在席捲東協和印度。
- 利用生成式人工智慧的內容智慧附加元件
- 為中小企業提供數位化工作流程補貼(例如新加坡的DSG津貼)
- 支援5G的邊緣內容處理,適用於現場作業
- 日本和韓國關於強制使用電子帳單的規定
- 碳核算內容儲存的採購標準
- 市場限制因素
- 由於資料居住要求導致的網路碎片化(中國的CSL、印度的DPDP)
- 一線城市以外地區超大規模資料中心容量短缺
- 低程式碼工作流程設計方面的技能差距
- 中型企業採購負責人對訂閱服務的疲勞感日益加劇。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按組件
- 解決方案/軟體
- 文件和記錄管理
- 數據收集
- 工作流程/個案管理
- 資訊安全與管治
- 其他解決方案
- 服務
- 解決方案/軟體
- 按部署模式
- 雲
- 本地部署/混合部署
- 按組織規模
- 中小企業
- 大公司
- 按最終用戶行業分類
- BFSI
- 政府/公共部門
- 醫療保健和生命科學
- IT/通訊
- 零售與電子商務
- 運輸/物流
- 其他行業
- 國家
- 中國
- 印度
- 日本
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Adobe Inc.
- Alfresco Software Ltd.(a Hyland company)
- Box, Inc.
- Fabasoft AG
- Fujifilm Business Innovation Corp.
- Hitachi Vantara LLC
- Hewlett Packard Enterprise
- Hyland Software, Inc.
- IBM Corporation
- iManage, LLC
- Kyocera Document Solutions Inc.
- Laserfiche, Inc.
- M-Files Corporation
- Microsoft Corporation
- Nintex Global Ltd.
- Objective Corporation Ltd.
- OpenText Corporation
- Oracle Corporation
- SaaSplaza(SoftwareOne)
- Tata Consultancy Services Ltd.(TCS BaNCS Content Suite)
- Tencent Cloud(TCI ECM)
第7章 市場機會與未來展望
According to Mordor Intelligence, the content services platform market size in Asia-Pacific in 2026 is estimated at USD 11.11 billion, growing from 2025 value of USD 9.05 billion with 2031 projections showing USD 31.03 billion, growing at 22.78% CAGR over 2026-2031.
This report is Segmented by Component (Solution/Software, Including Document and Records Management, and More), Deployment Model (Cloud, On-premise/Hybrid), Organization Size (SMEs, Large Enterprises), End-User Industry (BFSI, Government and Public Sector, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD)
Asia Pacific Content Services Platform Market Trends and Insights
Cloud-first spending boom across ASEAN and India
Regional cloud infrastructure investment surged 117% between 2019 and 2024, lifting the content services platform market as businesses traded legacy repositories for scalable SaaS suites.Microsoft's USD 1.7 billion Indonesian cloud buildout and double-digit Office 365 APAC growth illustrate vendor commitment. Financial services institutions are front-loading projects to satisfy cloud-adoption mandates, widening demand for compliant document workflows. Singapore's Advanced Digital Solutions grants that cover 50% of project costs have guided more than 450 solutions into production, driving replication across Malaysia and Thailand. The compounding influence of public-sector funding, hyperscaler expansion, and peer success stories positions cloud as the default architecture for the content services platform market over the next three years.
Generative-AI infused content intelligence add-ons
Enterprises are tripling Gen-AI budgets to USD 3.4 billion in 2024, steering platforms from passive storage toward insight engines. IBM exceeded USD 6 billion in Gen-AI revenue on the strength of APAC deployments that automate classification, redaction, and summary creation. Adobe's Document Cloud integrated AI features that extract structured data, supporting record Q3 2024 revenue of USD 5.41 billion, with APAC at 14.1% of turnover. ServiceNow supplemented search precision through the Raytion acquisition, confirming that AI enrichment is table-stakes for leadership. Early adopters report 70% decreases in manual processing time, validating positive ROI. The shift is not merely feature-led-it reshapes buyer criteria, repositioning the content services platform market as an intelligent knowledge fabric.
Data-residency splinter-net
China's Network Data Security Management Regulations effective January 2025 force cross-border disclosure reviews and local processing for "important data," raising compliance cost for multinational suites. India's Digital Personal Data Protection Act demands explicit consent layers and localization that reshape software architecture. Vendors now maintain variant builds per jurisdiction, eroding economies of scale. Mid-market firms lack budgets for multiregional governance, slowing adoption. Vietnam is drafting similar rules, signaling more fragmentation. While the content services platform market continues to grow, these policies clip near-term velocity and favor local incumbents.
Other drivers and restraints analyzed in the detailed report include:
- SME digital-workflow subsidies
- 5G-enabled edge content processing for field operations
- Scarcity of hyperscale datacenter capacity outside tier-1 cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software continued to anchor 61.02% of 2025 revenue, led by document and records management modules essential for compliance in the content services platform market. However, services posted the fastest 23.95% CAGR as enterprises sought expert integration and change-management support. The shift elevates implementation partners in vendor ecosystems. Hyland's Hyderabad hub and rollout of DDMS 2.0 to 35 000 Malaysian users illustrate how consultative delivery unlocks large public-sector deals. AI-driven data-capture innovations are compressing onboarding cycles while workflow suites converge with process-automation platforms. Security and governance upgrades remain non-negotiable as regional privacy laws tighten.
The services pivot translates into higher attach rates and recurring revenue, favoring vendors that embed domain expertise. Engagement models are migrating from license plus maintenance toward outcome-based managed services. As a result, the content services platform market size tied to services is projected to widen its contribution through 2031. Vendors that deliver continuous optimization and regulatory updates are expected to consolidate accounts, raising switching costs and supporting premium pricing.
Cloud options secured 69.78% of the 2025 content services platform market share and are forecast for 24.99% CAGR. Enterprises appreciate consumption-based pricing and seamless API integrations that align with broader digital roadmaps. Microsoft's 400 million paid Office 365 seats demonstrate platform pull for content-centric collaboration. Hybrid and on-premise models persist within heavily regulated verticals, yet even these users adopt cloud connectors for external collaboration. Vendors now emphasize regional PoPs and sovereign-cloud offsets to satisfy data-locality clauses.
The economic case deepens as hyperscaler nodes proliferate and marketplace billing streamlines procurement. Adobe's Document Cloud thrives on cross-suite coherence, mirroring buyer preference for unified, cloud-native ecosystems. Consequently, the content services platform market size linked to cloud deployments is expected to eclipse 80.54% by 2031 as SME adoption surges and large enterprises migrate phased workloads.
Complete Report Scope:
- By Component
- Solution / Software
- Document and Records Management
- Data Capture
- Workflow / Case Management
- Information Security and Governance
- Other Solutions
- Services
- Solution / Software
- By Deployment Model
- Cloud
- On-premise / Hybrid
- By Organization Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
- By End-user Industry
- BFSI
- Government and Public Sector
- Healthcare and Life Sciences
- IT and Telecom
- Retail and E-commerce
- Transportation and Logistics
- Other Industries
- By Country
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Adobe Inc.
- Alfresco Software Ltd. (a Hyland company)
- Box, Inc.
- Fabasoft AG
- Fujifilm Business Innovation Corp.
- Hitachi Vantara LLC
- Hewlett Packard Enterprise
- Hyland Software, Inc.
- IBM Corporation
- iManage, LLC
- Kyocera Document Solutions Inc.
- Laserfiche, Inc.
- M-Files Corporation
- Microsoft Corporation
- Nintex Global Ltd.
- Objective Corporation Ltd.
- OpenText Corporation
- Oracle Corporation
- SaaSplaza (SoftwareOne)
- Tata Consultancy Services Ltd. (TCS BaNCS Content Suite)
- Tencent Cloud (TCI ECM)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-first spending boom across ASEAN and India
- 4.2.2 Generative-AI infused content intelligence add-ons
- 4.2.3 SME digital-workflow subsidies (e.g., Singapore DSG grants)
- 4.2.4 5G-enabled edge content processing for field operations
- 4.2.5 Mandatory e-invoicing regulations in Japan and Korea
- 4.2.6 Carbon-accounted content storage buying criteria
- 4.3 Market Restraints
- 4.3.1 Data-residency splinter-net (China CSL, India DPDP)
- 4.3.2 Scarcity of in-region hyperscale datacenter capacity outside tier-1 cities
- 4.3.3 Skills gap in low-code workflow design
- 4.3.4 Rising subscription fatigue among mid-market buyers
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solution / Software
- 5.1.1.1 Document and Records Management
- 5.1.1.2 Data Capture
- 5.1.1.3 Workflow / Case Management
- 5.1.1.4 Information Security and Governance
- 5.1.1.5 Other Solutions
- 5.1.2 Services
- 5.1.1 Solution / Software
- 5.2 By Deployment Model
- 5.2.1 Cloud
- 5.2.2 On-premise / Hybrid
- 5.3 By Organization Size
- 5.3.1 Small and Medium-sized Enterprises (SMEs)
- 5.3.2 Large Enterprises
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Government and Public Sector
- 5.4.3 Healthcare and Life Sciences
- 5.4.4 IT and Telecom
- 5.4.5 Retail and E-commerce
- 5.4.6 Transportation and Logistics
- 5.4.7 Other Industries
- 5.5 By Country
- 5.5.1 China
- 5.5.2 India
- 5.5.3 Japan
- 5.5.4 South Korea
- 5.5.5 Australia and New Zealand
- 5.5.6 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Alfresco Software Ltd. (a Hyland company)
- 6.4.3 Box, Inc.
- 6.4.4 Fabasoft AG
- 6.4.5 Fujifilm Business Innovation Corp.
- 6.4.6 Hitachi Vantara LLC
- 6.4.7 Hewlett Packard Enterprise
- 6.4.8 Hyland Software, Inc.
- 6.4.9 IBM Corporation
- 6.4.10 iManage, LLC
- 6.4.11 Kyocera Document Solutions Inc.
- 6.4.12 Laserfiche, Inc.
- 6.4.13 M-Files Corporation
- 6.4.14 Microsoft Corporation
- 6.4.15 Nintex Global Ltd.
- 6.4.16 Objective Corporation Ltd.
- 6.4.17 OpenText Corporation
- 6.4.18 Oracle Corporation
- 6.4.19 SaaSplaza (SoftwareOne)
- 6.4.20 Tata Consultancy Services Ltd. (TCS BaNCS Content Suite)
- 6.4.21 Tencent Cloud (TCI ECM)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 內容服務平台:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)品牌內容服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 內容服務平台市場-2026-2032年全球市場預測
 2026年全球內容服務平台市場報告
 全球內容服務平台市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 內容服務平台市場規模、佔有率和成長分析(按組件、企業規模、部署類型、業務功能、產業和地區分類)-2026-2033年產業預測多語言字幕服務市場按服務類型、語言對、文件格式、字幕類型、垂直行業和配銷通路分類 - 全球預測 2025-2030