


 |
市場調查報告書
商品編碼
2124698
印度工業感測器和變送器:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)India Industrial Sensors And Transmitters - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
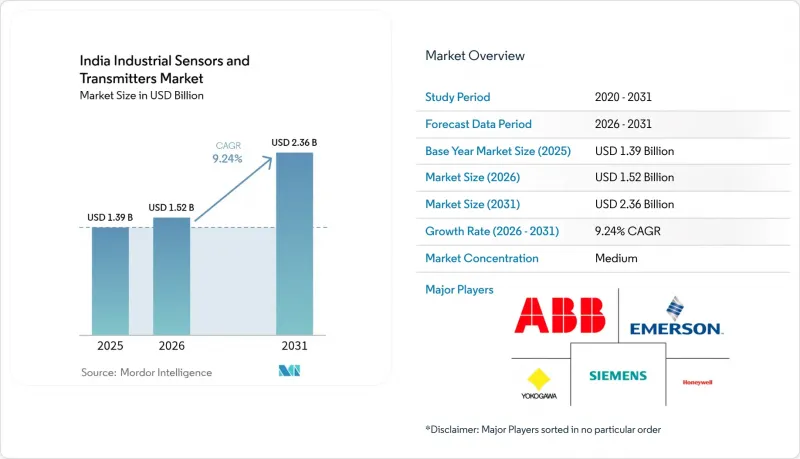
根據 Mordor Intelligence 預測,印度工業感測器和變送器市場規模將從 2025 年的 13.9 億美元成長到 2026 年的 15.2 億美元,到 2031 年將達到 23.6 億美元,2026 年至 2031 年的複合年成長率為 9.24%。
本報告按感測器類型(流量、溫度、壓力、液位等)、終端用戶行業(發電/公共產業、石油天然氣等)、外形規格/安裝方式(接觸式/直插式和非接觸式/夾裝式/遠程序)、通訊技術(有線、工業乙太網、無線)以及地區進行細分。市場預測以美元計價。
印度工業感測器和變送器市場的趨勢和洞察
政府的「印度製造」和生產連結獎勵計畫計畫(PLI)正在促進智慧工廠的發展。
價值7.6萬印度盧比(約91億美元)的績效獎勵正在激勵那些持續進行資本投資和生產成長的製造商,並促使採購決策轉向國產感測器組件。跨國公司正積極回應,建造垂直整合的工廠,以降低物流成本、縮短前置作業時間,並調整產品線以適應印度的營運環境。國產組件比例的不斷提高也有助於保護印度工業感測器和變送器市場的買家免受外匯波動的影響。中期來看,本地供應商生態系統的進一步加強可望降低先進智慧感測器的價格溢價,並進一步加速中型製造商的採用。
擴大工業4.0在各製造企業的應用
汽車製造商向電動車轉型、電子組裝最佳化生產線切換、資本財製造商實施預測分析,所有這些企業都對即時狀態數據有著通用的需求。一位工廠經理表示,將振動、溫度和電能品質感測器整合到生產設備中,可使停機時間減少高達 30%,並顯著提高單位面積產量。像海德拉巴物料輸送工廠廣泛應用DAIFUKU CO. LTD.)感測器的成功案例,正激勵著其他二級供應商開展類似項目,以維護其在原始設備製造商(OEM)中的聲譽。因此,印度工業感測器和變送器市場正受益於良性循環:性能的提升促使企業增加感測器預算,而部署規模的擴大又會產生更多數據,進而催生更高附加價值的分析服務。
使用先進智慧感測器的維修需要大量的資金投入。
整合診斷功能和行動通訊模組的智慧單元價格通常是傳統產品的三倍,而對整個工廠進行全面維修可能需要200萬至500萬美元的新支出。利潤率低的中小型企業不願將資金投入長達五年的投資回收期,這導致他們無法獲得原本能夠推動印度工業感測器和發射器市場發展的大訂單。雖然政府提供的低利率貸款和加速折舊方案在一定程度上抵消了高昂的前期成本,但除一線工業園區外,這些方案的宣傳力度仍然不足。
細分市場分析
預計到2025年,壓力測量儀器的出貨量將佔總出貨量的27.12%,凸顯了其在碳氫化合物加工、化學合成和發電鍋爐安全高效運作中的關鍵作用。隨著監管機構對高壓管道的安全裕度提出更嚴格的要求,印度工業壓力測量感測器和變送器市場預計將穩定成長。製造商不斷拓展產品線,推出防爆型和差壓型產品,以適應印度煉油廠中各種不同的黏度和腐蝕性環境。同時,受汽車、水泥和鋼鐵廠維護營運數位化項目的推動,振動和狀態監測感測器的年複合成長率預計將達到10.95%,這些項目旨在顯著減少意外運作。提供感測器和預測分析儀表板一體化解決方案的供應商正在確保穩定的業務收益來源,並提升其在印度工業感測器和變送器市場的整體價值獲取能力。
除了前兩大類之外,溫度探頭在製藥業的滅菌迴路和乳製品巴氏殺菌生產線中也保持著強勁的需求,因為精確的溫度控制可以防止批次劣化。流量感測器在市政智慧水務計畫資助的廢水處理和海水淡化計畫中得到了越來越廣泛的應用。液位感測器正從單一料倉的監控轉向整合式庫存管理系統,從而實現基於ERP的原料可視性。氣體和濕度感測器的應用範圍正從無塵室擴展到新一代資料中心,穩定的空氣品質可以延長伺服器的使用壽命。在所有類別中,原始設備製造商(OEM)都在大力推廣多參數平台,將多種感測方法整合到單一機殼中,這不僅降低了安裝難度,也提高了印度工業感測器和變送器市場的平均售價。
參與碳氫化合物價值鏈的企業預計在2025年佔總銷售額的26.15%,這主要得益於印度石油公司(Indian Oil Corporation)等資本項目,例如其價值24,000卡路里(約28.8億美元)的石化業務擴張。從SIL認證的壓力變送器到可燃性氣體探測器等安全儀器設備,在油氣行業支出中佔據很大比例,而環保部門對排放物的強制性持續監測也進一步擴大了印度的工業感測器和變送器市場。然而,在預測期內,製藥和生物技術設施預計將實現11.02%的複合年成長率,隨著疫苗和生物製藥企業在冷鏈儲存、冷凍乾燥室和專用潔淨室等場所擴展其符合GMP標準的感測器網路,市場佔有率差距預計將會縮小。
在公共產業,智慧電錶和變電站自動化正在實施,推動了電力品質感測器和光纖溫度迴路在變壓器中的應用。石油化學、化學和化學肥料產業正利用多變量感測器監測交聯反應參數,以最佳化加工能力。食品飲料加工企業正在部署雲端連接感測器,以實現從混合到包裝的即時可追溯性,超越了HACCP清單的範疇。用水和污水企業正在採用夾裝式超音波流量計,以避免連接作業期間的服務中斷。金屬和礦業公司正在引入耐環境振動探頭,以預測輸送機和球磨機驅動系統的磨損。這些不同行業的共同作用,正在使印度的工業感測器和變送器市場多元化,減少對特定產品週期的過度依賴。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府的「印度製造」計劃和生產連結獎勵計畫計畫(PLI)正在促進智慧工廠的發展。
- 擴大工業4.0在各製造企業的應用
- 醫藥、食品和飲料產業的品質導向法規
- 公共產業和流程工業的強制性能源效率要求
- 資料中心的快速成長帶動了對高精度暖通空調感測器的需求不斷成長。
- 感測器組件供應鏈本地化
- 市場限制因素
- 使用先進智慧感測器的維修需要大量資金投入。
- 與互通性和舊有系統整合相關的挑戰
- 熟練測量技術人員短缺
- 對半導體進口的依賴導致了供應瓶頸。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟趨勢對市場的影響
第5章 市場規模與成長預測
- 依感測器類型
- 流速
- 溫度
- 壓力
- 等級
- 振動/狀態監測
- 氣體和濕度
- 其他感測器類型
- 按最終用戶行業分類
- 發電和公共產業
- 石油和天然氣
- 石油化學產品、化學品、化肥
- 食品/飲料
- 生命科學(製藥、生技、醫療設備)
- 供水/污水處理
- 金屬和採礦
- 其他製造業(紡織、紙漿及造紙、汽車等)
- 外形規格/安裝方式
- 聯絡類型/線上
- 非接觸式/夾式/遠程式
- 透過通訊技術
- 有線連接(HART、MODBUS、PROFIBUS 等)
- 工業乙太網(PROFINET、EtherNet/IP 等)
- 無線(ISA100、WirelessHART、Wi-SUN、LPWAN)
- 按地區
- 印度北部
- 西印度群島
- 南印度
- 印度東部和東北部
- 印度中部
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB India Limited
- Honeywell Automation India Limited
- Siemens Limited
- Yokogawa India Ltd.
- Emerson Process Management(India)Pvt. Ltd.
- Schneider Electric Systems India Pvt. Ltd.
- Endress+Hauser(India)Automation Instruments Pvt. Ltd.
- WIKA Instruments India Pvt. Ltd.
- Pepperl+Fuchs(India)Pvt. Ltd.
- Turck India Automation Pvt. Ltd.
- Omron Automation Private Limited
- Bosch Rexroth(India)Pvt. Ltd.
- Vega India Level and Pressure Measurement Pvt. Ltd.
- Baumer Technologies India Pvt. Ltd.
- Phoenix Contact(India)Pvt. Ltd.
- ifm electronic India Pvt. Ltd.
- Rockwell Automation India Pvt. Ltd.
- SICK India Pvt. Ltd.
- Vishay Components India Private Ltd.
- EXA Thermometrics India Pvt. Ltd.
- SRI Electronics
- Sensorex, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the India industrial sensors and transmitters market size is expected to grow from USD 1.39 billion in 2025 to USD 1.52 billion in 2026 and is forecast to reach USD 2.36 billion by 2031 at 9.24% CAGR over 2026-2031.
This report is Segmented by Sensor Type (Flow, Temperature, Pressure, Level, and More), End-User Industry (Power Generation and Utilities, Oil and Gas, and More), Form Factor/Installation (Contact/In-line and Non-contact/Clamp-on/Remote), Communication Technology (Wired, Industrial Ethernet, and Wireless), and Region. The Market Forecasts are Provided in Terms of Value (USD).
India Industrial Sensors And Transmitters Market Trends and Insights
Government "Make-in-India" and PLI Schemes Catalyzing Smart Factories
Performance-linked incentives worth INR 76,000 crore (USD 9.1 billion) reward manufacturers that demonstrate sustained capital expenditure and output growth, tilting sourcing decisions toward domestically produced sensor components. Multinationals have responded by building vertically integrated plants that reduce logistics costs, compress lead times, and adapt product lines to Indian operating conditions. Larger domestic content also shields buyers in the India industrial sensors and transmitters market from exchange rate volatility. Over the medium term, a denser local vendor ecosystem is likely to compress price premiums for advanced smart sensors, further accelerating adoption across mid-tier manufacturers.
Rising Industry 4.0 Adoption Across Discrete Manufacturing
Automakers transitioning to electric vehicles, electronics assemblers optimizing line changeovers, and capital-goods makers deploying predictive analytics share a common need for real-time condition data. Factory leaders report up to 30% downtime reduction after embedding vibration, thermal, and power-quality sensors into production assets, which translates to notably higher throughput per square foot. Success stories such as Daifuku's sensor-rich material-handling plant in Hyderabad catalyze copy-cat projects among Tier-2 suppliers keen to preserve OEM rankings. The India industrial sensors and transmitters market will therefore benefit from a virtuous loop: performance gains justify larger sensor budgets, and larger installations yield more data, which in turn feeds higher-value analytics services.
High CAPEX of Advanced Smart-Sensor Retrofits
Smart units with built-in diagnostics and wireless modules often cost triple the price of legacy counterparts, and comprehensive facility conversions can require USD 2-5 million in fresh outlays. SMEs with slim margins hesitate to lock capital into five-year payback horizons, delaying sizable orders that would otherwise lift the India industrial sensors and transmitters market. Government low-interest loans and accelerated depreciation allowances partially offset sticker shock, yet awareness of such schemes remains patchy outside tier-one industrial parks.
Other drivers and restraints analyzed in the detailed report include:
- Quality-Centric Regulations in Pharma and Food and Beverage sectors
- Energy-Efficiency Mandates for Utilities and Process Industries
- Interoperability and Legacy System Integration Issues
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pressure devices accounted for 27.12% of 2025 shipments, underscoring their foundational role in safe and efficient hydrocarbon processing, chemical synthesis, and power-generation boiler operations. The India industrial sensors and transmitters market size tied to pressure measurement is expected to compound at a steady clip as regulatory bodies enforce tighter safety margins in high-pressure pipelines. Manufacturers continue to widen portfolios with explosion-proof and differential configurations suited to the diverse viscosity and corrosiveness profiles seen in Indian refineries. Meanwhile, vibration and condition-monitoring sensors are set to post an 10.95% CAGR through 2031, propelled by maintenance digitization programs that aim to slash unplanned downtimes across automotive, cement, and steel plants. Suppliers that bundle sensors with predictive analytics dashboards secure annuity-style service revenue streams, strengthening overall value capture within the India industrial sensors and transmitters market.
Beyond the top two categories, temperature probes retain durable demand in pharma sterilization loops and dairy pasteurization lines where precise thermal control guards against batch spoilage. Flow sensors enjoy rising penetration in effluent treatment and desalination projects funded by municipal smart-water schemes. Level sensors migrate from discrete silo monitoring toward integrated inventory-management suites, providing ERP-ready feedstock visibility. Gas and humidity sensing extend from cleanrooms into next-generation data centers, where consistent air quality boosts server lifespan. Across all classes, OEMs increasingly push multi-parameter platforms that condense several sensing modalities into a single housing, lowering installation labor while expanding the India industrial sensors and transmitters market's average selling price.
Hydrocarbon value-chain participants commanded 26.15% of 2025 revenue, anchored by capital projects such as Indian Oil Corporation's INR 24,000 crore (USD 2.88 billion) petrochemical expansion. Safety instrumentation ranging from SIL-rated pressure transmitters to combustible-gas detectors forms the bulk of oil-and-gas outlays, with environmental authorities mandating continuous emissions monitoring that further enlarges the India industrial sensors and transmitters market. Over the forecast period, however, pharma and biotech facilities are poised for an 11.02% CAGR, narrowing the share gap as vaccine and biologics plants scale GMP-compliant sensor grids spanning cold-chain storage, lyophilization chambers, and classified cleanrooms.
Utilities deploy smart metering and sub-station automation, driving uptake of power-quality transducers and fiber-optic temperature loops in transformers. Petrochemicals, chemicals, and fertilizers chase throughput optimization via multivariable sensors that monitor cross-linked reaction parameters. Food and beverage processors move beyond HACCP checklists, integrating cloud-linked sensors for real-time traceability from blending to packaging. Water and wastewater operators embrace clamp-on ultrasonic flow meters that eliminate service disruptions during tie-ins. Metals and mining companies adopt ruggedized vibration probes to anticipate drivetrain wear in conveyors and ball mills. Collectively, these verticals diversify the India industrial sensors and transmitters market, reducing over-reliance on any single commodity cycle.
Complete Report Scope:
- By Sensor Type
- Flow
- Temperature
- Pressure
- Level
- Vibration/Condition-Monitoring
- Gas and Humidity
- Other Sensor Types
- By End-user Industry
- Power Generation and Utilities
- Oil and Gas
- Petrochemicals, Chemicals and Fertilizers
- Food and Beverage
- Life Sciences (Pharma, Biotech and Medical Devices)
- Water and Waste-water
- Metals and Mining
- Other Manufacturing (Textile, Pulp and Paper, Auto, etc.)
- By Form Factor/Installation
- Contact/In-line
- Non-contact/Clamp-on/Remote
- By Communication Technology
- Wired (HART, MODBUS, PROFIBUS, etc.)
- Industrial Ethernet (PROFINET, EtherNet/IP, etc.)
- Wireless (ISA100, WirelessHART, Wi-SUN, LPWAN)
- By Region
- North India
- West India
- South India
- East and North-East India
- Central India
List of Companies Covered in this Report:
- ABB India Limited
- Honeywell Automation India Limited
- Siemens Limited
- Yokogawa India Ltd.
- Emerson Process Management (India) Pvt. Ltd.
- Schneider Electric Systems India Pvt. Ltd.
- Endress+Hauser (India) Automation Instruments Pvt. Ltd.
- WIKA Instruments India Pvt. Ltd.
- Pepperl+Fuchs (India) Pvt. Ltd.
- Turck India Automation Pvt. Ltd.
- Omron Automation Private Limited
- Bosch Rexroth (India) Pvt. Ltd.
- Vega India Level and Pressure Measurement Pvt. Ltd.
- Baumer Technologies India Pvt. Ltd.
- Phoenix Contact (India) Pvt. Ltd.
- ifm electronic India Pvt. Ltd.
- Rockwell Automation India Pvt. Ltd.
- SICK India Pvt. Ltd.
- Vishay Components India Private Ltd.
- EXA Thermometrics India Pvt. Ltd.
- SRI Electronics
- Sensorex, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government "Make-in-India" and PLI schemes catalyzing smart factories
- 4.2.2 Rising Industry 4.0 adoption across discrete manufacturing
- 4.2.3 Quality-centric regulations in pharma and Food and Beverage sectors
- 4.2.4 Energy-efficiency mandates for utilities and process industries
- 4.2.5 Data-center boom demanding precision HVAC sensors
- 4.2.6 Localization of sensor component supply chains
- 4.3 Market Restraints
- 4.3.1 High CAPEX of advanced smart-sensor retrofits
- 4.3.2 Interoperability and legacy system integration issues
- 4.3.3 Shortage of skilled instrumentation technicians
- 4.3.4 Semiconductor import dependence causing supply bottlenecks
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Sensor Type
- 5.1.1 Flow
- 5.1.2 Temperature
- 5.1.3 Pressure
- 5.1.4 Level
- 5.1.5 Vibration/Condition-Monitoring
- 5.1.6 Gas and Humidity
- 5.1.7 Other Sensor Types
- 5.2 By End-user Industry
- 5.2.1 Power Generation and Utilities
- 5.2.2 Oil and Gas
- 5.2.3 Petrochemicals, Chemicals and Fertilizers
- 5.2.4 Food and Beverage
- 5.2.5 Life Sciences (Pharma, Biotech and Medical Devices)
- 5.2.6 Water and Waste-water
- 5.2.7 Metals and Mining
- 5.2.8 Other Manufacturing (Textile, Pulp and Paper, Auto, etc.)
- 5.3 By Form Factor/Installation
- 5.3.1 Contact/In-line
- 5.3.2 Non-contact/Clamp-on/Remote
- 5.4 By Communication Technology
- 5.4.1 Wired (HART, MODBUS, PROFIBUS, etc.)
- 5.4.2 Industrial Ethernet (PROFINET, EtherNet/IP, etc.)
- 5.4.3 Wireless (ISA100, WirelessHART, Wi-SUN, LPWAN)
- 5.5 By Region
- 5.5.1 North India
- 5.5.2 West India
- 5.5.3 South India
- 5.5.4 East and North-East India
- 5.5.5 Central India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB India Limited
- 6.4.2 Honeywell Automation India Limited
- 6.4.3 Siemens Limited
- 6.4.4 Yokogawa India Ltd.
- 6.4.5 Emerson Process Management (India) Pvt. Ltd.
- 6.4.6 Schneider Electric Systems India Pvt. Ltd.
- 6.4.7 Endress+Hauser (India) Automation Instruments Pvt. Ltd.
- 6.4.8 WIKA Instruments India Pvt. Ltd.
- 6.4.9 Pepperl+Fuchs (India) Pvt. Ltd.
- 6.4.10 Turck India Automation Pvt. Ltd.
- 6.4.11 Omron Automation Private Limited
- 6.4.12 Bosch Rexroth (India) Pvt. Ltd.
- 6.4.13 Vega India Level and Pressure Measurement Pvt. Ltd.
- 6.4.14 Baumer Technologies India Pvt. Ltd.
- 6.4.15 Phoenix Contact (India) Pvt. Ltd.
- 6.4.16 ifm electronic India Pvt. Ltd.
- 6.4.17 Rockwell Automation India Pvt. Ltd.
- 6.4.18 SICK India Pvt. Ltd.
- 6.4.19 Vishay Components India Private Ltd.
- 6.4.20 EXA Thermometrics India Pvt. Ltd.
- 6.4.21 SRI Electronics
- 6.4.22 Sensorex, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 亞太地區工業感測器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)工業感測器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 工業感測器市場-2026-2032年全球市場預測
 2026-2030年全球工業感測器市場
 工業感測器和自動化市場預測至2034年—按感測器類型、技術、產業、應用、最終用戶和地區分類的全球分析
 工業感測器市場-全球市場規模、佔有率、趨勢、機會和預測:按產品、應用、地區和競爭對手分類,2021-2031年美國工業感測器:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 工業感測器市場規模、佔有率和趨勢分析報告:按感測器類型、技術、最終用途、地區和細分市場預測(2025-2033 年)
 工業感測器市場:按檢測方法、終端用戶產業和地區分類
 工業感測器市場機會、成長要素、產業趨勢分析及2026年至2035年預測