


 |
市場調查報告書
商品編碼
2124816
微處理器:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Microprocessor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年微處理器市值為 1091.2 億美元,預計到 2031 年將達到 1562.5 億美元,而 2026 年為 1158.5 億美元,預測期(2026-2031 年)的複合年成長率為 6.17%。
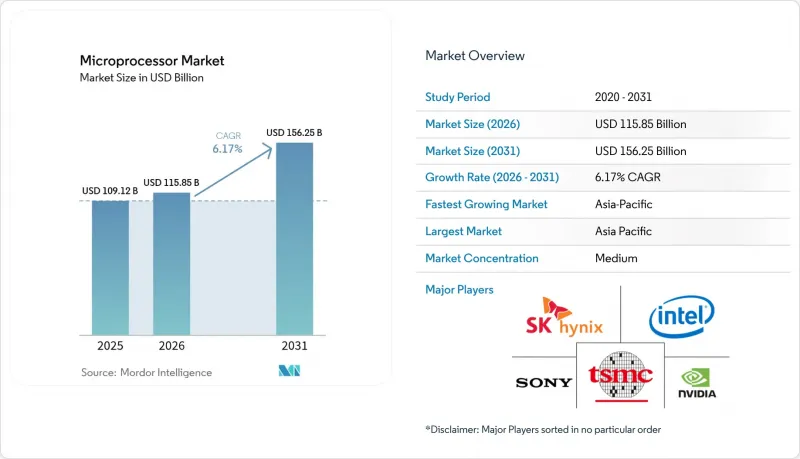
本報告依處理器類型(CPU、GPU、APU、FPGA、DSP、ASIC)、指令集架構(x86、Arm、RISC-V、Power、MIPS 等)、製造流程(28nm 以上、22-16nm、14-10nm、7-6nm、5-4nm等)、應用(家用電子電器、資料中心和企業伺服器、航太和國防、其他)以及地區(北美、南美、歐洲、亞太、中東和非洲)進行分類。
全球微處理器市場趨勢與洞察
對高效能、高能源效率處理器的需求日益成長。
兼具高吞吐量和低功耗的處理器的需求,在2024年和2025年持續影響著各廠商的產品藍圖。隨著資料中心營運商將整體擁有成本 (TCO) 置於優先地位,設計人員最佳化了每瓦效能,並整合封裝內記憶體以降低延遲。消費性電子設備製造商也緊跟其後,致力於研發能夠支援AI推理且不會因過熱而降頻的節能晶片。向3nm以下微型化製程的推進,使得漏電流成為首要考慮因素,並加強了電子設計自動化 (EDA) 供應商和代工廠之間的合作,以平衡速度和效率。實現節能設計的供應商的產品在智慧型手機、筆記型電腦和工業IoT終端中得到廣泛應用,進一步鞏固了這些促進因素對微處理器市場的中期影響。
人工智慧加速器和邊緣運算的應用場景不斷擴展
從智慧攝影機到工業機器人,邊緣設備對嵌入式神經網路引擎的需求日益成長,這些引擎能夠消除對雲端後端推理處理的依賴。 AMD 的 Instinct MI350 加速器系列預計將於 2025 年底廣泛上市,其運算密度提升了四倍,標誌著專用 AI 晶片的時代已經到來。為了滿足用戶對隱私和延遲的期望,設備製造商已將類似的引擎整合到通用處理器中。因此,需求已從資料中心 GPU 擴展到穿戴式裝置和汽車控制單元中的低功耗推理核心。隨著客戶加快產品更新換代以獲得 AI 功能,微處理器市場也出現了短期需求激增。
傳統個人電腦出貨量出現結構性下滑
隨著企業延長產品更新周期,消費者轉向行動裝置,筆記型電腦和桌上型電腦的出貨量放緩。製造商不得不調整通路庫存,這抑制了主流CPU的日常需求。供應商透過將AI賦能型PC定位為更換的觸發因素來緩解此影響,但2025年出貨量復甦仍不盡人意。這個短期不利因素使整體複合年成長率下降了0.5個百分點,但也促使現有晶圓廠轉型用於新興產品類別。
細分市場分析
從微處理器市場規模來看,CPU在2025年仍將維持51.85%的銷售佔有率,持續成為串列工作負載的關鍵元件。同時,GPU預計到2031年將以9.95%的複合年成長率成長,凸顯了人工智慧、圖形和科學模擬等領域向大規模並行工作負載的轉變。隨著資料中心營運商增加加速卡,獨立GPU的供應管道不斷擴大,而消費性設備也開始採用低功耗版本進行設備內推理。將CPU和GPU核心整合在單一晶片上的APU,在對基板空間和電池續航時間要求較高的細分市場中佔據了一席之地。
獨立GPU受惠於高頻寬記憶體技術的進步,訓練吞吐量顯著提升,促使超大規模超大規模資料中心業者簽訂多年供貨合約以確保供給能力。 FPGA在通訊基礎設施中繼續發揮關鍵作用,5G和新興的6G標準都需要可程式邏輯。 DSP繼續用於音訊和基頻處理,但部分市場佔有率已轉向整合向量擴展的通用核心。專用積體電路(ASIC)在大規模生產的AI推理設備中得到應用,表明如果產量足以抵消非重複性開發成本(NRE),客製化晶片的性能可以超越可編程產品。
在微處理器市場,x86晶片預計到2025年將佔據45.95%的市場佔有率,這得益於其數十年來強大的軟體相容性。 RISC-V預計以13.20%的複合年成長率成長,在對成本敏感的嵌入式應用和以開放標準為導向的學術研究計畫中越來越受歡迎。基於Arm架構的設計正進一步滲透到資料中心和汽車領域,這得益於其高能源效率和不斷擴展的伺服器級軟體棧。
各廠商的藍圖呈現分化而非趨同的趨勢。英特爾和AMD將x86架構發展到3奈米以下的製程節點,旨在維持其在單執行緒效能方面的領先地位。 RISC-V專家則專注於發展特定領域的擴展,例如向量指令和加密指令,以在物聯網和人工智慧加速器領域脫穎而出。 Arm的授權廠商則拓展了客製化核心設計的範圍,利用支援晶片組的多晶片封裝來滿足雲端工作負載的需求。指令集的這種多樣化推動了編譯器技術和工具鏈的創新,最終為開發者提供了更多選擇,並支持了更多元化的微處理器市場。
區域分析
預計到2025年,亞太地區將佔據微處理器市場41.95%的佔有率,複合年成長率(CAGR)為8.21%。這主要得益於中國龐大的電子組裝規模以及政府主導的晶圓代工擴張。日本的感測器和汽車產業生態系統確保了對混合訊號和安全關鍵型處理器的穩定需求。同時,在財政獎勵的支持下,韓國主要企業大力投資於3奈米以下製程節點。印度推出了半導體製造補貼政策,鼓勵跨國晶圓廠和本地設計服務公司在同一地點整合,從而創造了對中等製程節點的互補需求。
北美地區繼續保持第二大市場地位,這得益於超大規模雲端運算的擴張、汽車電氣化以及《晶片法案》(CHIPS Act)的激勵措施,該法案抵消了新建晶圓廠的資本投資風險。台積電承諾投資1,650億美元在美國建造三座工廠,這清楚表明,財政支持能夠有效改變國內產能配置。加拿大和墨西哥透過整合汽車電子和跨境物流,縮短一級供應商的前置作業時間,從而提升了區域發展動能。
在歐洲,受嚴格的車輛排放氣體法規和「工業4.0」現代化進程的推動,市場呈現逐步擴張的態勢。德國汽車製造商簽署了戰略性半導體供應協議,以確保其高級駕駛輔助系統(ADAS)藍圖的順利推進。同時,法國和英國利用當地研究機構,共同開發用於國防和航太任務的安全處理器。歐洲的《晶片法案》資助了試點生產線和先進封裝叢集,旨在減少對海外代工廠的依賴。儘管中東和非洲地區的微處理器市場絕對規模落後於其他地區,但海灣國家的資料中心專案和非洲各地的通訊基礎設施升級等相關設計應用,為長期進入更廣泛的微處理器市場奠定了基礎。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對高效能、高能源效率處理器的需求日益成長。
- 人工智慧加速器的激增和邊緣運算用例的擴展
- 超大規模資料中心的擴張和雲端工作負載的增加。
- 汽車電子領域的電氣化和ADAS的普及
- 基於晶片組的異質整合正在蓬勃發展。
- 政府對半導體(晶片類)的支援措施
- 市場限制因素
- 傳統個人電腦出貨量出現結構性下滑
- 先進節點的供應鏈產能限制依然存在。
- 尖端設備的出口限制/地緣政治限制
- 3奈米以下技術節點的研發成本不斷上升
- 宏觀經濟因素的影響
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依處理器類型
- 中央處理器(CPU)
- 圖形處理器(GPU)
- 加速處理單元(APU)
- 現場可程式閘陣列(FPGA)
- 數位訊號處理器(DSP)
- 專用積體電路(ASIC)
- 依指令集架構
- x86
- Arm
- RISC-V
- Power
- MIPS
- SPARC 及其他
- 透過製造製程節點
- 28奈米或更大
- 22~16 nm
- 14~10 nm
- 7~6 nm
- 5~4 nm
- 3奈米或更小
- 透過使用
- 家用電子產品
- 資料中心和企業伺服器
- 汽車和運輸業
- 工業自動化與機器人技術
- 航太/國防
- 醫療保健和醫療設備
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 其他南美國家
- 歐洲
- 德國
- 法國
- 英國
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Intel Corporation
- Advanced Micro Devices, Inc.
- NVIDIA Corporation
- Qualcomm Technologies, Inc.
- Taiwan Semiconductor Manufacturing Company Limited
- Samsung Electronics Co., Ltd.
- Apple Inc.
- Broadcom Inc.
- MediaTek Inc.
- HiSilicon Technologies Co., Ltd.
- NXP Semiconductors NV
- STMicroelectronics NV
- Texas Instruments Incorporated
- Marvell Technology, Inc.
- Microchip Technology Incorporated
- Analog Devices, Inc.
- Renesas Electronics Corporation
- Infineon Technologies AG
- SiFive, Inc.
- Alibaba Group Holding Ltd.(T-Head)
- Raspberry Pi Ltd.
- Rockchip Electronics Co., Ltd.
- GigaDevice Semiconductor(Beijing)Inc.
- Espressif Systems(Shanghai)Co., Ltd.
- VIA Technologies, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the microprocessor market size was valued at USD 109.12 billion in 2025 and estimated to grow from USD 115.85 billion in 2026 to reach USD 156.25 billion by 2031, at a CAGR of 6.17% during the forecast period (2026-2031).
This report is Segmented by Processor Type (CPU, GPU, APU, FPGA, DSP, and ASIC), Instruction-Set Architecture (x86, Arm, RISC-V, Power, MIPS, and More), Fabrication Node (>=28nm, 22-16nm, 14-10nm, 7-6nm, 5-4nm, and More), Application (Consumer Electronics, Datacentre and Enterprise Servers, Aerospace and Defence, and More), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa).
Global Microprocessor Market Trends and Insights
Growing Demand for High-Performance and Energy-Efficient Processors
Demand for processors that simultaneously deliver high throughput and low power consumption shaped vendor roadmaps throughout 2024 and 2025. Data-centre operators prioritized total cost of ownership, prompting designers to optimize performance per watt and integrate on-package memory to reduce latency. Consumer device makers followed suit, seeking battery-savvy chips that enable on-device AI inference without thermal throttling. The move toward smaller geometries such as 3 nm and below pushed leakage-current challenges to the forefront, intensifying cooperation between electronic-design-automation providers and foundries to balance speed and efficiency. Suppliers that delivered energy-efficient designs captured design wins in smartphones, notebooks, and industrial IoT endpoints, reinforcing this driver's medium-term influence on the microprocessor market.
Proliferation of AI Accelerators and Edge Computing Use-Cases
Edge devices, from smart cameras to industrial robots, increasingly require embedded neural engines that eliminate dependence on cloud back-ends for inference. AMD's Instinct MI350 accelerator family, scheduled for broad availability in late 2025, illustrated the push toward specialized AI silicon with a four-fold uplift in compute density. Device makers embedded similar engines inside general-purpose processors to address user privacy and latency expectations. As a result, demand broadened beyond data-centre GPUs to encompass low-power inference cores inside wearables and automotive control units. The short-term lift to the microprocessor market emerged as customers accelerated refresh cycles to gain AI capability.
Structural Decline in Traditional PC Shipments
Notebook and desktop volumes softened as enterprises extended refresh cycles and consumers turned to mobile form factors. Manufacturers confronted channel inventory corrections that depressed run-rate demand for mainstream CPUs. Vendors mitigated the impact by positioning AI-enabled PCs as a replacement catalyst, yet volume recovery remained partial through 2025. The short-term drag shaved 0.5 percentage points from the overall CAGR, yet also prompted repurposing of existing fabs toward emerging categories.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Hyperscale Data-Centres and Cloud Workloads
- Electrification and ADAS Adoption in Automotive Electronics
- Ongoing Supply-Chain Capacity Constraints for Advanced Nodes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The microprocessor market size for processor types showed CPUs retaining a 51.85% revenue share in 2025 as they remained indispensable for serial workloads. GPUs, however, posted a 9.95% CAGR outlook through 2031, underlining the shift toward massively parallel workloads in AI, graphics, and scientific simulation. The discrete-GPU pipeline expanded as data-centre operators added accelerator cards while consumer devices integrated low-power variants for on-device inference. APUs that fuse CPU and GPU cores on one die circled niche segments where board space and battery life mattered.
Discrete GPUs benefited from high-bandwidth-memory advances that multiplied training throughput, with hyperscalers locking in multiyear supply agreements to secure capacity. FPGAs preserved relevance in telecom infrastructure, where 5G and emerging 6G standards required programmable logic. DSPs continued to address audio and baseband processing, although some market share shifted toward general-purpose cores with embedded vector extensions. Application-specific integrated circuits claimed design wins in high-volume AI inference appliances, demonstrating that bespoke silicon can outpace programmable counterparts once volumes justify non-recurring engineering expense.
The microprocessor market registered x86 chips with a 45.95% share in 2025 on the strength of decades-old software compatibility. RISC-V, buoyed by its 13.20% CAGR forecast, gained traction among cost-sensitive embedded applications and academic research initiatives that valued open standards. Arm-based designs deepened penetration in data-centre and automotive sectors, leveraging a reputation for power efficiency and a growing server-class software stack.
Vendor roadmaps illustrated divergence rather than convergence. Intel and AMD advanced x86 to sub-3 nm nodes, aiming to sustain single-thread performance leadership. RISC-V specialists emphasized domain-specific extensions, such as vector and cryptography instructions, to differentiate in IoT and AI accelerators. Arm licensees broadened custom core designs, targeting cloud workloads with chiplet-enabled multi-die packages. The proliferation of instruction sets fostered innovation in compiler technologies and toolchains, ultimately expanding developer choice and supporting a more diverse microprocessor market.
Complete Report Scope:
- By Processor Type
- Central Processing Unit (CPU)
- Graphics Processing Unit (GPU)
- Accelerated Processing Unit (APU)
- Field-Programmable Gate Array (FPGA)
- Digital Signal Processor (DSP)
- Application-Specific Integrated Circuit (ASIC)
- By Instruction-Set Architecture
- x86
- Arm
- RISC-V
- Power
- MIPS
- SPARC and Others
- By Fabrication Node
- >=28 nm
- 22-16 nm
- 14-10 nm
- 7-6 nm
- 5-4 nm
- 3 nm and Below
- By Application
- Consumer Electronics
- Datacentre and Enterprise Servers
- Automotive and Transportation
- Industrial Automation and Robotics
- Aerospace and Defence
- Healthcare and Medical Devices
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held a 41.95% share of the microprocessor market in 2025 and posted an 8.21% CAGR outlook, sustained by China's electronics assembly scale and government-backed foundry expansion. Japan's sensor and automotive ecosystems ensured steady demand for mixed-signal and safety-critical processors, while South Korea's champions pressed ahead with below-3 nm node investments supported by fiscal incentives. India rolled out chip-manufacturing subsidies that encouraged multinational fabs and local design-service firms to co-locate, adding complementary demand for mid-tier nodes.
North America remained the second-largest region, buoyed by hyperscale cloud build-outs, automotive electrification, and the CHIPS Act incentives that offset capital-expenditure risk for new fabs. TSMC's USD 165 billion commitment to three United States plants underlined how fiscal support can redirect capacity allocation to domestic soil. Canada and Mexico supported regional momentum through automotive electronics and cross-border logistics integration that shortened lead times for Tier-1 suppliers.
Europe delivered moderate expansion on the back of stringent vehicle-emissions rules and Industry 4.0 modernization. Germany's automakers locked in strategic silicon supply agreements to safeguard ADAS roadmaps, while France and the United Kingdom tapped local research institutes to co-develop secure processors for defense and aerospace missions. The European Chips Act channeled funds into pilot lines and advanced packaging clusters that aimed to reduce dependency on overseas foundries. The Middle East and Africa trailed in absolute volumes yet registered design-win activity tied to data center projects in the Gulf states and telecom infrastructure upgrades across Africa, setting the stage for long-term participation in the wider microprocessor market.
- Intel Corporation
- Advanced Micro Devices, Inc.
- NVIDIA Corporation
- Qualcomm Technologies, Inc.
- Taiwan Semiconductor Manufacturing Company Limited
- Samsung Electronics Co., Ltd.
- Apple Inc.
- Broadcom Inc.
- MediaTek Inc.
- HiSilicon Technologies Co., Ltd.
- NXP Semiconductors N.V.
- STMicroelectronics N.V.
- Texas Instruments Incorporated
- Marvell Technology, Inc.
- Microchip Technology Incorporated
- Analog Devices, Inc.
- Renesas Electronics Corporation
- Infineon Technologies AG
- SiFive, Inc.
- Alibaba Group Holding Ltd. (T-Head)
- Raspberry Pi Ltd.
- Rockchip Electronics Co., Ltd.
- GigaDevice Semiconductor (Beijing) Inc.
- Espressif Systems (Shanghai) Co., Ltd.
- VIA Technologies, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for high-performance and energy-efficient processors
- 4.2.2 Proliferation of AI accelerators and edge computing use-cases
- 4.2.3 Expansion of hyperscale data-centres and cloud workloads
- 4.2.4 Electrification and ADAS adoption in automotive electronics
- 4.2.5 Chiplet-based heterogeneous integration gaining traction
- 4.2.6 Government semiconductor incentive programmes (CHIPS-style)
- 4.3 Market Restraints
- 4.3.1 Structural decline in traditional PC shipments
- 4.3.2 Ongoing supply-chain capacity constraints for advanced nodes
- 4.3.3 Export-control/geopolitical limits on leading-edge equipment
- 4.3.4 Escalating R&D costs below the 3 nm technology node
- 4.4 Impact of Macroeconomic Factors
- 4.5 Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Processor Type
- 5.1.1 Central Processing Unit (CPU)
- 5.1.2 Graphics Processing Unit (GPU)
- 5.1.3 Accelerated Processing Unit (APU)
- 5.1.4 Field-Programmable Gate Array (FPGA)
- 5.1.5 Digital Signal Processor (DSP)
- 5.1.6 Application-Specific Integrated Circuit (ASIC)
- 5.2 By Instruction-Set Architecture
- 5.2.1 x86
- 5.2.2 Arm
- 5.2.3 RISC-V
- 5.2.4 Power
- 5.2.5 MIPS
- 5.2.6 SPARC and Others
- 5.3 By Fabrication Node
- 5.3.1 >=28 nm
- 5.3.2 22-16 nm
- 5.3.3 14-10 nm
- 5.3.4 7-6 nm
- 5.3.5 5-4 nm
- 5.3.6 3 nm and Below
- 5.4 By Application
- 5.4.1 Consumer Electronics
- 5.4.2 Datacentre and Enterprise Servers
- 5.4.3 Automotive and Transportation
- 5.4.4 Industrial Automation and Robotics
- 5.4.5 Aerospace and Defence
- 5.4.6 Healthcare and Medical Devices
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Intel Corporation
- 6.4.2 Advanced Micro Devices, Inc.
- 6.4.3 NVIDIA Corporation
- 6.4.4 Qualcomm Technologies, Inc.
- 6.4.5 Taiwan Semiconductor Manufacturing Company Limited
- 6.4.6 Samsung Electronics Co., Ltd.
- 6.4.7 Apple Inc.
- 6.4.8 Broadcom Inc.
- 6.4.9 MediaTek Inc.
- 6.4.10 HiSilicon Technologies Co., Ltd.
- 6.4.11 NXP Semiconductors N.V.
- 6.4.12 STMicroelectronics N.V.
- 6.4.13 Texas Instruments Incorporated
- 6.4.14 Marvell Technology, Inc.
- 6.4.15 Microchip Technology Incorporated
- 6.4.16 Analog Devices, Inc.
- 6.4.17 Renesas Electronics Corporation
- 6.4.18 Infineon Technologies AG
- 6.4.19 SiFive, Inc.
- 6.4.20 Alibaba Group Holding Ltd. (T-Head)
- 6.4.21 Raspberry Pi Ltd.
- 6.4.22 Rockchip Electronics Co., Ltd.
- 6.4.23 GigaDevice Semiconductor (Beijing) Inc.
- 6.4.24 Espressif Systems (Shanghai) Co., Ltd.
- 6.4.25 VIA Technologies, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 微處理器市場預測至2034年—按架構、核心類型、裝置類型、製造技術、應用和地區分類的全球分析
 微處理器市場機會、成長要素、產業趨勢分析及2026年至2035年預測
 微處理器市場分析及預測(至2035年):依類型、產品類型、技術、組件、應用、最終用戶、功能、製程及部署類型分類
 2026年全球微處理器市場報告雙介面中央處理器(CPU)卡晶片全球市場報告(2026年)
 微處理器市場-全球產業規模、佔有率、趨勢、競爭格局、機會和預測:按類型、架構、技術格局、最終用戶、地區和競爭情況分類,2021-2031年
 伺服器FCBGA市場按裝置類型、基板類型、應用、I/O數量和最終用戶產業分類,全球預測,2026-2032年
 微處理器市場規模、佔有率、成長及全球產業分析:依類型、應用和地區劃分的洞察與預測(2026-2034)汽車微處理器市場-全球產業規模、佔有率、趨勢、機會及預測(依應用、技術、區域及競爭格局分類,2021-2031年預測)
 微處理器市場規模、佔有率和成長分析(按架構類型、應用、節點和地區分類)-2026-2033年產業預測